Open interest explained: calculation, units and positioning · 1 / 5
Reconstruct open interest from opening and closing trades
Every matched futures contract has a long and a short. In the conventional single-sided count, that pair contributes one unit of open interest. The key question is whether a trade creates a pair, removes a pair or transfers an existing position—not whether someone clicked Buy.
Athenum7 minUpdated:
How opening, closing and transfer trades change open interest
When a new long meets a new short, one contract is created and OI rises by one. When an existing short buys to close against an existing long selling to close, one contract disappears and OI falls by one. If one participant opens while the other closes, ownership changes and OI is unchanged. Volume still increases in all three cases.
The public trade feed generally tells you price, size and the aggressor side. It does not reveal each participant's complete account state. An aggressive buy can open a long or close a short. You therefore cannot reconstruct opening and closing activity exactly from a coloured trade tape alone. The ledger below exposes the hidden states for teaching; live feeds usually do not.
OI counting conventions and net change between observations
The conceptual ledger uses each long/short pair once. Exchange fields can use different reporting conventions. Current Bybit documentation distinguishes a summed-both-sides field from a single-sided field; units also differ between linear and inverse products. Normalise the documented convention before combining venues or comparing a vendor chart with an exchange screen.
Time matters too. A five-minute OI change is the net difference between two observations. Inside that interval, many pairs may open and close. A flat line does not prove inactivity, and an increase of ten does not mean only ten contracts traded. Missing or delayed observations make that inference still less reliable.
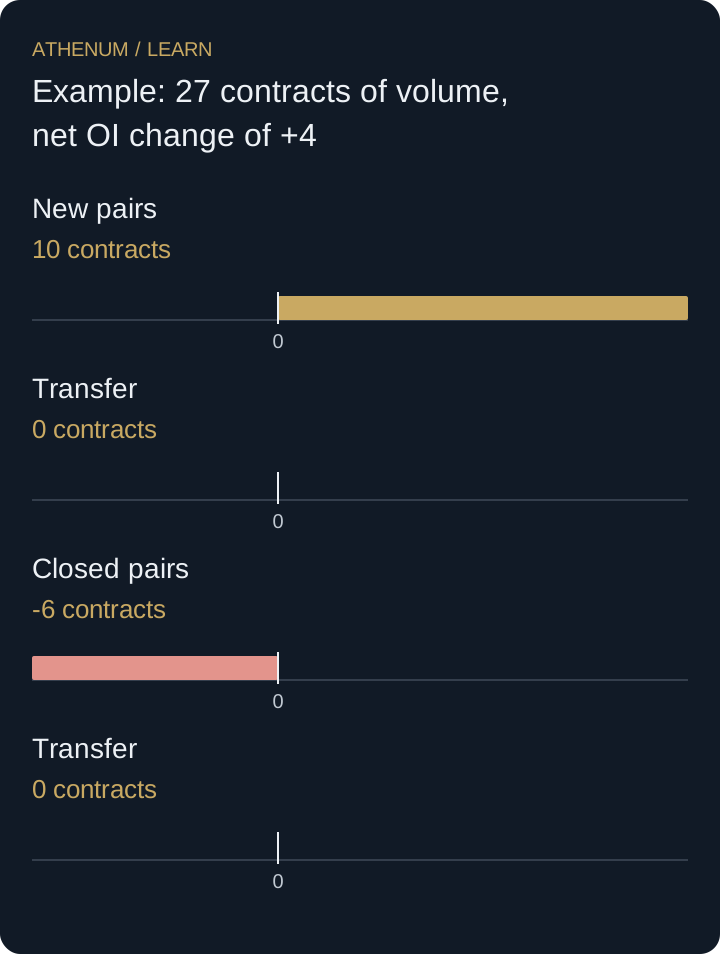
Example: 27 contracts of volume, net OI change of +4
Start with 100 outstanding pairs. Ten new longs match ten new shorts, increasing OI to 110. Seven existing longs then sell to seven new long holders while their short counterparties remain outstanding; that transfer leaves OI at 110. Six existing long/short pairs subsequently close, reducing OI to 104. A final transfer of four contracts leaves the count unchanged.
Total traded volume is 10 + 7 + 6 + 4 = 27 contracts. Net OI change is +10 − 6 = +4. Neither quantity tells us the number of distinct traders: one account can trade repeatedly, hold multiple contracts or offset exposure on another venue.
| Event | Volume | OI change | OI after |
|---|---|---|---|
| Both sides open | 10 | +10 | 110 |
| One side opens, one closes | 7 | 0 | 110 |
| Both sides close | 6 | −6 | 104 |
| Another transfer | 4 | 0 | 104 |
 Open full-size diagram
- New pairs: 10 contracts
- Transfer: 0 contracts
- Closed pairs: -6 contracts
- Transfer: 0 contracts
Rising OI does not mean more longs than shorts
The new long and new short are created together. Price may rise because aggressive demand meets available offers, but the OI total cannot tell you which side is better informed, more leveraged or hedged elsewhere. A claim that OI alone proves net bullish positioning asks the field to reveal information it does not contain.
Before acting
- Identify single-sided versus summed-both-sides reporting.
- Check contracts, base-asset units and quote notional before comparison.
- Separate traded volume from the net outstanding-position change.
- Treat aggressor direction and opening/closing status as different facts.
Check your understanding
OI starts at 200. Twelve pairs open, nine pairs close and 30 contracts transfer. What are ending OI and total traded volume?
Show the explained answer
Ending single-sided OI is 200 + 12 − 9 = 203. Volume is 12 + 9 + 30 = 51 contracts. Transfers contribute to volume but not the OI total; the ledger says nothing about the number of unique traders.
Sources and further reading
Continue with Athenum
From the Athenum blog
Open Interest One Side or Both, and Most Venues Never Say Which
Related lessons
- Open interest vs volume: check each interval for consistency
Compare open interest changes with traded volume in matching contract units. Find interval-level discrepancies that disappear in daily totals.
- Distinguish crowded positioning from a squeeze
Use funding and open interest as context for crowded positioning. Require an adverse price move and forced-flow evidence before calling it a squeeze.