Open interest explained: calculation, units and positioning · 2 / 5
Read the price–open interest matrix as competing hypotheses
Price up with OI up is an observation. “New informed longs will drive the next move” is a hypothesis. Keeping those sentences separate lets you investigate useful patterns without pretending the data identifies every participant.
Athenum7 minUpdated:
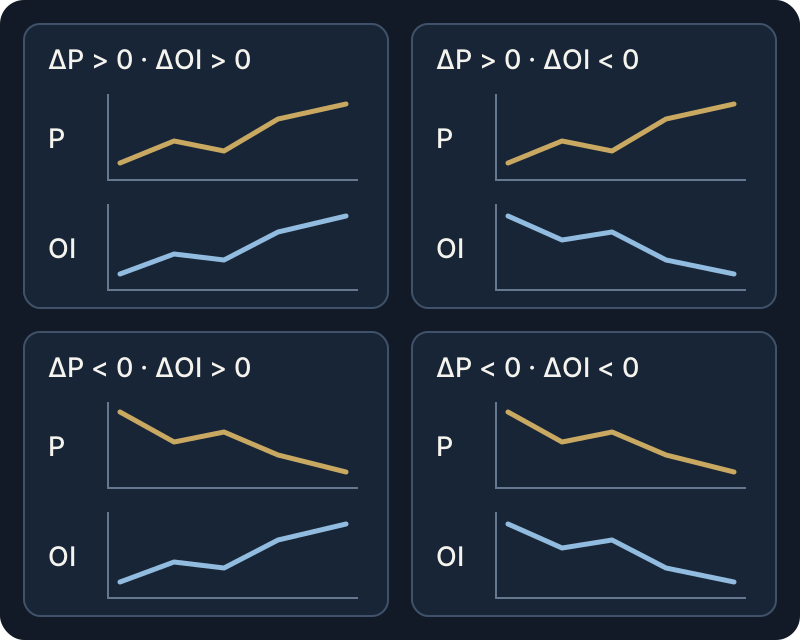
The price vs open interest matrix: what the four combinations mean
Use the same instrument and time window for price and OI. Choose an OI series that removes simple price revaluation where possible, or explicitly account for it. In a single-sided contract or base-unit series, rising OI means more outstanding exposure; falling OI means fewer outstanding pairs. Neither observation identifies the winning side.
With price rising and OI rising, new exposure accompanies the advance, but shorts also enter. With price rising and OI falling, net closures accompany the rise; short covering is one possible contributor. Price falling with OI rising adds exposure during a decline. Price falling with OI falling removes exposure during a decline, possibly including long liquidations. The words “possible” and “net” do real work here.
Add flow, liquidation and spot data, then define invalidation
Executed flow can describe which side crossed the spread. Liquidation messages can identify reported forced-close activity within their documented coverage. Spot behaviour can help distinguish a derivatives-led move from wider demand. None provides a complete map of trader intentions, and several indicators derived from the same trades are not independent confirmations.
Before entry, define what would make the hypothesis less credible. For example, if you expect an upside breakout to hold, sustained trading back inside the range may invalidate the setup even while OI remains elevated. The outcome should be judged against that predeclared condition, not against a new narrative invented after the move.
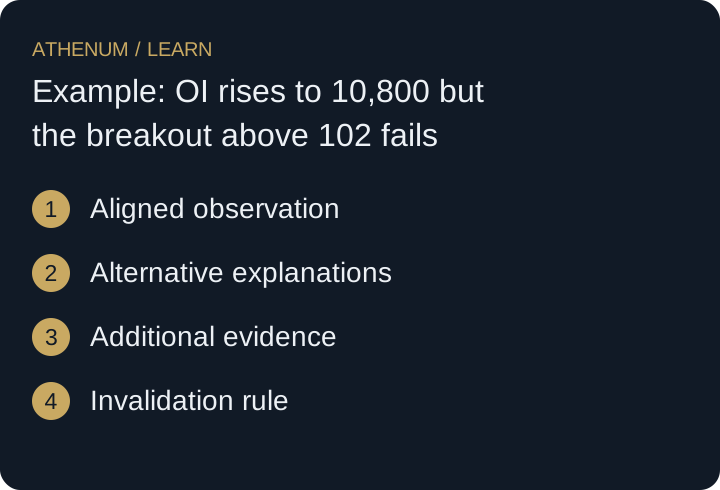
Example: OI rises to 10,800 but the breakout above 102 fails
An asset rises from 100 to 103 while normalised OI increases from 10,000 to 10,800 contracts. One explanation is aggressive new buying meeting new short supply. Another is new short hedging against demand from participants with positions elsewhere. The aggregate observations are compatible with both.
Suppose you are testing a breakout above 102. You require two completed five-minute closes above 102 and a retest that does not close below 101.80. Those thresholds are illustrative research rules, not a proven edge. If price subsequently closes at 101.50, the price condition fails. The fact that OI is still 10,750 does not rescue the trade.
| Price | Normalised OI | What can be said |
|---|---|---|
| Up | Up | Exposure grows during an advance |
| Up | Down | Net closures accompany an advance |
| Down | Up | Exposure grows during a decline |
| Down | Down | Net closures accompany a decline |
 Open full-size diagram
- Aligned observation
- Alternative explanations
- Additional evidence
- Invalidation rule
Why price down with falling OI does not mark the bottom
Price down and OI down is often labelled “the bottom.” Yet forced selling can persist, discretionary sellers may continue and fresh shorts can replace closed positions. Falling OI explains an inventory change, not the end of supply. Waiting for a predefined reclaim or acceptance condition sacrifices immediacy but gives the hypothesis an observable test.
Before acting
- Align venue, instrument, timestamps and OI units.
- Describe the observed quadrant before assigning a cause.
- Write at least one plausible alternative explanation.
- Specify a price or data condition that rejects the setup.
Check your understanding
Price rises 3% and USD-denominated OI also rises 3%. Is this enough to classify the move as new exposure entering?
Show the explained answer
No. If the base quantity is unchanged, price revaluation alone can raise USD notional by 3%. Inspect the contract or base-unit series and the reporting convention before using the matrix. Even a confirmed quantity increase would not identify the dominant trader motive.
Sources and further reading
Continue with Athenum
From the Athenum blog
Open Interest and Price: How to Read the Four Regimes of a Crypto Move
Related lessons
- Distinguish crowded positioning from a squeeze
Use funding and open interest as context for crowded positioning. Require an adverse price move and forced-flow evidence before calling it a squeeze.
- Long/short ratio: compare account counts with position size
Calculate long-holder share, the account ratio and open interest from one ledger. More long accounts do not prove greater long exposure in the market.