The decision before the data
Compare 3,330 historical Bitcoin funding settlements: contract-specific timing, signed payments and receipts, and fee thresholds with explicit assumptions.
| Your question | What to compare | What this cannot establish |
|---|---|---|
| Hold through settlement? | Check the instrument’s eligibility window and funding sign. | Published timestamps do not guarantee last-second execution eligibility. |
| Close and reopen? | Compare the signed payment with both fill fees and changed exposure. | The 0.10% fee comparison is an assumption, not your fee tier. |
| Use the historical ranking? | Compare only matching windows and funding-notional definitions. | Rate sums are proxies; Gate.io has shorter coverage and currency conversion is separate. |
Practise with worked lessons
- Test a funding-settlement trade after all costs
Opening just before funding and closing just after looks easy. A 30 USDT receipt cannot cover 100 USDT of fees and slippage even before price moves.
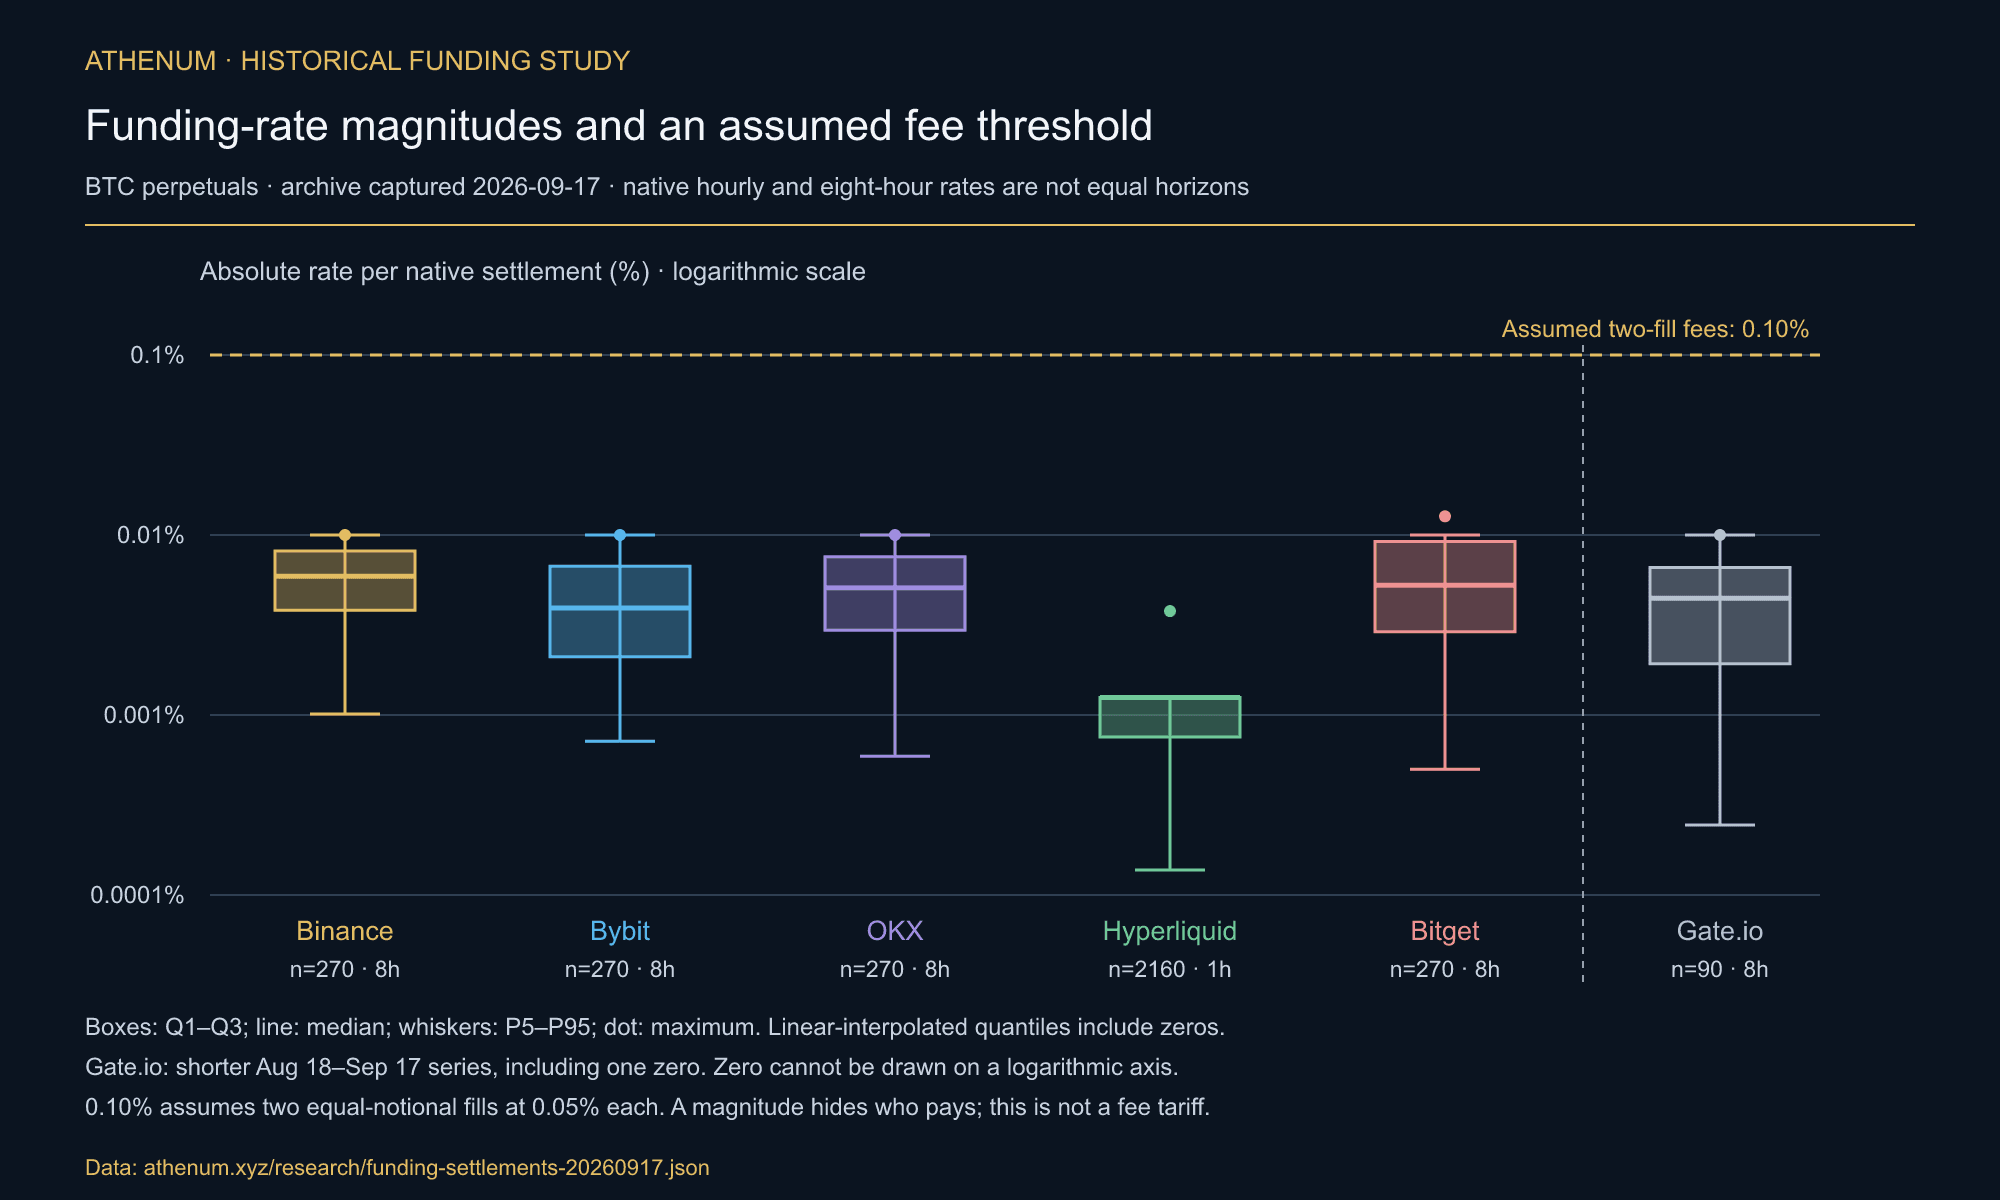
Review 2026-10-23: the archived funding-rate calculations were reproduced; 540 Binance and Bybit records also matched a new historical exchange query. These are rate-based cost proxies, not account statements. The earlier open-interest market-share claim was withdrawn because its comparable contract coverage and counting basis could not be verified. The revised figures retain the historical funding observations and make fee assumptions explicit. Deribit funding Data JSON Hyperliquid funding Binance funding Bybit funding
TLDR. For contracts with discrete funding, eligibility depends on holding a position during the contract’s settlement processing window. Continuous funding, such as Deribit’s, works differently. Our archived Bitcoin sample contains 3,330 settlements: 270 each on Binance, Bybit, OKX and Bitget, 2,160 hourly observations on Hyperliquid, and a separate shorter Gate.io series of 90. The largest absolute rate was 0.0127%; it was negative, so longs received funding. Compare the signed payment you would avoid with your own execution costs and changed price exposure, not with a universal claim that exiting before funding is profitable or cost-free.
When is funding actually charged on a Bitcoin perpetual?
For the discrete-settlement contracts in this study, being eligible at settlement determines whether a position pays or receives funding. Closing between settlements can avoid a payment, but opening or closing near the advertised time does not guarantee which side of processing the position falls on. Check the specific instrument’s current rules. The historical rate timestamps show eight-hour gaps for Binance, Bybit, OKX and Bitget and hourly gaps for Hyperliquid; they do not measure account posting delays. Deribit accrues funding continuously. Only if its eight-hour rate and funding notional stay constant does one minute correspond to 1/480 of that eight-hour charge. The Athenum explainer on perpetual futures introduces these different mechanisms.
A funding interval belongs to an instrument and a time period. The observed Bitcoin clocks below are evidence about this sample, not a permanent exchange-wide schedule or a measure of each venue’s market share.
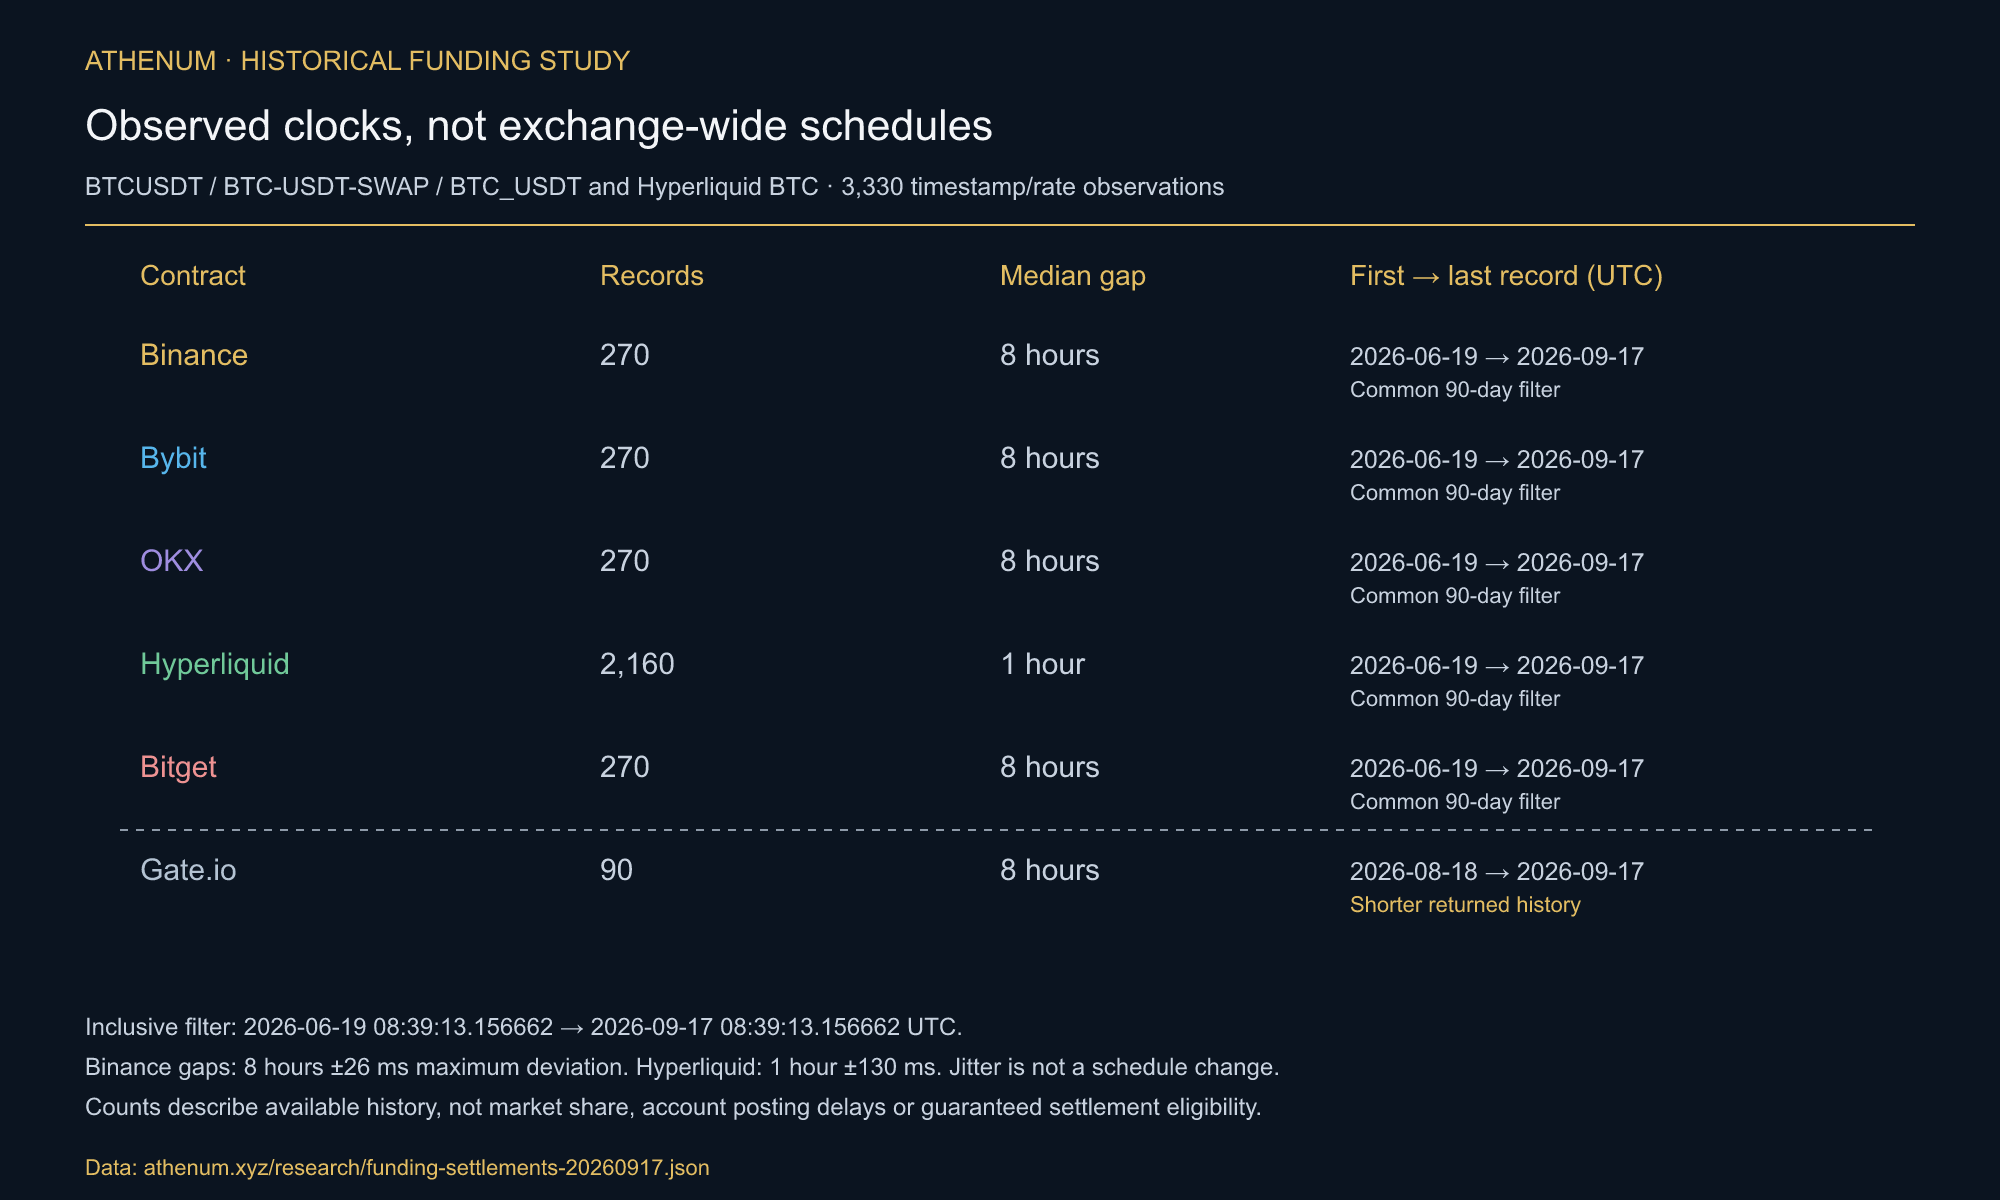
Observed settlement clocks: 270 eight-hour records each for Binance, Bybit, OKX and Bitget, and 2,160 hourly Hyperliquid records in the common filter. Gate.io returned 90 records from 2026-08-18 to 2026-09-17 and is shown separately.
The first retained eight-hour record is 2026-06-19 16:00 UTC; the first hourly record is 09:00 UTC that day. All five full samples end at the 2026-09-17 08:00 UTC settlement, with small timestamp offsets on some venues. Binance’s gaps deviate from eight hours by at most 26 ms and Hyperliquid’s from one hour by at most 130 ms. Such recording jitter does not prove that the funding interval changed.
What do the rates imply for a constant funding notional?
The archive applies an inclusive timestamp filter from 2026-06-19 08:39:13.156662 UTC through 2026-09-17 08:39:13.156662 UTC. Summing the signed rates yields 1.056493% to 1.97375668% over that window for the five complete samples. These are sums of settlement rates relative to a constant reference notional, not observed cash flows of a fixed-coin trade. Gate.io’s shorter returned series is excluded from this comparison.
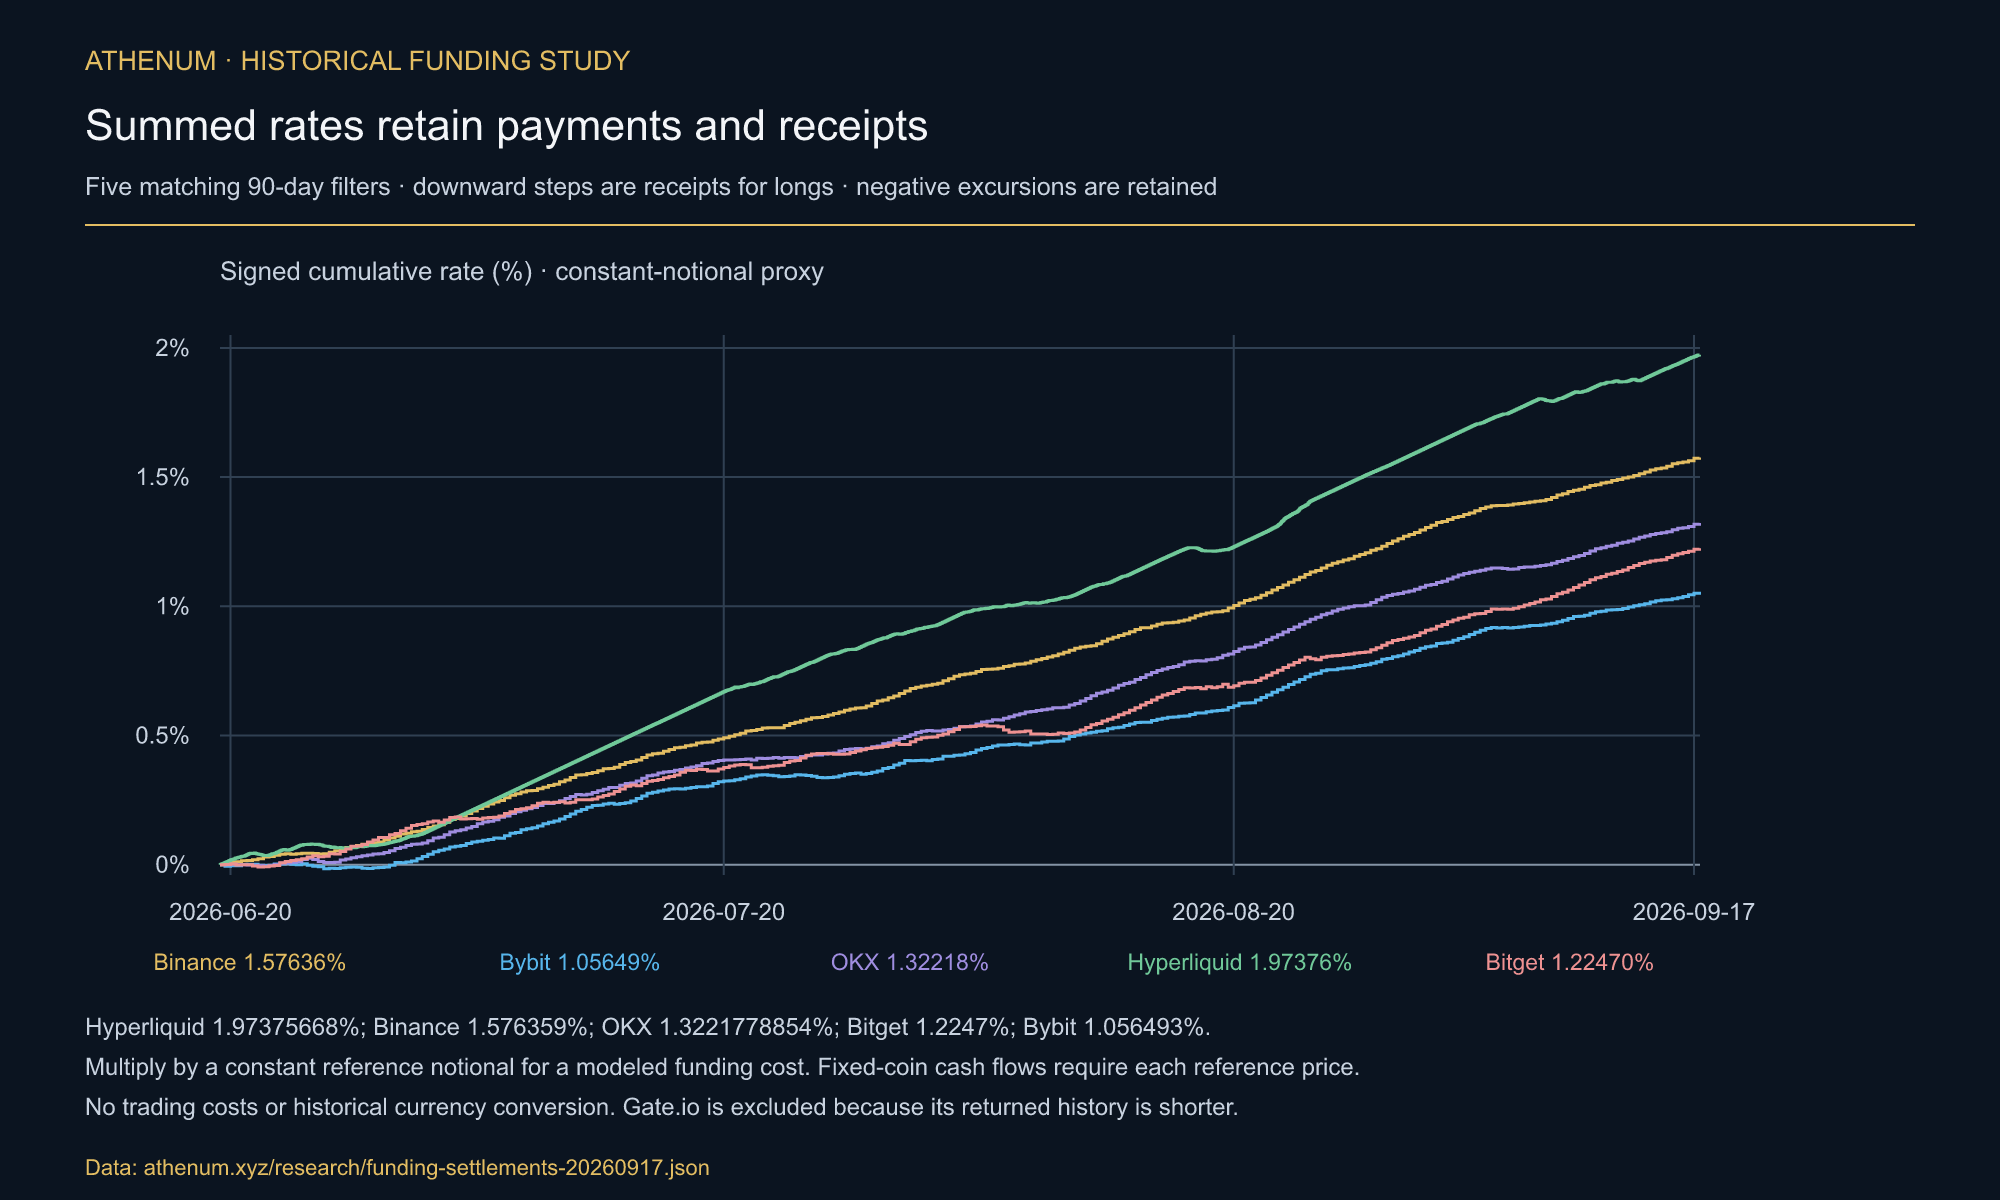
Signed cumulative rate sums in the common window: Hyperliquid 1.97375668%, Binance 1.576359%, OKX 1.3221778854%, Bitget 1.2247% and Bybit 1.056493%. Each step is one archived settlement; a downward step represents a receipt for longs.
At a constant funding notional of 10,000 units of each contract’s settlement currency, the modeled net payments are 197.38 USDC on Hyperliquid, 157.64 USDT on Binance, 132.22 USDT on OKX, 122.47 USDT on Bitget and 105.65 USDT on Bybit. No historical USDC/USDT/USD conversion is assumed. Multiplying the rate sums by 365/90 gives simple annualized rates of 8.00%, 6.39%, 5.36%, 4.97% and 4.28%; these are neither APYs nor realized annual returns. Actual fixed-coin payments depend on each settlement’s quantity and contract-specific reference price: for example mark price on Binance/Bybit and oracle price on Hyperliquid. Trading costs needed to maintain a constant notional are outside this funding-only proxy. The funding rate cap study examines a different window; neither window establishes a lasting venue ranking.
Binance’s signed median rate was 0.0059085%, with the linearly interpolated middle half approximately 0.00382%–0.00814%, and 38 of 270 rates equaled 0.01000%. Hyperliquid had 1,287 of 2,160 rates equal to 0.00125% per hour. These repeated values are consistent with the interest component of the funding formula; a repeated rate alone does not prove a binding cap. The cover summarizes absolute rate sizes, a different quantity from signed rates, and includes all observations when computing its quantiles. The free funding rate calculator provides scenario calculations; the guide to funding intervals per symbol explains why current instrument rules still need checking.
Is it worth closing before the stamp to avoid funding?
In this sample the largest absolute single rate was 0.0127%, a Bitget payment to longs. The largest positive rate charged to longs was 0.01000%. Hyperliquid’s largest sum of eight consecutive hourly rates was 0.02223316%; those rolling windows overlap and are not independent observations. For an explicitly assumed fee of 0.05% on each of two equal-notional fills, fees total 0.10% of that notional. This assumed fee exceeds every sampled single-settlement magnitude, but it is not a verified tariff for every trader or venue. Against the 0.0127% magnitude, the equal-fill fee threshold is 0.00635% per side before spread, slippage and exposure changes; for a long that rate was a receipt, so avoiding it would forgo income. Maker fees, tiers and rebates can change the comparison.
With the same hypothetical 0.05% fee per fill and unchanged execution notionals, 270 additional close-and-reopen pairs (540 fills) sum to 27% of the reference notional in fees, excluding the initial entry and final exit common to both comparisons. Binance’s signed funding-rate sum was 1.576359%. This illustrates a fee threshold under stated assumptions, not a replay of an executable strategy. Real fill fees use each fill’s actual notional, and repeatedly being flat changes price exposure; spreads, slippage and re-entry gaps require separate evaluation.
A separate historical Binance query covers 1,000 settlements from 2025-09-17 16:00 UTC through 2026-08-16 16:00 UTC: 259 were negative and the largest absolute rate was 0.015178%, again a receipt for longs. A new query on 2026-10-23 reproduced these aggregate counts and extremes. The longer sample shares 175 exact timestamps with the 90-day sample and is not independent. Its maximum also remains below the assumed 0.10% equal-notional round-trip fee; this does not bound rates in other periods.
Use the payment’s sign, your fee tier and the actual execution notionals before changing a trade. Exchanges can process funding around the displayed time, so a last-second exit is not a guarantee of avoiding settlement. If you planned to close anyway, moving the exit earlier may change funding eligibility, but it also changes the exit price and exposure. It is therefore not cost-free, and this study does not establish a universally best exit time.
What does a stamp dodger give up when funding turns negative?
When funding is negative, eligible longs receive and shorts pay. A flat position misses that receipt as well as avoiding any payment at other settlements. The positive and negative totals below describe this particular instrument and sample; they are not permanent properties of a venue.
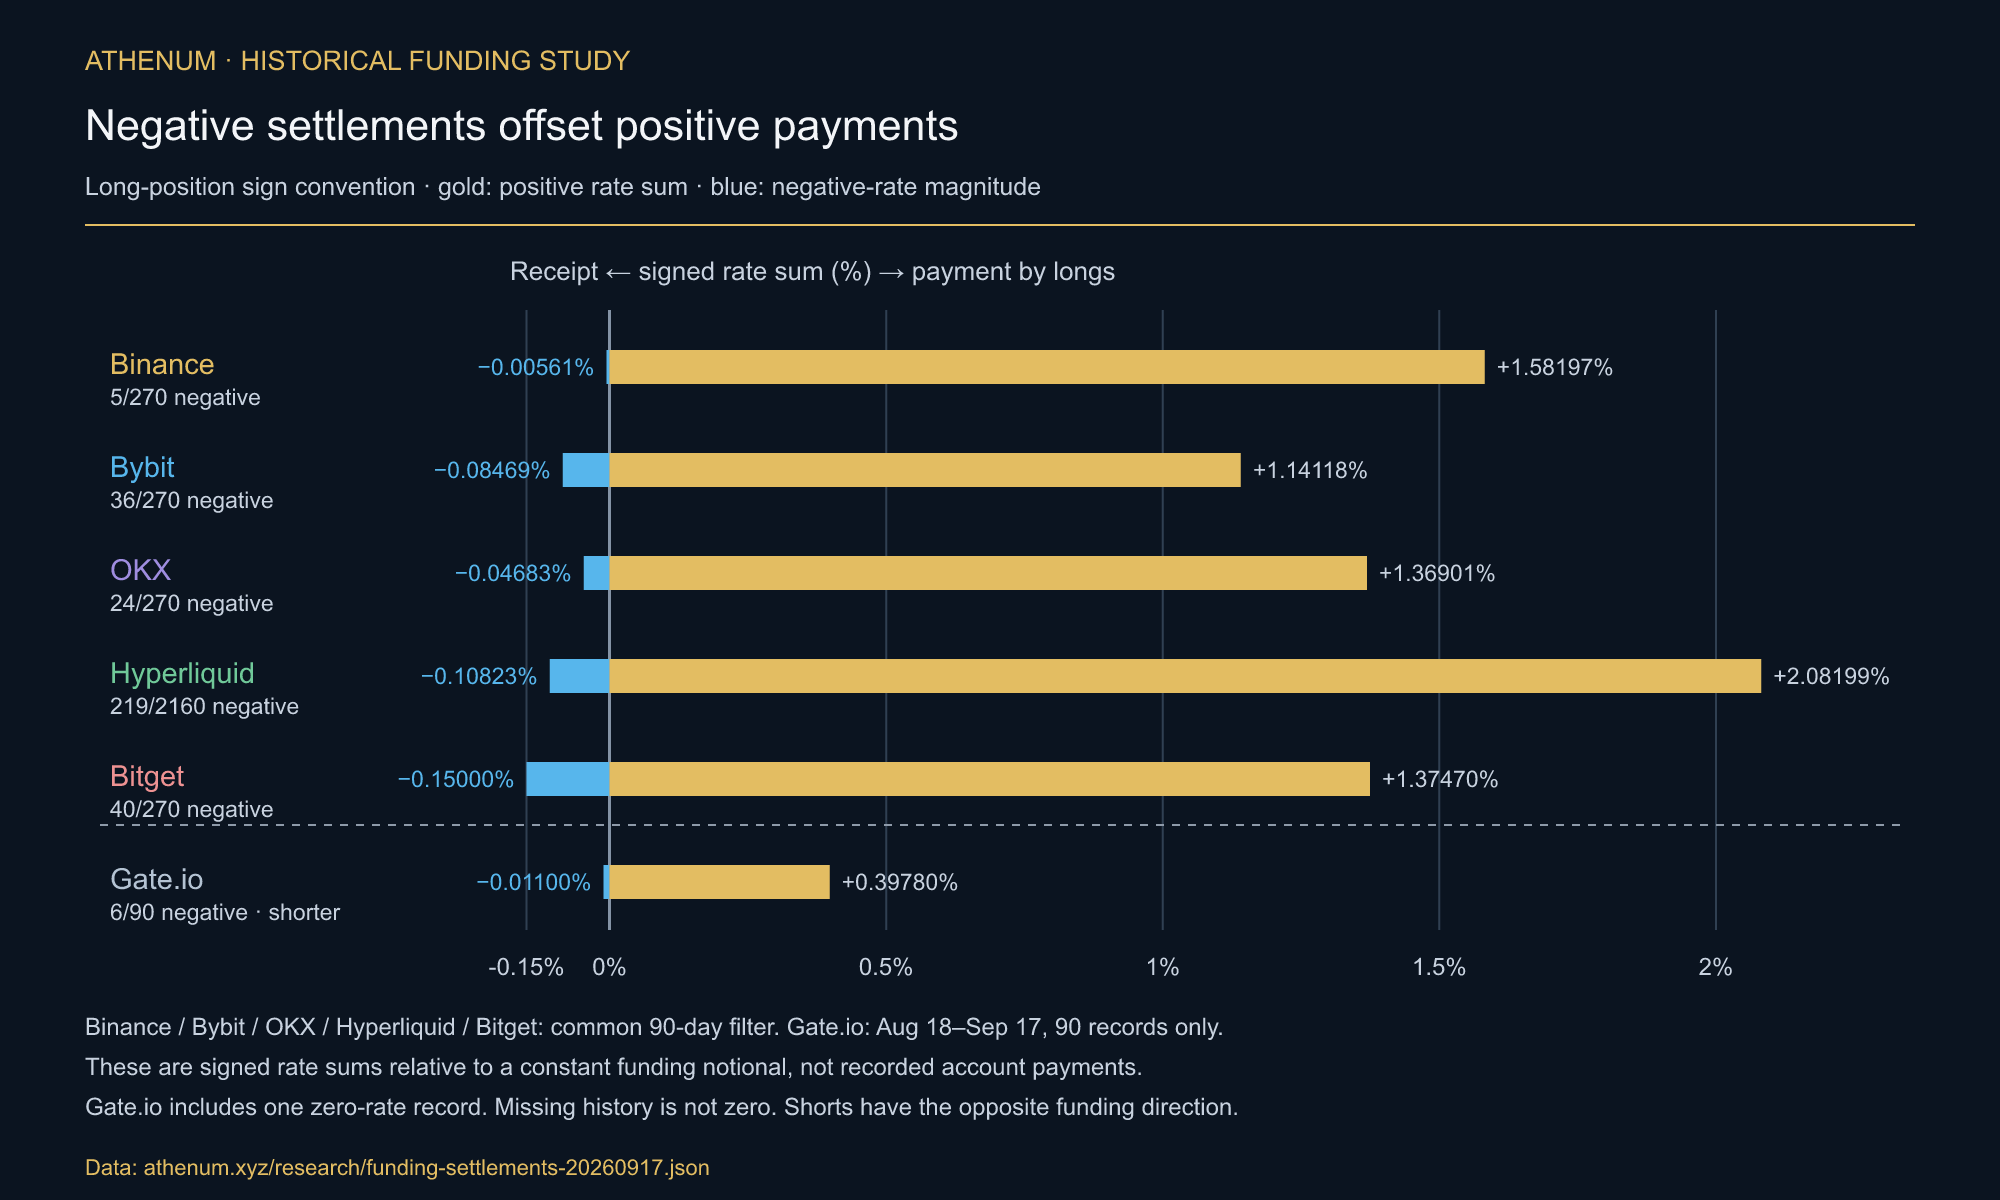
In the common sample Binance’s positive rates sum to 1.581967% and its negative-rate magnitudes to 0.005608%, with 5 negative settlements out of 270. Bitget’s corresponding sums are 1.3747% and 0.15%, with 40 negative settlements. Gate.io’s shorter 90-record series is labeled separately.
The other negative counts and receipt-rate sums are Bybit 36/270 and 0.084686%, OKX 24/270 and 0.0468278284%, and Hyperliquid 219/2,160 and 0.10823201%. Gate.io has 6 negative records out of 90 and a 0.011% receipt-rate sum. Receipts offset payments; their importance depends on the trade’s funding notional and holding window. A negative funding rate is a signed cash-flow input, not a reason to disregard it as a rounding error. The PnL calculator covers price PnL and trading fees, excluding funding; reconcile signed funding separately. Funding before settlement examines how indicative rates can differ from the eventual settlement.
How would you reproduce this?
The downloadable archive preserves normalized public timestamp/rate pairs captured on 2026-09-17, the original calculation method and an independent recheck. Complete original HTTP response envelopes were not retained. A historical exchange requery on 2026-10-23 matched all 270 Binance and 270 Bybit timestamps and rates exactly; the other archived series were recalculated, not independently recollected at their original capture time.
1. Read the contract-specific funding history: Binance BTCUSDT, Bybit linear BTCUSDT, OKX BTC-USDT-SWAP, Hyperliquid BTC, Bitget USDT futures BTCUSDT and Gate.io BTC_USDT. Inspect HTTP status and body-level errors, preserve field definitions and follow each endpoint’s pagination. For this OKX archive the acquisition script selected realizedRate when supplied; an indicative fundingRate is not interchangeable with a settled rate.
2. Apply explicit timestamp boundaries before comparing series. This archive uses the inclusive bounds stated above; record counts and timestamp gaps are retained. Gate.io’s returned history begins on 2026-08-18 and is not a complete 90-day sample. Keep its sums separate rather than filling missing earlier periods with zero.
3. Inspect the median, minimum and maximum timestamp gaps, then distinguish ordinary timestamp jitter, missing observations and genuine schedule changes. Different gap statistics alone do not prove an interval change. Check instrument metadata and settlement records around a suspected change; do not infer a permanent interval from the exchange name.
4. Sum signed rates only for a constant-notional proxy. For actual cash flows use each settlement’s position quantity, contract-specific reference price, rate and direction. Inverse contracts require their own formula. Keep positive payments, negative receipts and zero-rate records separate; missing records are not zero payments.
5. Compare the relevant signed funding payment with fees on both actual execution notionals and with spread, slippage and changed price exposure. The 0.10% fee line here is an explicit equal-notional example at 0.05% per fill. Replace those assumptions with your applicable terms; they are not a historical or current tariff claim.
This is a dated study with a fixed archive, not a current funding forecast. The five complete series, the shorter Gate.io series and the overlapping 1,000-record Binance comparison have different coverage. A fresh pull can answer a new question, but it must not silently replace this archive or its original observation window.
Use the free funding rate calculator for explicit funding scenarios and the live terminal to inspect current observations. Check each instrument’s settlement rule and source time before comparing venues. The historical calculations and their limitations remain available in the linked data.
One terminal. All the data.
Liquidations, orderbook depth, whale walls & open interest, all real-time, in one place. 29 supported exchanges; coverage differs by tool.
No credit card required

Athenum Analytics
Athenum Analytics is our three-person editorial team covering crypto derivatives, market data and macroeconomic context.