Range trading: breakout acceptance, volume profile and VWAP
Define a range before the breakout, map uncertain cost zones and combine price acceptance with profiles, VWAP and session context.
What you will practise
Create a range study that another reader can reproduce without knowing the later outcome.
Before you start
- Complete the Open interest course, especially the limits of inferred cohorts.
- Understand invalidation, execution costs and price-based trade rules.
Course outline
- 1
Define a locked-in range as a hypothesis you can test
Fix range boundaries and an observation window, measure normalised open interest growth and test the breakout without assuming the same traders stay locked in.
8 minIn short: A locked-in range is a hypothesis: fix instrument, venues, timezone, window and boundary rule, measure normalised OI growth, and save the range before any departure. Rising OI shows net exposure growth, not which traders are trapped; test acceptance and invalidation across all qualifying ranges.
- 2
Map cost-adjusted break-even zones without inventing stops
Calculate long and short break-even zones from a hypothetical entry range. Include trading fees and funding while keeping the uncertainty about actual entries.
8 minIn short: For a linear position with a fixed all-in cost C per unit, break-even is entry + C for a long and entry − C for a short. Entries of 100–101 with 0.12 cost give a long zone of 100.12–101.12 and a short zone of 99.88–100.88; signed funding shifts them.
- 3
Define breakout acceptance before the breakout happens
Write a close-and-retest rule before the breakout, such as two five-minute closes and a retest. Account for the delay and keep failed breakouts in the sample.
8 minIn short: Write breakout acceptance before the outcome: a fixed rule such as two completed five-minute closes beyond the boundary plus a retest that holds, and an explicit failure rule. Enter no earlier than the final condition, size at the executable price, and keep qualified failures in the sample.
- 4
Calculate volume profile and VWAP from the same sample
The busiest price was 100, the volume-weighted average 102. Calculate volume profile and VWAP from the same trades and see why a value area is not a forecast.
8 minIn short: The point of control is the price bucket with the highest volume; VWAP is the sum of price × volume ÷ total volume over the same window. In the example the busiest price is 100 while VWAP is 1,530 ÷ 15 = 102, a feature of the distribution, not a broken indicator.
- 5
Choose timeframes and session context without moving the goalposts
Give context, setup and execution timeframes separate roles before entry. Align UTC timestamps, daylight-saving changes, funding events and incomplete candles.
8 minIn short: Assign each timeframe a role before entry: higher for context, intermediate for the setup, lower for the execution trigger. Use completed-candle or intrabar rules consistently, store timestamps in UTC, and keep the original invalidation and exclusion rules when another chart looks different.
Calculators used in this course
Related courses
- Volume profile and TPO: audit how profiles are builtReconstruct POC ties, value-area coverage, composite sessions, TPO counts and price-grid effects using original, checkable datasets.
- Order flow and CVD: absorption, footprints and data qualityCalculate delta from trades, compare spot and perpetual activity and distinguish a useful observation from a feed or classification artefact.
- Backtest bias: validate a trading strategy without hindsightAudit signal timing, ambiguous fills, confirmation filters, parameter searches and chronological holdouts with reproducible worked cases.
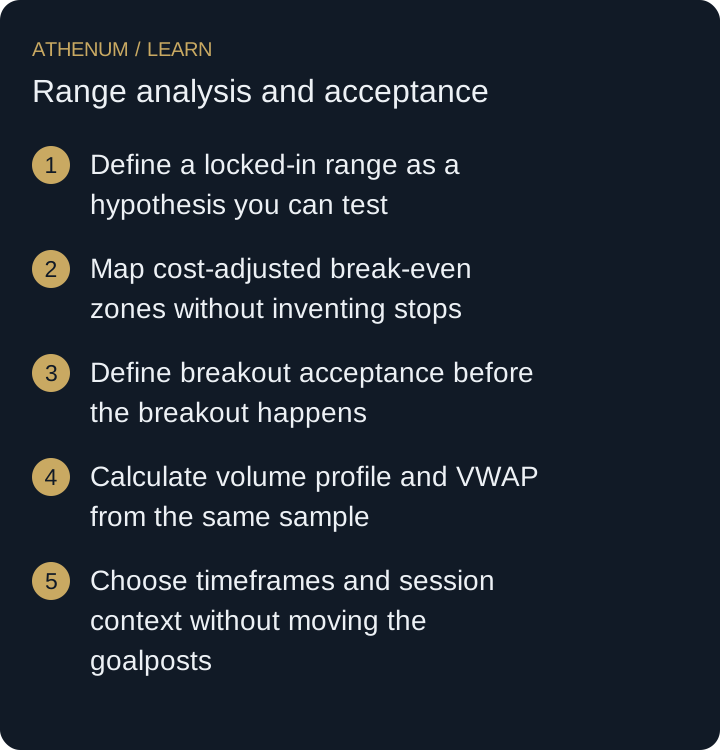 Open full-size diagram
- Define a locked-in range as a hypothesis you can test
- Map cost-adjusted break-even zones without inventing stops
- Define breakout acceptance before the breakout happens
- Calculate volume profile and VWAP from the same sample
- Choose timeframes and session context without moving the goalposts
Educational material. Examples do not establish a profitable strategy. Trading costs, gaps and liquidation can produce losses beyond a planned stop.