Funding Arbitrage Net Carry Calculator
Compare two spot/perpetual or perpetual/perpetual positions using settlement calendars, execution costs and committed capital.
Your financial inputs stay in this browser and are excluded from analytics.
Manual scenario · no live funding feed
Both legs must refer to the same underlying asset and USD-valued linear exposure. Inverse contracts are not modeled.
Enter assumptions and calculate to see a result.
Compare the funding scenario with current rates
Open the funding heatmapAthenum research: a measured example
When does funding outweigh trading fees?
In the 2026-09-08–2026-10-08 Binance BTCUSDT window, a $10,000 long paid $40.33 in funding against a $10 standard taker round trip. Cumulative funding crossed that fee at settlement 18, hour 136.
This is an observed historical path, not a six-day rule. Rates can turn negative and pay longs; fee tiers, execution and holding periods change the comparison. The PnL calculator excludes funding.
Published observation:
Read the measurement and its limits →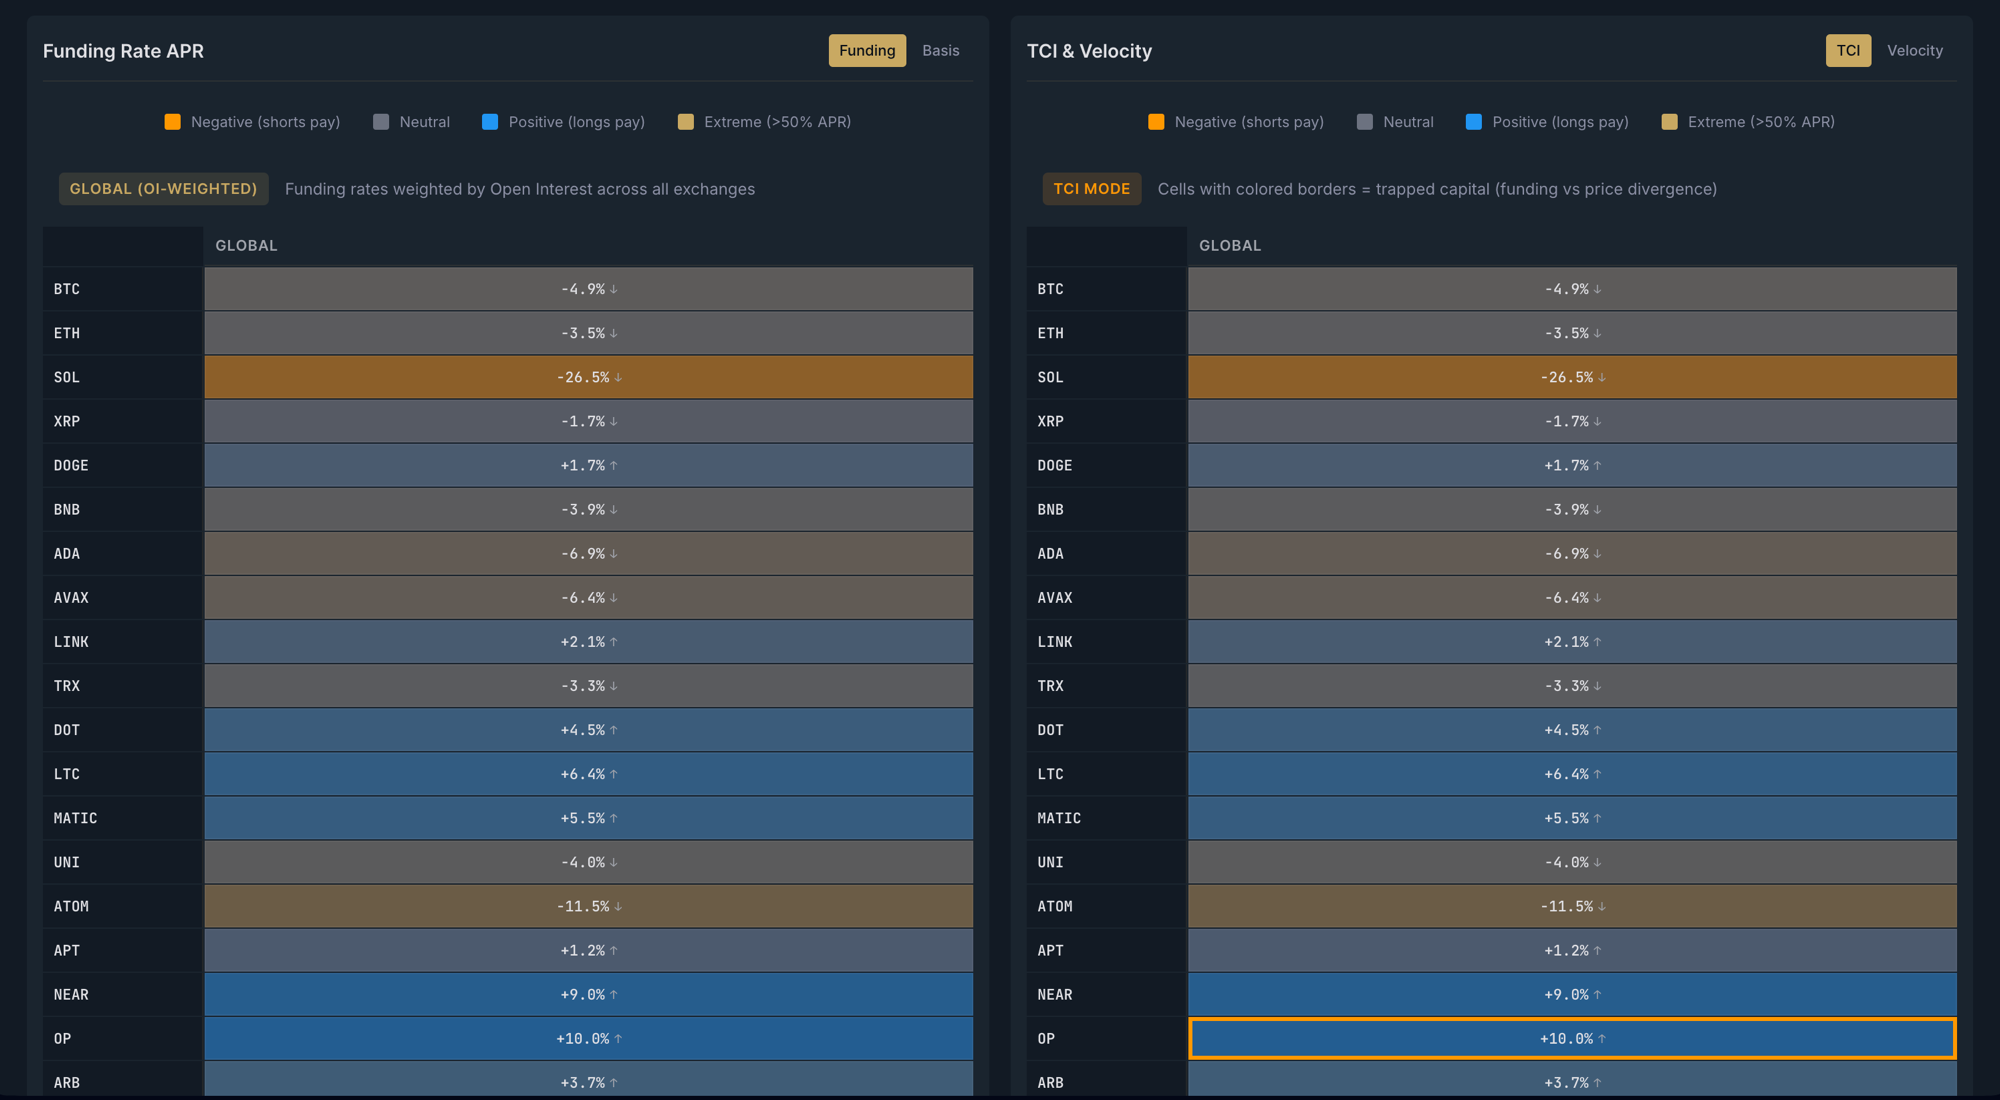
Your next step
Compare the funding scenario with current rates
A fixed rate is a scenario. Compare funding across exchanges before evaluating the cost of holding a perpetual position.
Sign in or create an account. Access depends on your plan.
Results depend on your inputs and the assumptions shown by this calculator. Reference links explain the model; they do not supply a live price feed. Fees, execution and changing market conditions can affect actual outcomes.
Methodology and assumptions
Manual scenario · no live funding feed
Manual assumptions, not live rates. Prices and position sizes stay constant. Funding is positive for a short receiving a positive rate; a long pays it.
Both legs must refer to the same underlying asset and USD-valued linear exposure. Inverse contracts are not modeled.
Use UTC. The next settlement must be after the start and within one interval. Include settlements at the end, exclude the start. Intervals remain fixed in each scenario.
Committed capital = both cash/collateral or margin amounts + reserve. It is not notional. Enter all capital actually tied up; the model does not derive margin requirements.
First settlement covering all assumed entry, exit and transfer costs plus borrowing accrued so far. Later payments can erase this break-even. No event is extrapolated past the chosen period.
Delta uses quantities of the same underlying asset. Equal USD notional at different prices is not necessarily neutral. Price, basis, liquidation, collateral and counterparty risks remain.
Fₙ = ΣFᵢ − C₁ − C₂ − C₃ − C₄ − C₅
Frequently asked questions
Is positive funding risk-free income?
Delta uses quantities of the same underlying asset. Equal USD notional at different prices is not necessarily neutral. Price, basis, liquidation, collateral and counterparty risks remain.
What is the return denominator?
Committed capital = both cash/collateral or margin amounts + reserve. It is not notional. Enter all capital actually tied up; the model does not derive margin requirements.
Practise with worked lessons
- Build the full ledger for a spot–perpetual basis trade
Calculate both legs, basis change, funding and fees of a spot–perpetual basis trade. Stress a widening basis and margin needs before calling the hedge low risk.
- Test a funding-settlement trade after all costs
Opening just before funding and closing just after looks easy. A 30 USDT receipt cannot cover 100 USDT of fees and slippage even before price moves.
- Funding minus borrow costs: account for rate resets and repayment
Calculate net carry from actual funding and a changing loan balance. Include hourly rate resets, partial repayment and interest after the trade closes.