Funding rates and basis trades: costs, crowding and carry · 1 / 5
Calculate funding payments over your actual holding window
Funding is a cash flow associated with holding a perpetual position through the venue's settlement rules. It is calculated from exposure, not simply from the collateral you deposited. A small-looking rate can matter when notional is large or a position crosses several settlements.
Athenum8 minUpdated:
Funding payment formula: notional × settled rate
For a simple linear perpetual, let N be the positive position notional at settlement and r the signed settled funding rate. The cash flow is −N × r for a long and +N × r for a short: positive cash flow means receipt. A positive rate therefore makes longs pay shorts; a negative rate reverses the payment. Check the applicable valuation price and timestamp. Inverse products use a different position-value convention and may settle in the underlying asset.
Funding intervals are not universally eight hours. They can vary by instrument and change under exchange rules. Use instrument metadata, settlement history and the current schedule. An indicated next rate may still change before settlement. The rate that actually settled belongs in the realised ledger; the earlier estimate belongs in the decision-time record.
Funding vs trading fees: leverage does not change the payment
Trading fees arise from fills. Funding arises from eligible position exposure at settlement. A short holding period can still cross a settlement, while a longer period entirely between settlements may have different treatment under the venue's rules. Do not automatically prorate an eight-hour rate by minutes held unless that product explicitly does so.
Changing leverage with quantity fixed does not multiply the funding payment again. A 1 BTC position has the same notional-based payment whether it was opened with more or less collateral. Leverage changes the payment's size relative to committed margin, which is a different comparison. Include funding alongside fees and price P&L when judging the whole trade.
Example: 1 BTC long across three funding settlements
A hypothetical 1 BTC linear long remains eligible through three settlements. The applicable notionals are 60,000, 62,000 and 61,000 USDT. Settled rates are +0.01%, +0.02% and −0.005%. The long pays 6, then 12.40, then receives 3.05 USDT.
Net funding paid is 6 + 12.40 − 3.05 = 15.35 USDT. Using only the first notional or multiplying the final rate by all three settlements would produce a different and incorrect ledger for this scenario. Trading fees and changes in the position's market value must be added separately to obtain total P&L.
| Settlement | Notional USDT | Rate | Long cash flow USDT |
|---|---|---|---|
| 1 | 60,000 | +0.01% | −6.00 |
| 2 | 62,000 | +0.02% | −12.40 |
| 3 | 61,000 | −0.005% | +3.05 |
| Total | Varies | Do not average blindly | −15.35 |
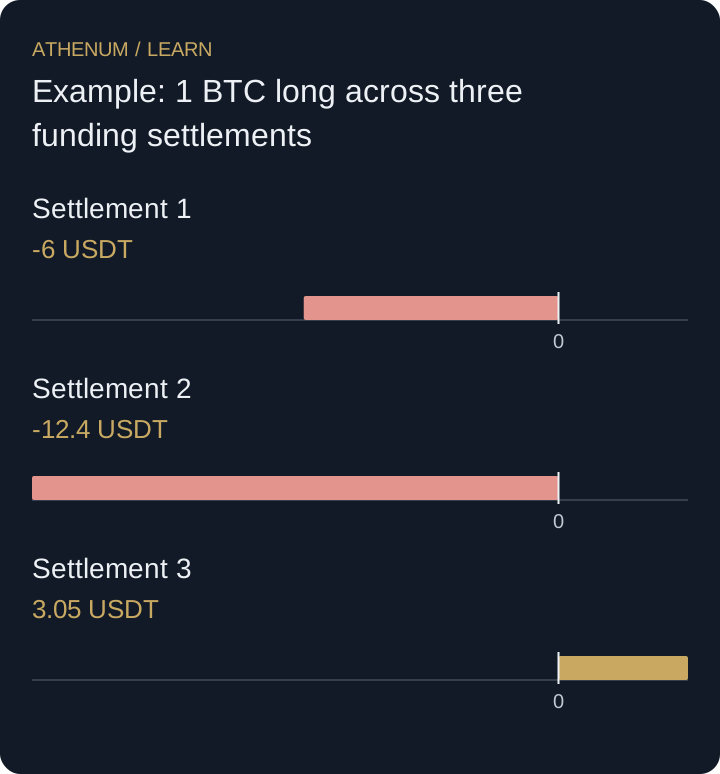 Open full-size diagram
- Settlement 1: -6 USDT
- Settlement 2: -12.4 USDT
- Settlement 3: 3.05 USDT
Mistake: treating the estimated funding rate as a completed payment
A funding estimate can change as the premium evolves or as an exchange applies its caps and interval rules. Closing or opening close to the settlement boundary also introduces timing uncertainty. Evaluate expected and adverse rate scenarios before entry, then reconcile the actual account ledger rather than assuming the initial screen value was received.
Before acting
- Verify the current instrument interval and settlement timestamp.
- Use the settled rate and the correct position-value convention.
- Keep payments and receipts signed consistently.
- Include every settlement actually crossed and changes in quantity.
- Add fees and price P&L separately; do not multiply by leverage again.
Check your understanding
A 20,000 USDT linear short is eligible at a settlement with a −0.03% rate. Does it pay or receive, and how much?
Show the explained answer
With negative funding, shorts pay longs under the stated convention. The short pays 20,000 × 0.0003 = 6 USDT. The calculation uses notional, not initial margin, and assumes the applicable position value is 20,000 at settlement.
Sources and further reading
Continue with Athenum
From the Athenum blog
How to Calculate Crypto Futures PnL: Entry, Exit, Funding, and Fees
Related lessons
- Partial exits: allocate fees and funding without double counting
Allocate entry fees, funding and exit charges across a partially closed position. Two exits reconcile to 5.99 USDT net without double counting any cost.
- Calculate trading expectancy after fees and slippage
Turn win rate and average wins and losses into net expectancy. Find the break-even win rate and see how fees and slippage can turn a 2R setup negative.