Position sizing and leverage: risk, stops and fees · 5 / 5
Build a trading journal that can reject a setup
A useful trading journal must be capable of disproving your favourite idea. Screenshots of successful entries cannot do that. Record the opportunities that qualify under fixed rules, the orders that could actually execute and the costs that turn gross outcomes into account results.
Athenum8 minUpdated:
What to record in a trading journal before the outcome
Define instrument, venue, session, timeframe, trigger, invalidation, order type, exit rule and maximum holding period. Record the information available at the decision timestamp. If a pivot requires future candles to confirm, its signal was not available at the pivot's historical location. Save the time the signal became usable, not just where a chart later draws it.
Each opportunity needs a status: taken, rejected by a stated filter, missed, unfilled or unavailable because the feed failed. Keep a reason for every exclusion. Otherwise discretionary deletion of difficult trades creates a sample that is easy to admire and impossible to reproduce.
Test the setup on an untouched later period
Use an earlier period to develop rules and a later, untouched period to evaluate them. A chronological split better reflects deployment than mixing neighbouring observations at random. If you change the rules after seeing the later results, that period becomes development data too. A new version needs a new forward evaluation window.
Track net R, average win and loss, total costs, maximum drawdown, time in market and concentration by asset and regime. No fixed number of trades guarantees validity. Repeated trades from the same event are not independent evidence. Paper execution is useful for checking decisions, but still needs realistic fills and cannot demonstrate live capacity.
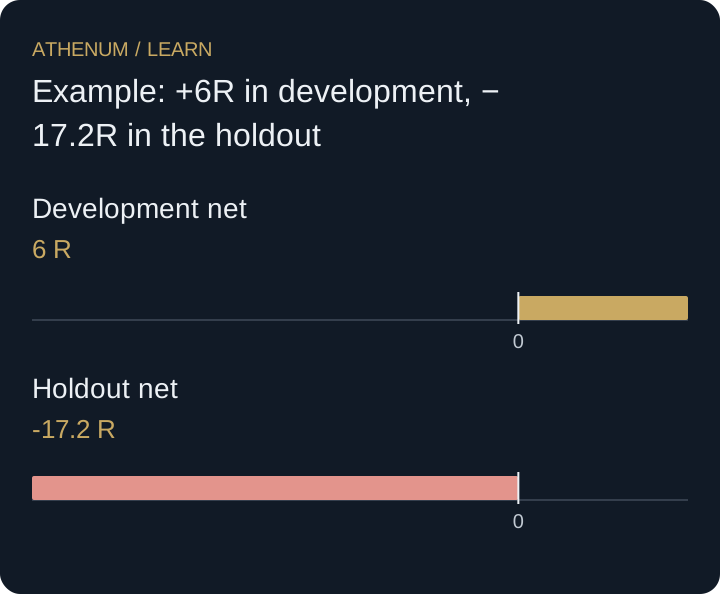
Example: +6R in development, −17.2R in the holdout
An illustrative development set has 120 opportunities: 60 wins averaging 1.4R and 60 losses averaging 1R. Gross result is 84 − 60 = 24R. Costs of 0.15R per trade remove 18R, leaving 6R or +0.05R per trade.
Freeze the rule and evaluate the next 40 opportunities. Twelve win 1.4R and 28 lose 1R. Gross result is 16.8 − 28 = −11.2R; after 6R of costs, net result is −17.2R. This does not identify the cause by itself. It tells you that the development result did not survive this evaluation, so review regime dependence, data quality and execution without quietly rewriting the original test.
| Measure | Development | Later holdout |
|---|---|---|
| Opportunities | 120 | 40 |
| Wins / losses | 60 / 60 | 12 / 28 |
| Gross result | +24R | −11.2R |
| Costs | 18R | 6R |
| Net result | +6R | −17.2R |
 Open full-size diagram
- Development net: 6 R
- Holdout net: -17.2 R
Why adding filters after a loss is overfitting
After the failure, you notice that excluding Tuesdays would improve results. That observation can justify a new hypothesis, but it is not an independent validation of the revised setup. Trying enough filters eventually finds one that explains noise. Log the revision and its rationale, retain the previous version and judge the new rule on data that did not select it.
Before acting
- Timestamp rules, screenshots and the information available at entry.
- Retain rejected, missed and unfilled opportunities with reasons.
- Record actual costs and the gross/net R convention.
- Freeze versions and reserve genuinely later evaluation data.
- Set a review or suspension condition before a losing sequence arrives.
Check your understanding
You inspect the holdout, add a funding filter and obtain a profitable result on that same period. Is the filtered strategy validated?
Show the explained answer
No. The holdout influenced the new rule, so it is now part of development. Preserve the result as exploratory, describe the filter precisely and test the frozen revision on a new chronological window. Check that the funding data used was available at each historical decision time.
Sources and further reading
Continue with Athenum
Related lessons
- Trading journal review: separate rule adherence from profit
Review trades against rules recorded before entry. Do not reward a profitable rule violation or call every compliant loss a mistake.
- Out-of-sample testing: freeze a holdout without leaking outcomes
Freeze the rule and evaluation protocol before testing. Audit boundary-crossing trades and preprocessing so future outcomes never leak into the holdout.