Position sizing and leverage: risk, stops and fees · 1 / 5
Calculate position size from your invalidation level
A position is too large when an ordinary failure of the idea creates an unacceptable loss. Start with the price that would invalidate the trade, then calculate quantity. Starting with a leverage setting leaves the most important question unanswered: how much money can this particular trade lose?
Athenum7 minUpdated:
Place the stop where the trade idea is invalidated
For a long position, invalidation might be acceptance below a previously reclaimed range. Describe that condition before entry. A stop placed an arbitrary percentage below entry may sit inside normal noise; moving it farther away after entry changes the original risk contract. A tighter stop permits more quantity mathematically, but it does not make the trading idea more robust.
Separate the analytical invalidation level from the execution instruction. A price condition can trigger an order, but the final fill depends on the order type and available liquidity. Use an adverse execution allowance when planning, and record the actual difference after exit.
Position size formula: risk budget ÷ loss per unit
Here quantity means base-asset units, not a count of contracts: convert contracts using their multiplier first. For a linear payoff, budget = quantity × (adverse price distance + fees + execution allowance + funding debit per unit) + fixed costs. Subtract fixed costs from the budget before dividing. If the budget is exhausted, no positive quantity fits. Use the inverse payoff for inverse contracts; do not reuse this linear equation.
The risk percentage is a planning input, not a universal recommendation. Account equity, other open positions and correlated exposures matter. Three small positions in highly correlated coins can act like one large trade. Check the combined scenario before treating each individual budget as available.
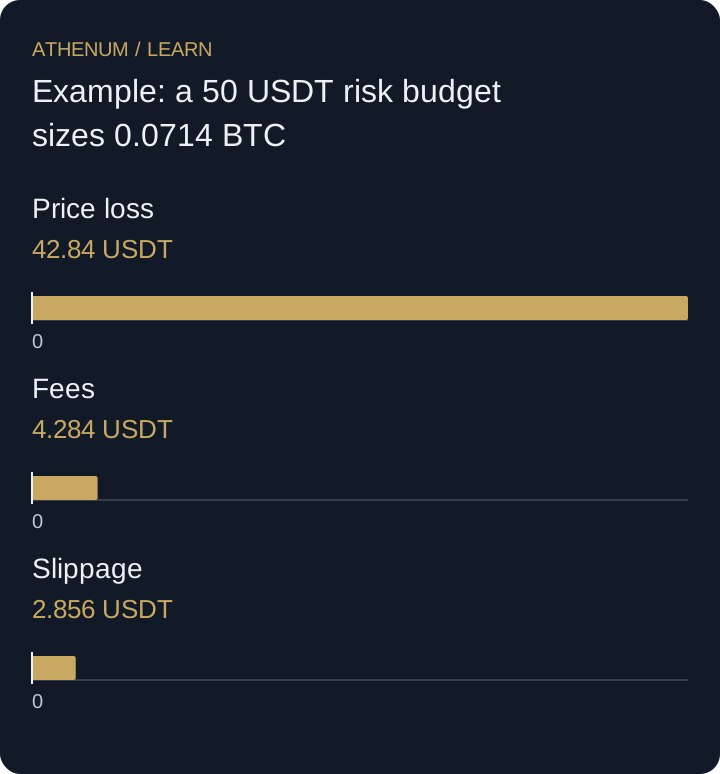
Example: a 50 USDT risk budget sizes 0.0714 BTC
Assume 10,000 USDT of equity and an illustrative 0.5% trade budget: 50 USDT. A BTC linear long enters at 60,000 with invalidation at 59,400. Reserve 60 USDT per BTC for round-trip fees and 40 for adverse execution. These are hypothetical allowances, not an exchange fee schedule.
The denominator is 600 + 60 + 40 = 700 USDT per BTC. Quantity is at most 50 ÷ 700 = 0.071428… BTC. With a 0.0001 BTC size step, round down to 0.0714 BTC. Its notional is 4,284 USDT and its planned loss is 49.98 USDT. A leverage change affects the margin required; it does not multiply this fixed quantity's price loss again.
| Component | Calculation | USDT |
|---|---|---|
| Price movement | 0.0714 × 600 | 42.84 |
| Fee allowance | 0.0714 × 60 | 4.284 |
| Execution allowance | 0.0714 × 40 | 2.856 |
| Total | 0.0714 × 700 | 49.98 |
 Open full-size diagram
- Price loss: 42.84 USDT
- Fees: 4.284 USDT
- Slippage: 2.856 USDT
When slippage pushes the loss past the budget
Suppose the exit slips another 300 USDT per BTC beyond the allowance. The position loses an additional 21.42 USDT, so the planned budget is exceeded. This does not make the sizing equation wrong: it reveals that its execution assumption failed. A stop is not a guaranteed maximum loss. Reduce quantity, improve the execution plan or skip the trade if plausible stress outcomes are unacceptable.
Before acting
- Write invalidation before choosing quantity.
- Include both entry and exit costs, expected funding and adverse execution.
- Round down to the instrument's permitted size step and check minimum order value.
- Check account-wide correlated risk and available margin.
Check your understanding
The same 50 USDT budget now has a 900 USDT price distance, 60 in fees and 40 in slippage per BTC. What quantity fits a 0.0001 BTC step?
Show the explained answer
50 ÷ (900 + 60 + 40) = 0.05 BTC. The wider invalidation distance reduces quantity. Keeping 0.0714 BTC would raise planned loss to 71.40 USDT; increasing leverage would not fix that.
Sources and further reading
Continue with Athenum
From the Athenum blog
Risk/Reward Ratio in Crypto: How to Size a Leveraged Trade Around Your Liquidation Price
Related lessons
- Round an executable quantity without increasing the risk budget
Check quantity steps, price ticks and minimum notional against a fixed risk budget. Learn when rounding leaves no order that fits the original risk.
- Portfolio heat: add correlated positions before sizing a new trade
Add planned stop losses across BTC, ETH and altcoin positions before a new trade, then stress a joint shock. Correlated trades do not have separate budgets.