Reconcile margin, collateral and account exposure · 5 / 5
Collateral haircuts: calculate tiered credit and liabilities
The last collateral band's factor is not necessarily the factor for the whole balance. And an asset haircut does not automatically reduce a debt owed by the account.
Athenum7 minUpdated:
Identify whether bands are marginal
Assume an invented eligible asset Y priced at 100 USD. The first 5 Y receive 90% credit, the next 5 receive 80%, and quantity above 10 through 15 receives 50%. These are explicitly marginal bands. Values above 15 require an additional rule; do not extrapolate this schedule.
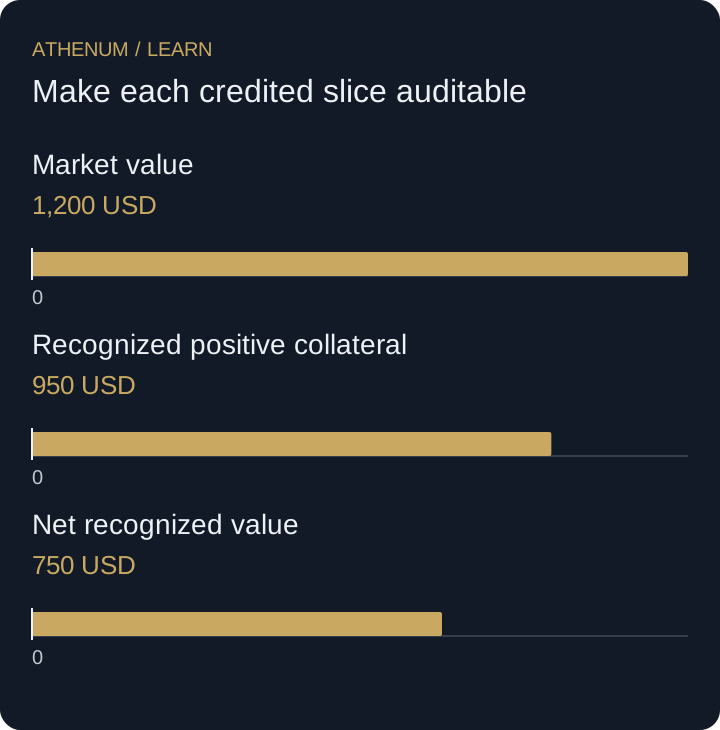
For 12 Y, calculate each slice separately: 5 × 100 × 0.90, then 5 × 100 × 0.80, then 2 × 100 × 0.50. The sum is 950 USD, although market value is 1,200. Eligibility is enabled; there are no positions, fees, orders or other assets in this initial example.
Subtract the liability under its own rule
Now add a separate liability of 200 USD, recognized in full under the exercise rules. Net recognized value is 950 − 200 = 750. Applying Y's last 50% factor to the liability would shrink the debt to 100 and falsely report net value of 850.
Market value, eligibility, collateral credit and withdrawal availability answer different questions. An asset can retain a market price while contributing nothing as collateral. Whether a venue permits disabling it, and when that affects margin or forces action, requires account-specific evidence rather than this abbreviated ledger.
Make each credited slice auditable
The first 5 Y contribute 450 USD, the next 5 contribute 400 and the remaining 2 contribute 100. Their total is 950. The table keeps nominal value and recognized value in different columns so that a reviewer can reconstruct the distinction.
Applying 50% to all 12 gives 600, which is a different rule from the one stated. Applying 90% throughout gives 1,080 and overstates credit. A whole-balance schedule could exist elsewhere; determine the actual rule before choosing a formula.
| Slice | Nominal USD | Credit factor | Recognized USD |
|---|---|---|---|
| First 5 Y | 500 | 0.90 | 450 |
| Next 5 Y | 500 | 0.80 | 400 |
| Remaining 2 Y | 200 | 0.50 | 100 |
 Open full-size diagram
- Market value: 1,200 USD
- Recognized positive collateral: 950 USD
- Net recognized value: 750 USD
Do not transfer one venue's recognition rules to another
Collateral factors can depend on asset, balance, account mode and effective date. A rule for borrowing capacity can also differ from a transfer-out rule. The Y schedule illustrates a calculation method only; it is not a live collateral table for any exchange.
Before acting
- Check whether the asset is eligible and enabled.
- Distinguish marginal bands from whole-balance rates.
- Value every slice under the stated price convention.
- Apply liability treatment separately.
- Do not relabel net recognized value as withdrawable cash.
Check your understanding
Increase Y from 12 to 13 with all other inputs fixed. What are total credit and net recognized value? Separately, what happens to collateral credit if the original 12 Y becomes entirely ineligible?
Show the explained answer
The extra unit adds 100 USD of market value but only 50 of credit. Total credit becomes 1,000 and net recognized value becomes 800 after the 200 liability. In the separate ineligibility scenario, the 12 Y still has assumed market value 1,200 but contributes zero collateral credit; the 200 liability remains. Actual venue actions are not specified by this model.