Portfolio risk: drawdown, sizing and daily limits · 2 / 5
Fixed fractional risk: model a losing streak before trading
Risking a fixed percentage of current equity reduces the next planned cash loss after a loss. Risking the same cash amount does not. Neither rule guarantees that real losses equal the plan: gaps, fees and liquidation can change the actual outcome.
Athenum7 minUpdated:
State what the fraction controls
In the idealized fixed-fraction model, each losing trade removes fraction f of the equity available immediately before that trade. After n consecutive losses, E_n = E_0 × (1 − f)^n. The fraction refers to planned account loss, not position notional or margin posted. A 1% margin allocation with high leverage is not a 1% loss limit.
The model assumes sequential, non-overlapping trades, exact loss realization and no deposits or withdrawals. Include expected costs inside the loss allowance if that is the convention. Concurrent positions need a combined budget; sizing each independently from the full equity can commit several times the intended risk.
Make the model executable
Translate the cash allowance into quantity using stop distance, contract payoff, cost allowance and valid quantity increments. Round down where rounding up would exceed the budget. At small account sizes a venue minimum may make the planned trade impossible; skipping it preserves the rule better than silently increasing risk.
A losing-streak calculation is a stress path, not its probability. A formula such as loss_probability^n applies only to a specified sequence under independent trials with a constant probability. It is not the probability of encountering at least one streak anywhere in a longer, dependent trading history.
Worked example: five losses with a 2% allowance
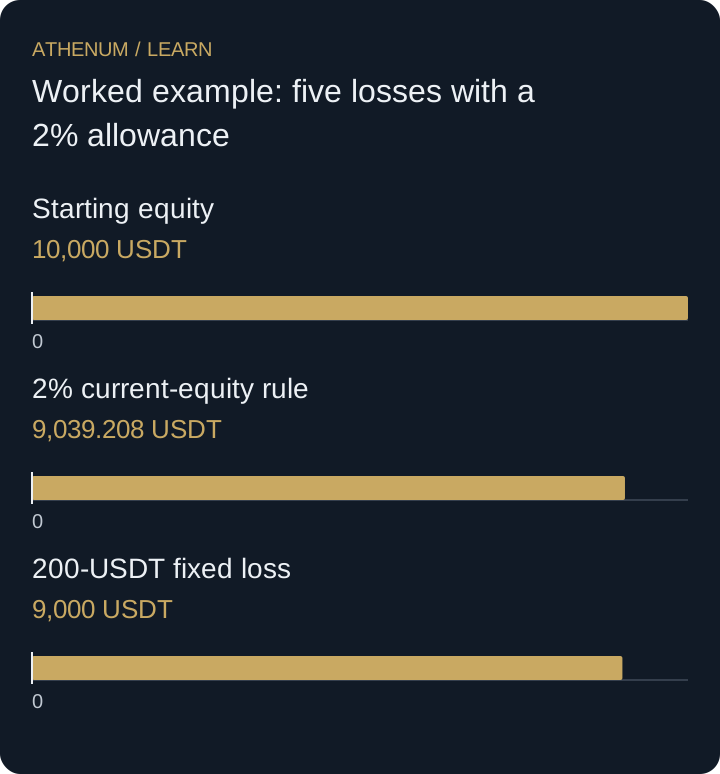
Start with a hypothetical 10,000-USDT account. Recalculating a 2% allowance yields equity of 9,800; 9,604; 9,411.92; 9,223.6816; and 9,039.207968. The fifth planned loss is 184.473632 USDT. The cumulative loss is approximately 9.608%, rather than exactly 10%.
With a constant 200-USDT loss, equity instead reaches 9,000. That fifth 200-USDT risk is 2.174% of the 9,200 equity before it. A fixed cash rule therefore increases its percentage exposure during a drawdown. This comparison assumes exact realized losses and illustrates mechanics, not a recommendation for a 2% risk setting.
| Loss number | Fractional equity (USDT) | Fixed-cash equity (USDT) |
|---|---|---|
| 1 | 9,800 | 9,800 |
| 2 | 9,604 | 9,600 |
| 3 | 9,411.92 | 9,400 |
| 4 | 9,223.6816 | 9,200 |
| 5 | 9,039.207968 | 9,000 |
 Open full-size diagram
- Starting equity: 10,000 USDT
- 2% current-equity rule: 9,039.208 USDT
- 200-USDT fixed loss: 9,000 USDT
The asymptote is not protection from ruin
The ideal formula never reaches zero for a fraction strictly between zero and one. Real trading has minimum order sizes, fees, execution gaps and margin thresholds. These can make an account unable to trade long before mathematical zero or produce a larger loss than modeled. Do not market the formula as proof that an account cannot fail.
Before acting
- Define the fraction as loss allowance, not margin.
- Recalculate from the declared equity measure before each sequential trade.
- Respect quantity increments and venue minimums.
- Stress gaps and overlapping losses separately from exact-stop arithmetic.
Check your understanding
From 5,000 USDT, three sequential trades each lose exactly 1% of current equity. What remains, and how does that compare with three fixed 50-USDT losses?
Show the explained answer
Fixed fractional equity is 5,000 × 0.99³ = 4,851.495 USDT, a 2.9701% loss. Three fixed 50-USDT losses leave 4,850, a 3% loss. The small difference grows with longer streaks or larger fractions, but neither number accounts for loss overruns.