Funding rates and basis trades: costs, crowding and carry · 4 / 5
Build the full ledger for a spot–perpetual basis trade
Buying spot and shorting the same quantity of a linear perpetual reduces directional price exposure under specific assumptions. It does not eliminate basis, funding, execution, collateral or venue risk. The two-leg ledger shows where the remaining profit and loss actually come from.
Athenum9 minUpdated:
Basis trade P&L: initial basis minus final basis
Assume the same underlying, matched base quantity, linear payoff and compatible quote currency. Let S be spot price and F the perpetual price. Basis is F − S. For one unit of long spot and short perpetual, price P&L over the holding period is (S1 − S0) + (F0 − F1), which equals initial basis minus final basis.
This relation does not cover every contract automatically. Inverse payoffs, quantity changes, mismatched assets and currency movements can leave additional exposure. A perpetual has no fixed expiry forcing convergence on a known date. The basis can widen and funding can reverse while both legs remain open.
Liquidation and failed-leg risk in a hedged basis trade
If spot and the perpetual rise together, the spot leg gains while the short derivative loses. When the positions sit in separate accounts or venues, the spot gain may not be available as derivative collateral. The short can face liquidation before you transfer funds, especially during withdrawal delays or stressed markets.
Entry and exit are also two executions. One leg may fill while the other does not, creating temporary directional exposure. Include four sets of trading costs, adverse fills, transfer or borrowing costs where applicable and the actual funding sequence. Use a contingency for failed hedges rather than assuming simultaneous perfect fills.
Example: basis narrows from 300 to 50 on 1 BTC
All four quoted prices are hypothetical USDT-per-BTC reference prices before execution costs; quantities stay at 1 BTC on each leg. The 100 USDT budget includes all assumed fees and adverse execution, with no additional borrowing or transfer charge in this example. If using actual fill prices instead, include only costs not already embedded in those fills.
Buy 1 BTC spot at 60,000 and short 1 BTC of a linear perpetual at 60,300. Initial basis is 300. Later, sell spot at 61,000 and buy back the perpetual at 61,050. Spot gains 1,000; the short loses 750. Combined price P&L is 250, equal to basis narrowing from 300 to 50.
Assume the short received 60 USDT of funding and all trading/execution costs totalled 100. Net result is 250 + 60 − 100 = 210 USDT. In an adverse alternative where final basis widens to 900, combined price P&L is 300 − 900 = −600 before funding and costs. The hedge removes neither that spread risk nor the need for collateral.
| Component | Calculation | USDT |
|---|---|---|
| Spot price P&L | 61,000 − 60,000 | +1,000 |
| Perpetual price P&L | 60,300 − 61,050 | −750 |
| Funding received | Actual assumed total | +60 |
| Trading and execution costs | Both legs, entry and exit | −100 |
| Net result | 1,000 − 750 + 60 − 100 | +210 |
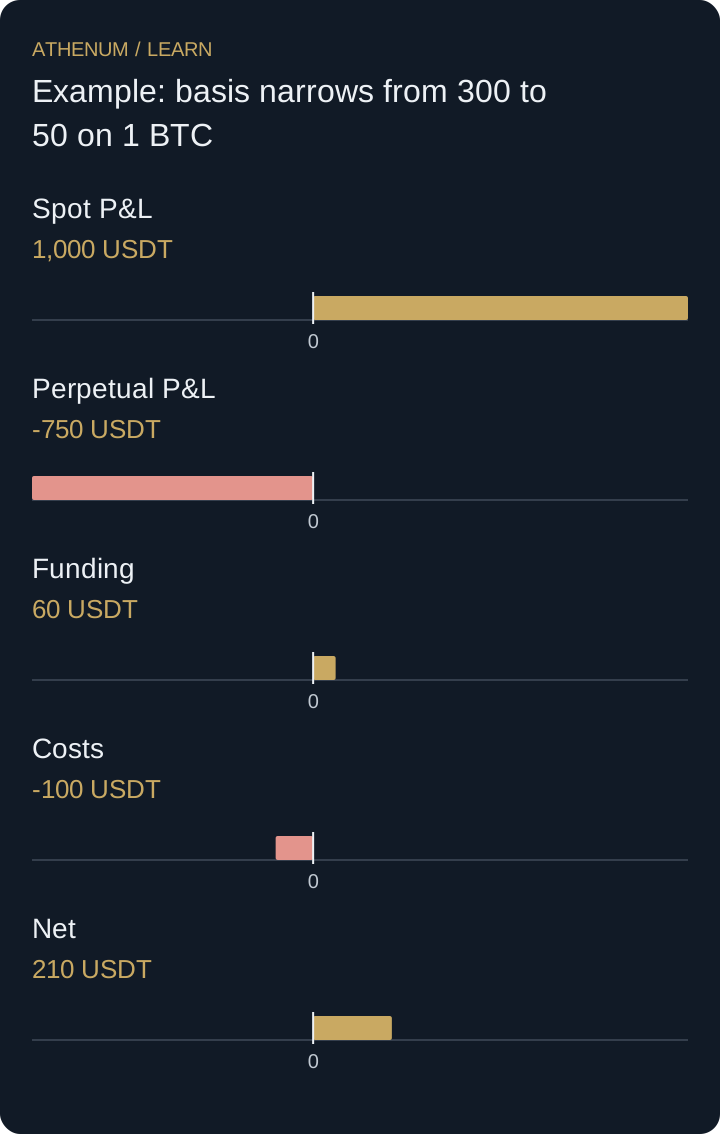 Open full-size diagram
- Spot P&L: 1,000 USDT
- Perpetual P&L: -750 USDT
- Funding: 60 USDT
- Costs: -100 USDT
- Net: 210 USDT
Mistake: annualising a few good funding settlements as yield
A few profitable settlements do not demonstrate a stable yield. Basis can move before funding compensates for it, and emergency hedge closure can crystallise a loss. Report capital committed across both legs, maximum margin usage and worst interim basis move alongside final return. A smooth funding ledger alone is an incomplete performance record.
Before acting
- Match underlying, quantity, payoff and quote-currency assumptions.
- Calculate initial and exit basis explicitly.
- Include signed funding and all entry/exit costs on both legs.
- Stress basis widening and derivative collateral needs separately.
- Define failed-leg, transfer-delay and venue-outage contingencies.
Check your understanding
Initial basis is 300, final basis is 450, funding received is 80 and total costs are 90, for one matched unit. What is net P&L?
Show the explained answer
Price P&L is 300 − 450 = −150. Adding funding and costs gives −150 + 80 − 90 = −160. Receiving funding does not ensure that the combined position is profitable.
Sources and further reading
Continue with Athenum
From the Athenum blog
The Cash and Carry Trade in Crypto: Capturing Basis With Spot and Futures
Related lessons
- Funding minus borrow costs: account for rate resets and repayment
Calculate net carry from actual funding and a changing loan balance. Include hourly rate resets, partial repayment and interest after the trade closes.
- Cross margin risk: stress several positions together
Calculate joint position losses, maintenance margin and remaining equity in one cross-margin stress. Never let two positions spend the same shared collateral.