Trade management: partial exits, MFE/MAE and time stops
Calculate partial-exit R, cost-adjusted break-even, observed MFE and MAE, add-on risk and time stops using complete hypothetical trading ledgers.
What you will practise
Reconcile what was actually filled, what remains exposed and which exit rule applies, without substituting a chart target or hindsight for a position ledger.
Before you start
- Calculate linear position P&L and fees on execution notional.
- Distinguish a stop trigger, an order acknowledgement and a confirmed fill.
Course outline
- 1
Calculate realized R after partial profit taking
A 2R exit on a quarter of the position still left the whole trade at 0.625R gross. Weight each exit by its share, deduct fees and keep the original risk.
8 minIn short: Realized R = gross P&L across all exits ÷ original R, where 1R = initial quantity × entry-to-stop distance. Weight each exit's R multiple by its share of initial quantity: 0.25 × 1 + 0.25 × 2 + 0.50 × (−0.25) = 0.625R gross, not 2R, and 0.5996875R after fees.
- 2
Calculate break-even after a partial exit
Separate an entry-price stop, the remaining position's break-even and whole-trade break-even. Include earlier partial profits and every fee paid.
9 minIn short: After a partial exit, three break-even prices differ: the entry-price stop, the residual units' break-even and the whole-trade break-even, which includes realized partial profit and all fees. In the example, entry is 100, whole-trade break-even 98.4337671 and residual break-even 100.3003003.
- 3
Measure MFE and MAE without inventing realized profit
Maximum favorable excursion is not profit: an observed 20.40 USDT excursion ended as 3.598 USDT net. Measure MFE and MAE, then reconcile the actual exit.
8 minIn short: MFE and MAE are the largest unrealized gain and loss within a declared observation series: V_t = Q × (P_t − E), MFE = max(0, max V_t), MAE = max(0, −min V_t). They are not profit: a sampled MFE of 20.40 USDT ended as 3.598 USDT realized net.
- 4
Recalculate average entry and risk before adding to a position
Size an addition from the combined position's stop: a 12 USDT budget permits 1.8 extra units, not two. Recalculate the average entry and don't spend risk twice.
9 minIn short: Size an addition from the whole position's risk: subtract the existing units' loss at the common stop from the budget, then divide by each added unit's loss plus fees, (12 − 4.398) ÷ 4.101, rounded down to 1.8 units. Average entry = (Q_old × E_old + Q_add × E_add) ÷ (Q_old + Q_add).
- 5
Define a time stop and signal expiry before entering
Separate signal expiry, maximum holding time and order time in force. Reconcile the actual timed exit and execution delay under a rule fixed before entry.
8 minIn short: A time stop exits at the earlier of the signal expiry and the maximum holding time from the first fill, both fixed before entry. With expiry at 09:20 and 15 minutes from a 09:04 fill, the exit deadline is 09:19. Cancelling the entry order does not close the position.
Calculators used in this course
Related courses
- Position sizing and leverage: risk, stops and feesSize a position from invalidation, distinguish leverage from exposure and test whether a setup survives real trading costs.
- Trading journal: costs, decisions and honest performanceAllocate partial-exit costs, review rule adherence, preserve thesis revisions and separate external cash flows from trading returns.
- Portfolio risk: drawdown, sizing and daily limitsReconcile drawdown recovery, losing streaks, correlated exposure, lagged volatility sizing and daily risk budgets with original worked examples.
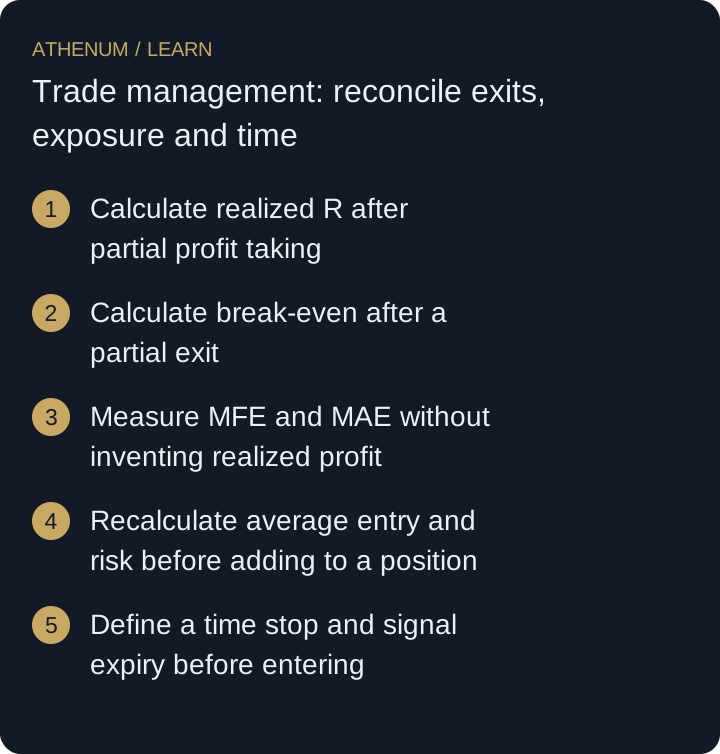 Open full-size diagram
- Calculate realized R after partial profit taking
- Calculate break-even after a partial exit
- Measure MFE and MAE without inventing realized profit
- Recalculate average entry and risk before adding to a position
- Define a time stop and signal expiry before entering
Educational material. Examples do not establish a profitable strategy. Trading costs, gaps and liquidation can produce losses beyond a planned stop.