Reconcile margin, collateral and account exposure · 1 / 5
Inverse futures P&L: calculate profit and collateral value
A BTC-settled position and the BTC already held as collateral create two distinct contributions to account value. A correct contract result is not yet a complete account reconciliation.
Athenum8 minUpdated:
Name the settlement and reporting units
For this hypothetical inverse long, let D be the fixed USD face amount, including the contract multiplier, E the entry price and P the comparison price in USD/BTC. Coin P&L is D × (1/E − 1/P). The reciprocal-price difference has units BTC/USD; multiplying by D therefore produces BTC, not USD. Reversing the contract direction reverses this result.
Translate coin P&L at P when reporting its value at the comparison point. Keep full precision until presentation. A venue's displayed unrealized P&L, margin valuation and eventual execution can use different price inputs; record which one you are using rather than calling every observation the current price.
Reconcile the starting collateral separately
If starting collateral is C BTC, theoretical equity at the comparison point is C + coin P&L. Its USD value is that total multiplied by P. The change from starting USD equity splits into contract P&L valued at P plus C × (P − E), the revaluation of the original collateral.
The exercise excludes fees, funding, deposits, withdrawals, borrowing, other positions and liquidation before the comparison point. It describes hypothetical endpoint values, not a guarantee that a venue would keep the account open along the intervening path. Recognized collateral and withdrawable funds may also differ from this equity measure.
One contract, two sources of USD change
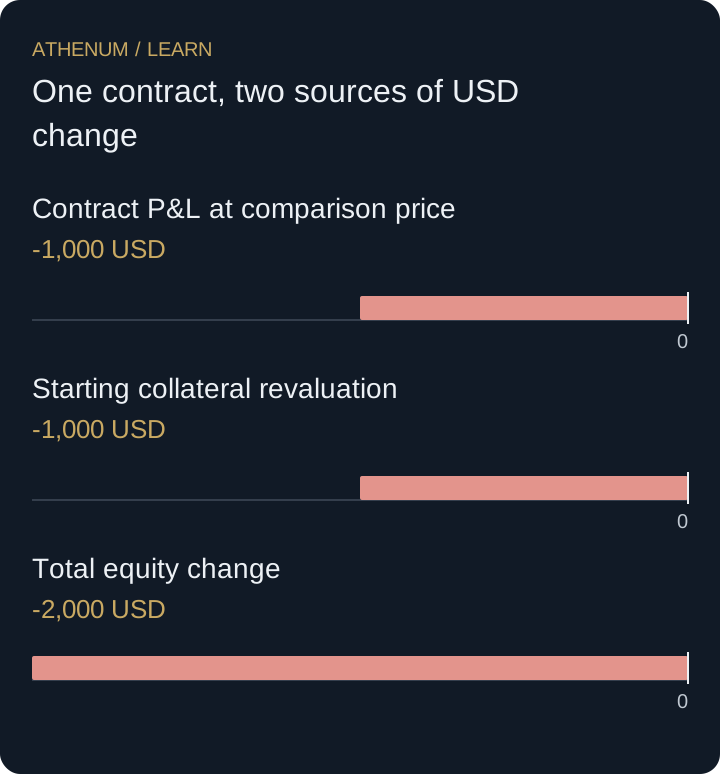
Assume D = 6,000 USD, E = 60,000 USD/BTC and C = 0.10 BTC. Starting equity is 6,000 USD. At P = 50,000, contract P&L is −0.02 BTC, worth −1,000 USD at that same price. The original collateral also loses 1,000 USD of value.
Equity is therefore 0.08 BTC, worth 4,000 USD: the account change is −2,000, not −1,000. At 70,000 the two USD contributions are each +1,000. Equal USD price moves here produce unequal coin P&L amounts; the reporting convention matters.
| Price USD/BTC | Contract P&L BTC | Equity BTC | Equity USD | USD equity change |
|---|---|---|---|---|
| 50,000 | −0.0200000000 | 0.0800000000 | 4,000 | −2,000 |
| 60,000 | 0 | 0.1000000000 | 6,000 | 0 |
| 70,000 | +0.0142857143 | 0.1142857143 | 8,000 | +2,000 |
 Open full-size diagram
- Contract P&L at comparison price: -1,000 USD
- Starting collateral revaluation: -1,000 USD
- Total equity change: -2,000 USD
Do not treat USD face amount as BTC quantity
6,000 × (50,000 − 60,000) is not this contract's payoff: it treats the USD face amount like a base-asset quantity. Adding −0.02 BTC directly to −1,000 USD is another unit error. Both can survive a spreadsheet review if column headings omit currencies.
Before acting
- Confirm contract multiplier and settlement asset.
- Name the comparison price and its role.
- Compute coin P&L before converting to USD.
- Separate original collateral revaluation from contract P&L.
- Keep costs and liquidation-path assumptions visible.
Check your understanding
Reverse only the contract to a short. With the same face amount and collateral, what is USD equity at 50,000 and 70,000? Is the result a risk-free live trade?
Show the explained answer
At 50,000, the short gains 0.02 BTC: 0.12 BTC equals 6,000 USD. At 70,000, it loses approximately 0.0142857143 BTC: the remaining approximately 0.0857142857 BTC also equals 6,000 USD. This cost-free endpoint identity is not a risk-free trading claim. Funding, fees, basis, collateral rules, liquidation and operational constraints remain outside it.