Portfolio risk: drawdown, sizing and daily limits · 5 / 5
Daily loss limit: reserve open risk before taking another trade
A daily loss limit is incomplete if it ignores positions that are still open. Before another entry, reconcile the realized loss already spent, the modeled loss still committed and the reserve for execution. A threshold controls decisions; it cannot guarantee the eventual fill price.
Athenum7 minUpdated:
How to measure a daily loss: marked equity and reset time
Net daily P&L, the sum of losing trades and a drawdown from an intraday peak are different rules. Here the allowance is fixed from start-of-day equity, and losses are measured using current marked equity. Include realized and unrealized daily P&L once each; separate deposits and withdrawals. For an overnight position, the daily change starts at its start-of-day mark, not its original entry.
Define the day boundary and timezone, especially in 24-hour markets. A clock reset does not flatten positions or erase their risk. Also decide whether realized profits increase the allowance. A conservative fixed-loss policy may decline to recycle profits; a net-P&L policy may permit it. Neither convention should change opportunistically after a losing trade.
Remaining daily risk formula and what the limit triggers
Remaining allowance = daily limit − marked daily loss − additional modeled loss from current marks − separate execution reserve. Without external cash flows, marked daily loss equals start-of-day equity minus current marked equity. If that equity already includes open P&L, do not subtract it again. A calculation using only realized loss omits existing unrealized loss; future stop risk measured from current prices does not recover that missing amount.
Specify what reaching the threshold does: reject new entries, cancel unfilled entry orders, or initiate reductions according to the plan. Cancelling an entry order does not close a position. A local alert is also not the same as an exchange-enforced control; loss can continue during latency, gaps or service outages.
Example: a 300 USDT daily limit leaves 60 USDT for new trades
A hypothetical account starts at 10,000 USDT with a 300-USDT daily allowance. It has booked 120 of net realized losses, and two positions have no current unrealized P&L but modeled additional losses of 60 and 40. A separate 20-USDT execution reserve is not included in those position estimates. Remaining admission capacity is 300 − 120 − 60 − 40 − 20 = 60.
A new trade requesting 90 USDT of total modeled loss exceeds the remaining budget by 30. Cutting the quantity to fit must use actual contract increments and preserve its strategy invalidation; moving the stop arbitrarily closer merely to make the arithmetic fit changes the trade. If no valid order fits, the rule rejects it.
Counterexample: keep the 120 realized loss but add 30 of unrealized loss. Current equity is now 9,850, and the remaining stop risks measured from these new marks are still 60 and 40. Capacity is 300 − 120 − 30 − 60 − 40 − 20 = 30. Equivalently subtract the 150 marked daily loss once. The original 60 allowance would overstate capacity by 30.
| Budget item | USDT |
|---|---|
| Daily allowance | 300 |
| Realized loss spent | −120 |
| Open risk A | −60 |
| Open risk B | −40 |
| Additional reserve | −20 |
| Remaining admission capacity | 60 |
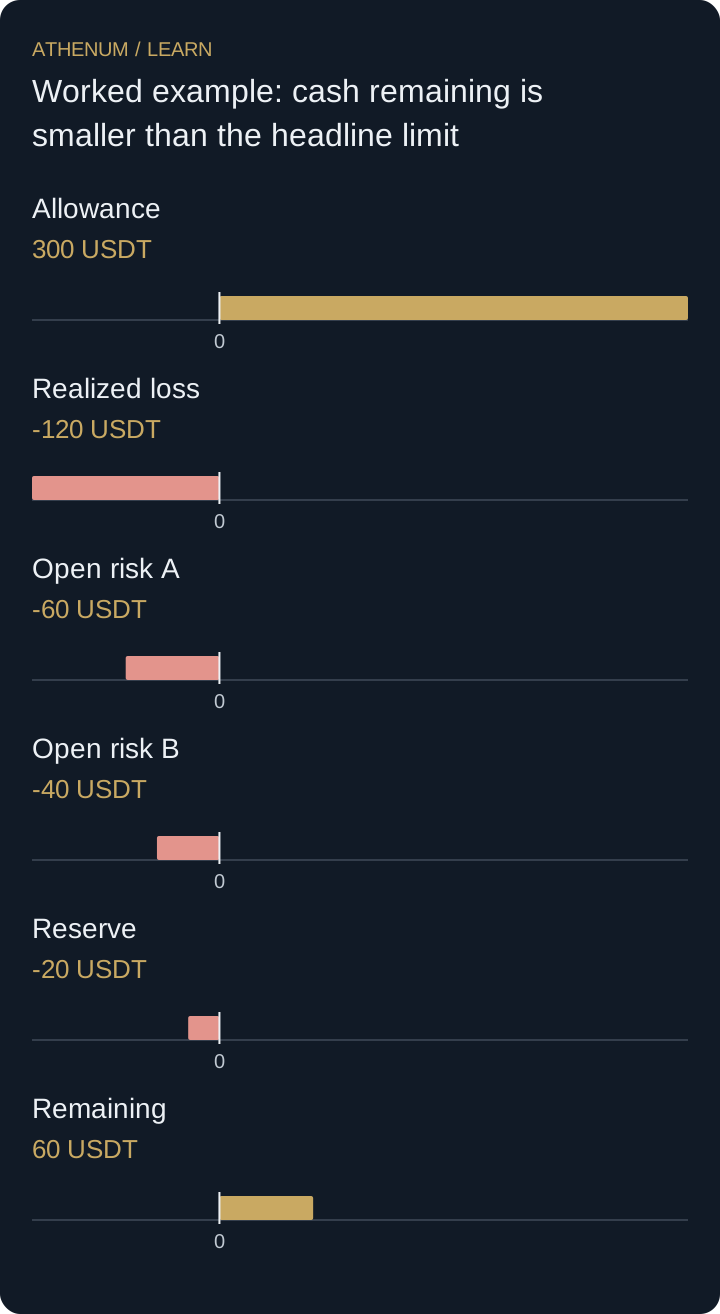 Open full-size diagram
- Allowance: 300 USDT
- Realized loss: -120 USDT
- Open risk A: -60 USDT
- Open risk B: -40 USDT
- Reserve: -20 USDT
- Remaining: 60 USDT
Mistake: resetting the daily limit while positions stay open
If yesterday’s positions remain open after the reset, they still need a place in today’s risk accounting. Ignoring them while assigning the full fresh allowance to new trades compounds exposure. Likewise, a threshold-triggered market exit may fill after the loss has passed the threshold. Record both the trigger breach and final executed loss.
Before acting
- Define the day, timezone and whether profits replenish capacity.
- Reconcile realized and unrealized P&L under one baseline.
- Reserve additional open-position loss and avoid double-counting costs.
- Specify threshold actions and verify actual cancellation or fill states.
Check your understanding
Assume no current unrealized daily P&L. The daily allowance is 250 USDT. Realized losses are 80, additional open risk is 95 and the separate reserve is 15. What remains? What changes if an existing stop then loses 25 more than modeled?
Show the explained answer
Capacity is 250 − 80 − 95 − 15 = 60 USDT. If the 25-USDT overrun is incremental to the modeled amounts and not already absorbed by the reserve, capacity falls to 35. Reconcile the closed position out of open risk and its realized loss into the ledger; do not subtract its full loss twice.
Sources and further reading
Continue with Athenum
From the Athenum blog
The $19 Billion Lesson: A Complete Guide to Risk Management for Crypto Derivatives Trading
Related lessons
- Recalculate average entry and risk before adding to a position
Size an addition from the combined position's stop: a 12 USDT budget permits 1.8 extra units, not two. Recalculate the average entry and don't spend risk twice.
- Choose between stop-market and stop-limit orders
A stop's trigger is not its fill. Compare gaps, partial fills, reduce-only and exchange protection rules before relying on a stop-market or stop-limit exit.