Athenum Analytics
Athenum Analytics es nuestro equipo editorial de tres personas dedicado a derivados cripto, datos de mercado y contexto macroeconómico.
Responsabilidad editorial y metodología
Quién prepara los artículos
Nuestro equipo interno de tres personas realiza la investigación, la elaboración y la verificación de datos. Los artículos se comprueban cuidadosamente antes de publicarse. Publicamos bajo el nombre de la organización Athenum Analytics; no presentamos aquí nombres ni credenciales profesionales individuales.
Fuentes y comprobación
Utilizamos nuestras propias API de mercado y contrastamos los datos con fuentes externas fiables, como FRED para series macroeconómicas. Importan la fuente, la fecha, la unidad y la cobertura: una instantánea de un exchange, un pago de financiación liquidado y un cálculo de modelo son pruebas diferentes.
Ejemplos verificables
Las páginas públicas de BTC y ETH documentan contratos, conversiones, fechas y datos ausentes. El estudio de bases de rentabilidad de Bitcoin incluye código, consultas de origen y descargas agregadas para comprobar el resultado. Las capturas históricas que no pudieron reproducirse se señalan expresamente.
Automatización y ayuda de IA
La actualización del 24 de septiembre de 2026 se preparó con ayuda de IA para borradores, traducciones y código. Los cálculos automáticos y las comprobaciones con fuentes reales apoyan el trabajo; por sí solos no acreditan una revisión humana experta e independiente. Las páginas de investigación explican qué se recalculó y los límites de la verificación.
Correcciones y cambios
Envía la URL del artículo, la afirmación cuestionada y la evidencia a nuestra dirección de correcciones. Las revisiones de septiembre documentan los cambios sustanciales en los artículos afectados, incluidas las afirmaciones históricas sobre financiación y correlación.
Información del perfil confirmada y actualizada:
Cost of Holding a Bitcoin Perp: Funding Passes the Round Trip Fee at the 18th Settlement
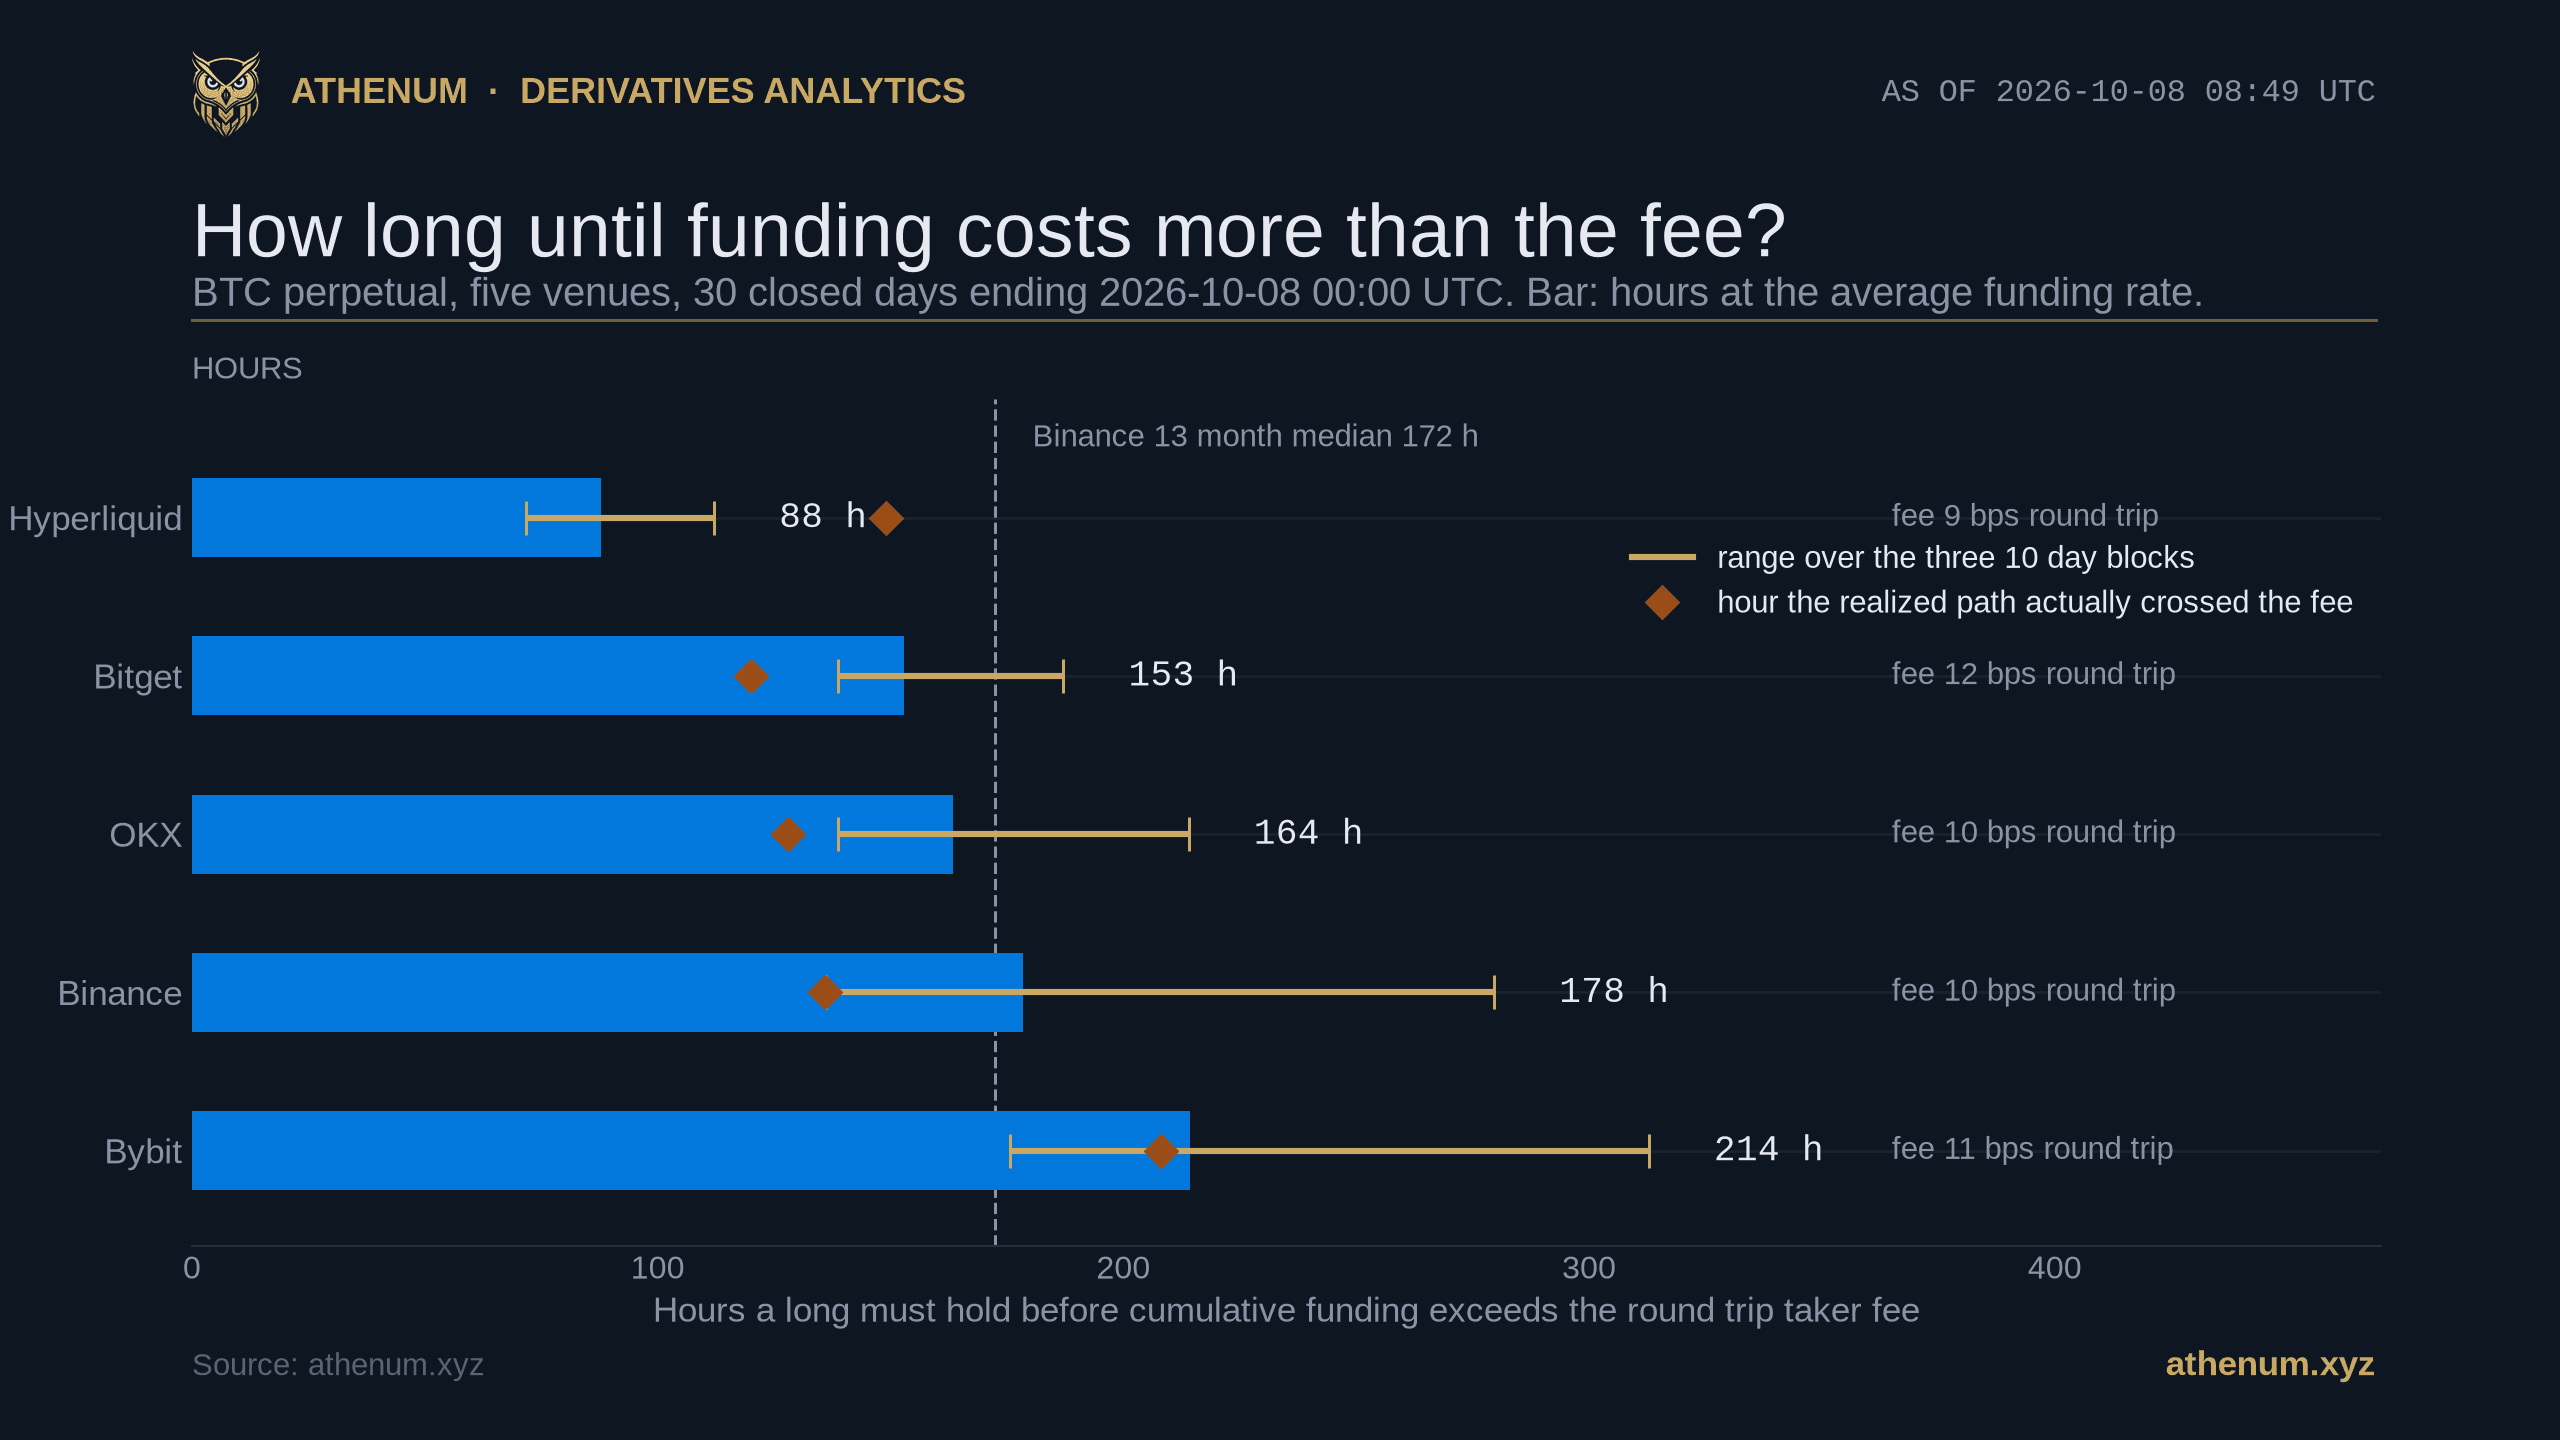
The cost of holding a bitcoin perp is usually compared venue by venue on the taker fee, and that is the smaller of the two numbers as soon as the position lives longer than a few days. Over the 30 closed days to 2026-10-07 a Binance long paid 40.33 basis points of funding against a 10 basis point round trip, so the funding bill passed the fee at the 18th of 90 settlements.
 Athenum Analytics
Tick Size vs Taker Fee: On 24 Perps Half a Tick Costs More Than the Fee
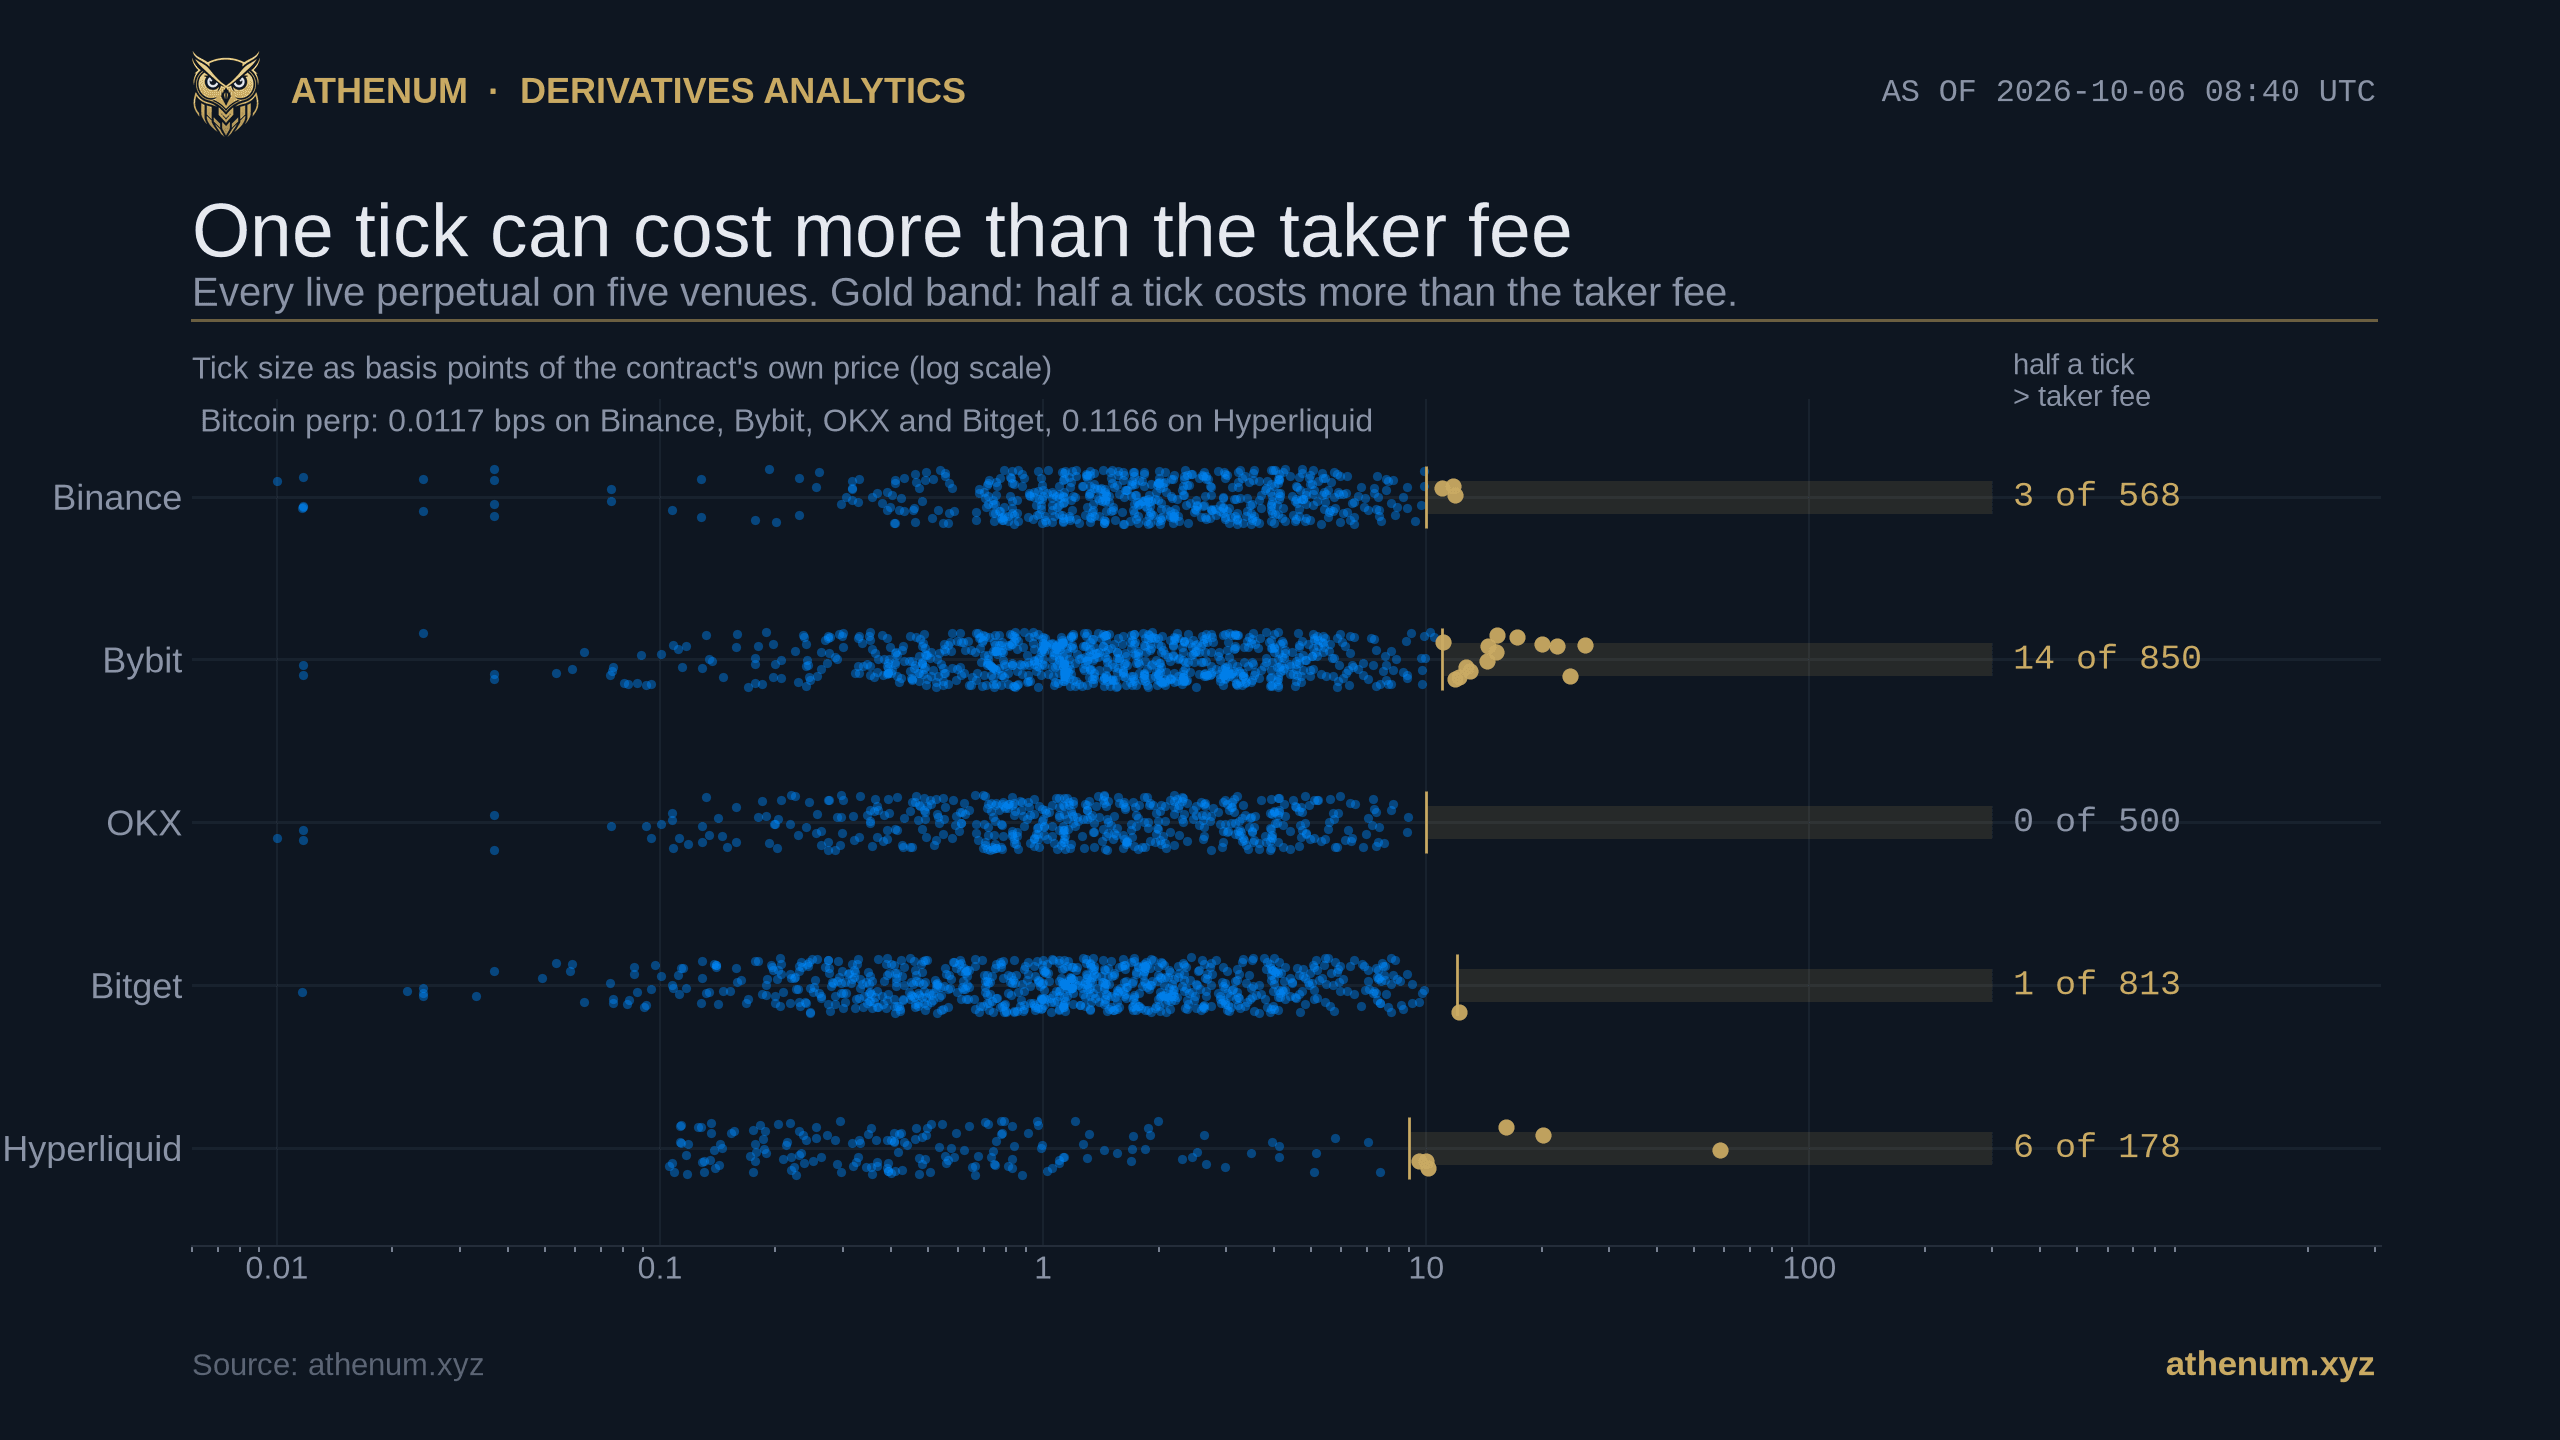
On a Bitcoin perpetual the taker fee dwarfs the price grid, and that is the comparison almost everyone generalizes from. Read across every live perpetual on five venues at 08:40 UTC on 2026-10-06, 2,909 contracts in all, it inverts on the long tail. The tick is a fixed number of decimal places.
Athenum Analytics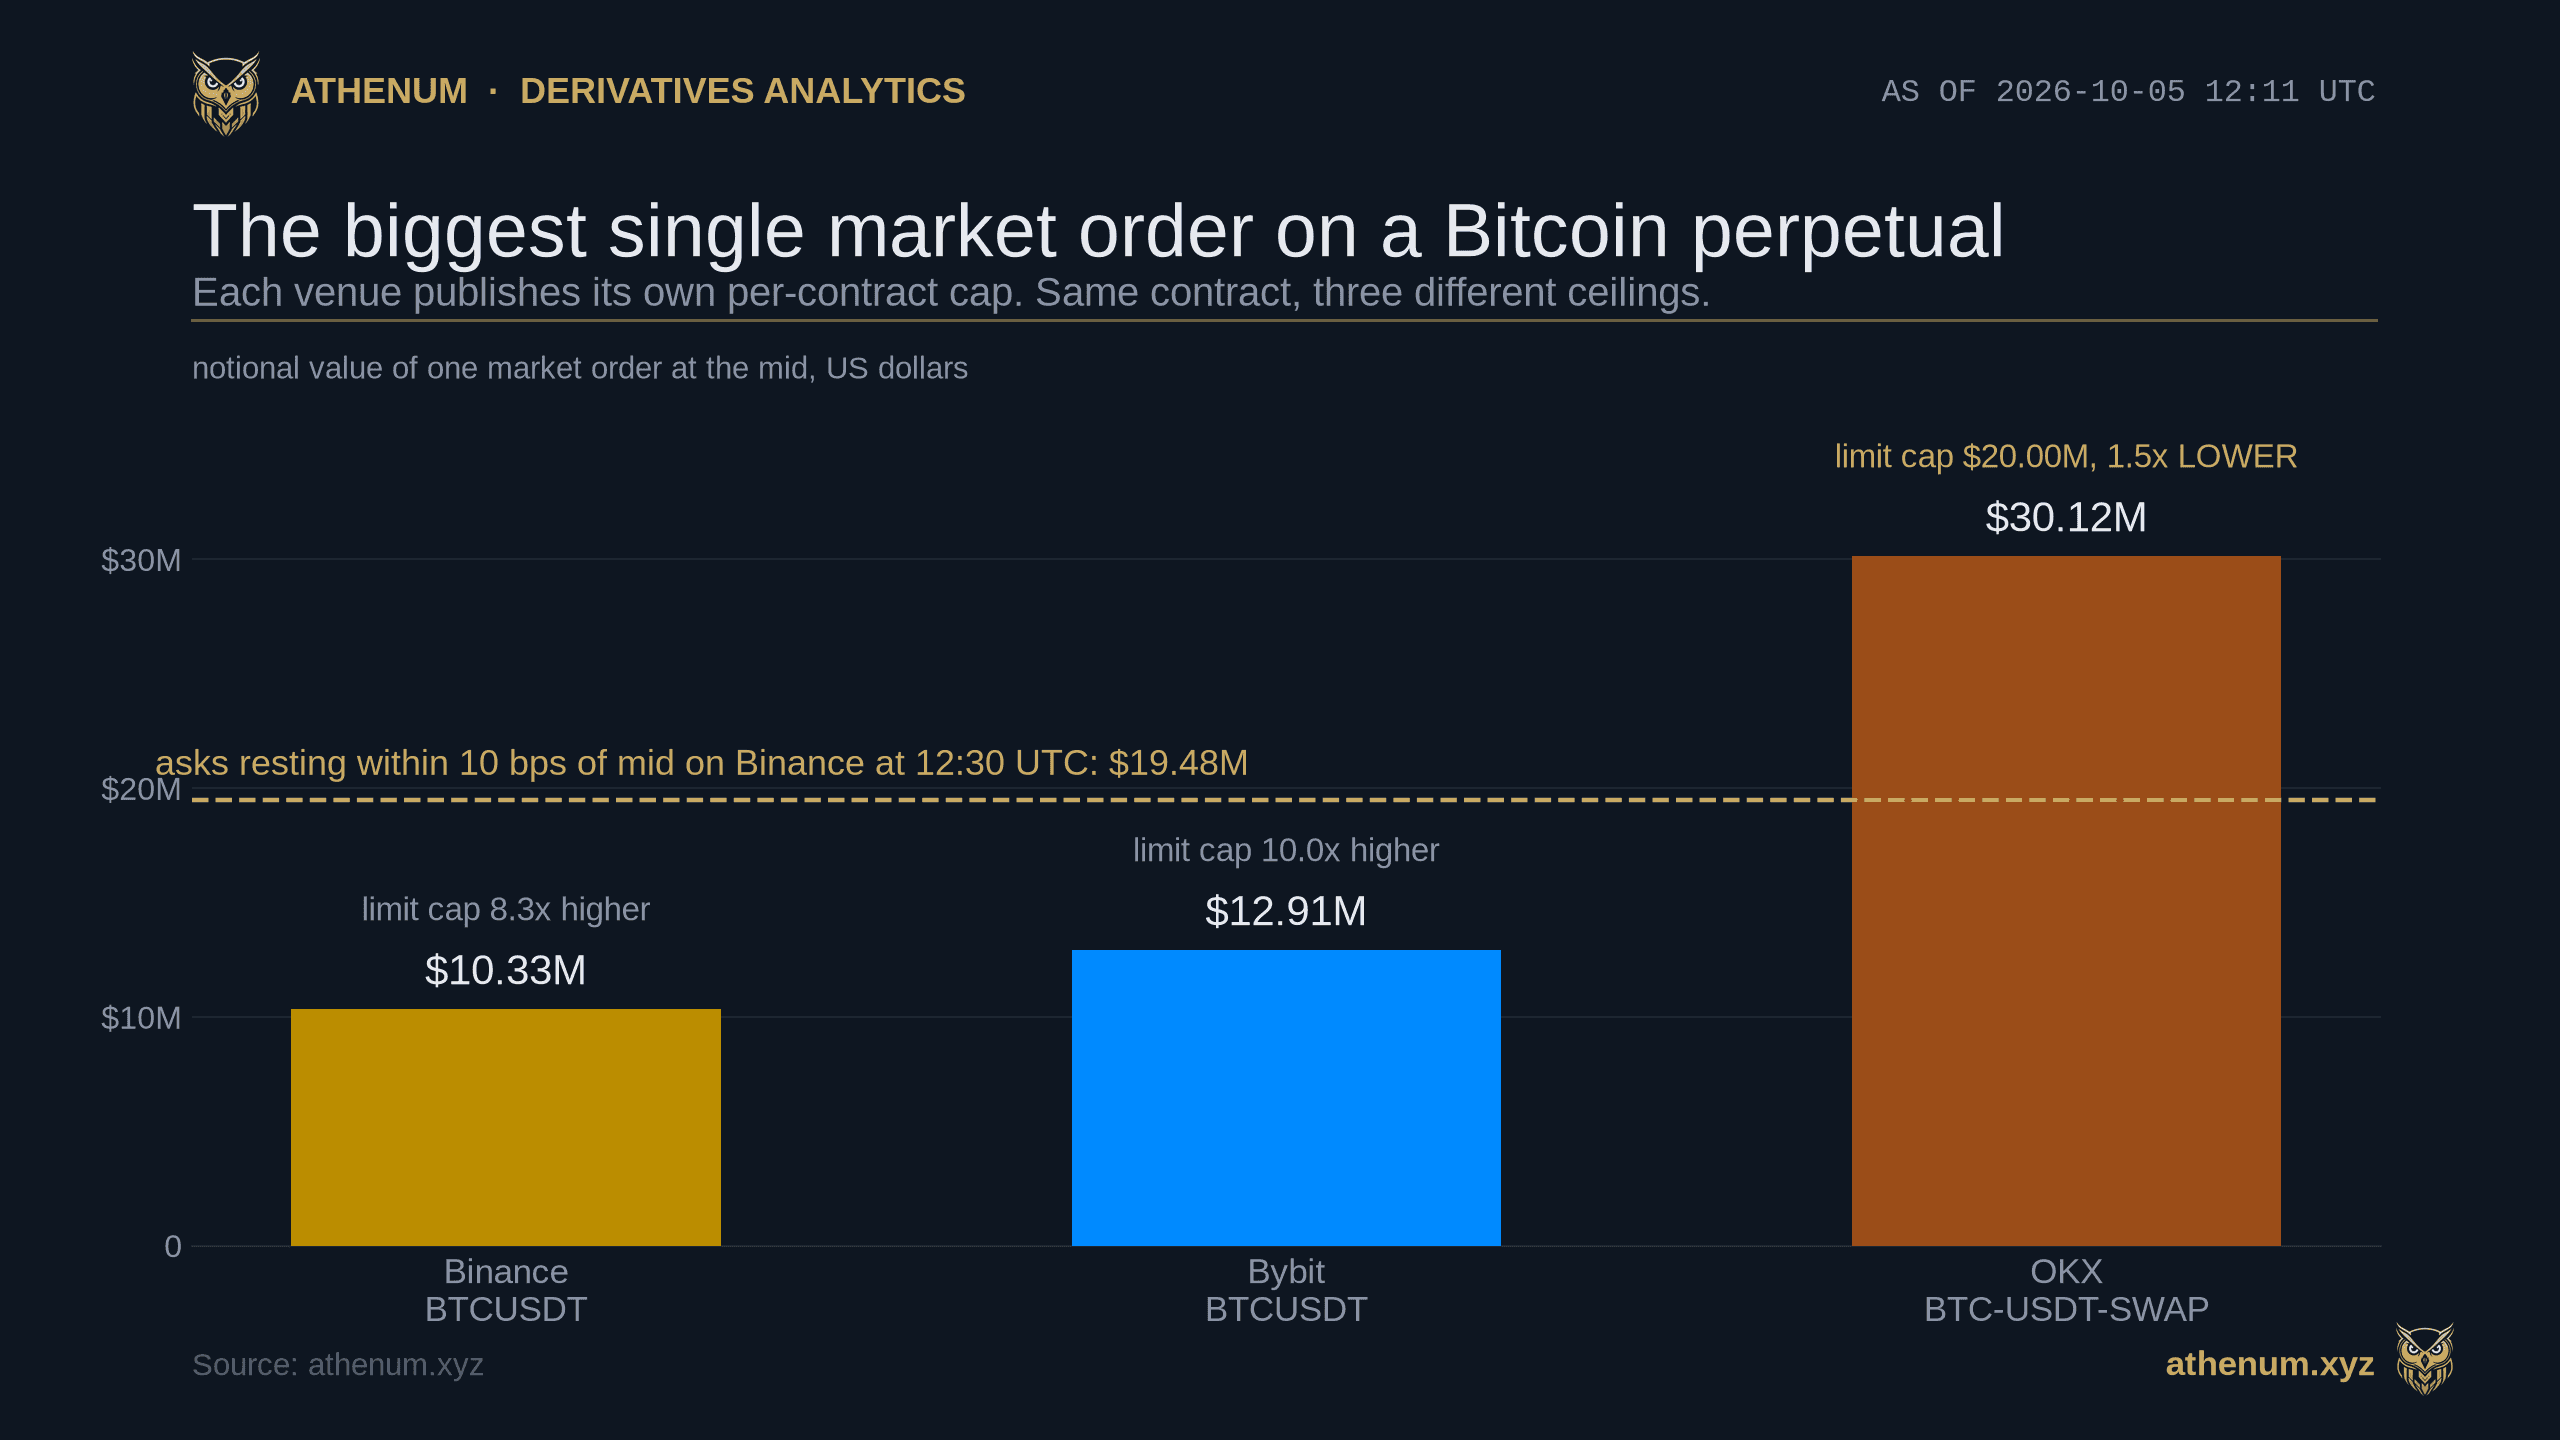
Maximum Market Order Size: Bitcoin Stops at $10.3M and a Typical Perp at $99,510
Binance, Bybit and OKX each publish a hard ceiling on how much one market order may take, and it is a different number from the limit order ceiling. On 2026-10-05 the Bitcoin perpetual stopped at $10.33M, $12.91M and $30.12M, while the median contract stopped at $99,510, $26,376 and $16,488.
Athenum Analytics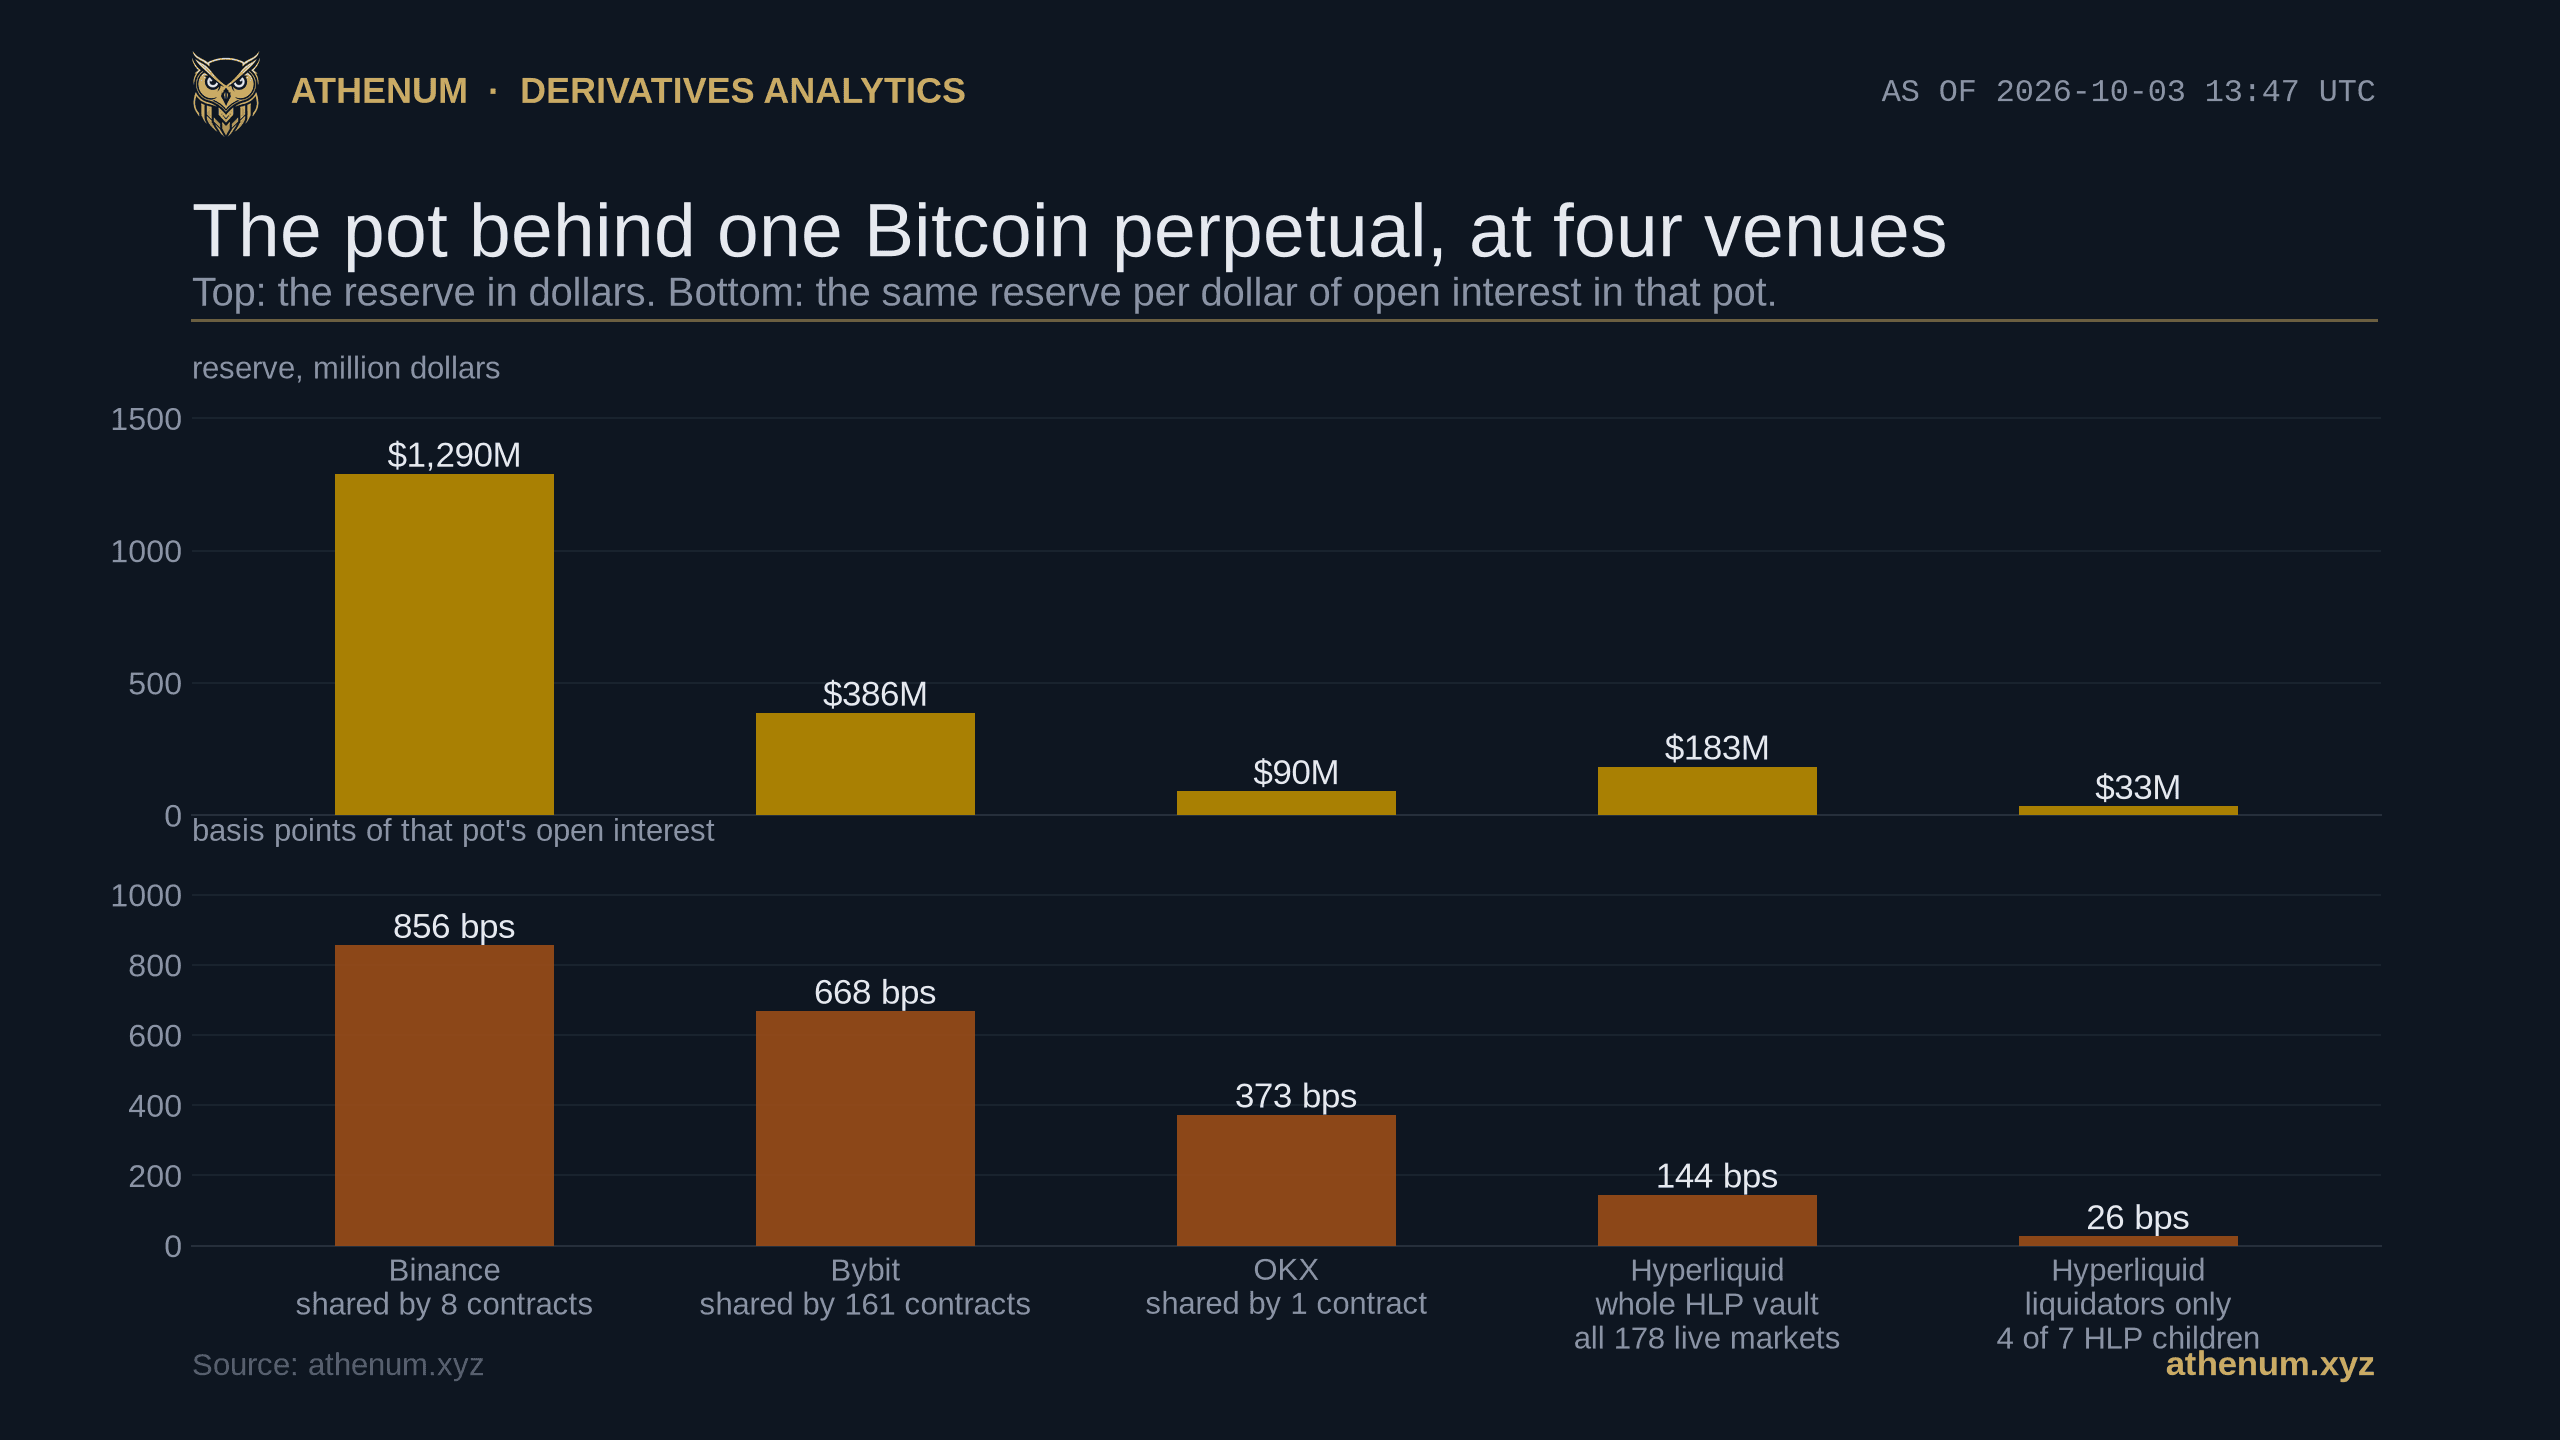
Crypto Insurance Funds Are Not One Pot: 123 at Binance, and Cover Varies a Hundredfold
The futures insurance fund is the reserve that pays the winner when a liquidation closes worse than its bankruptcy price, and when it runs out the venue reaches for auto deleveraging instead. Almost everything written about it, including two explainers on this blog, treats it as one number per excha
Athenum Analytics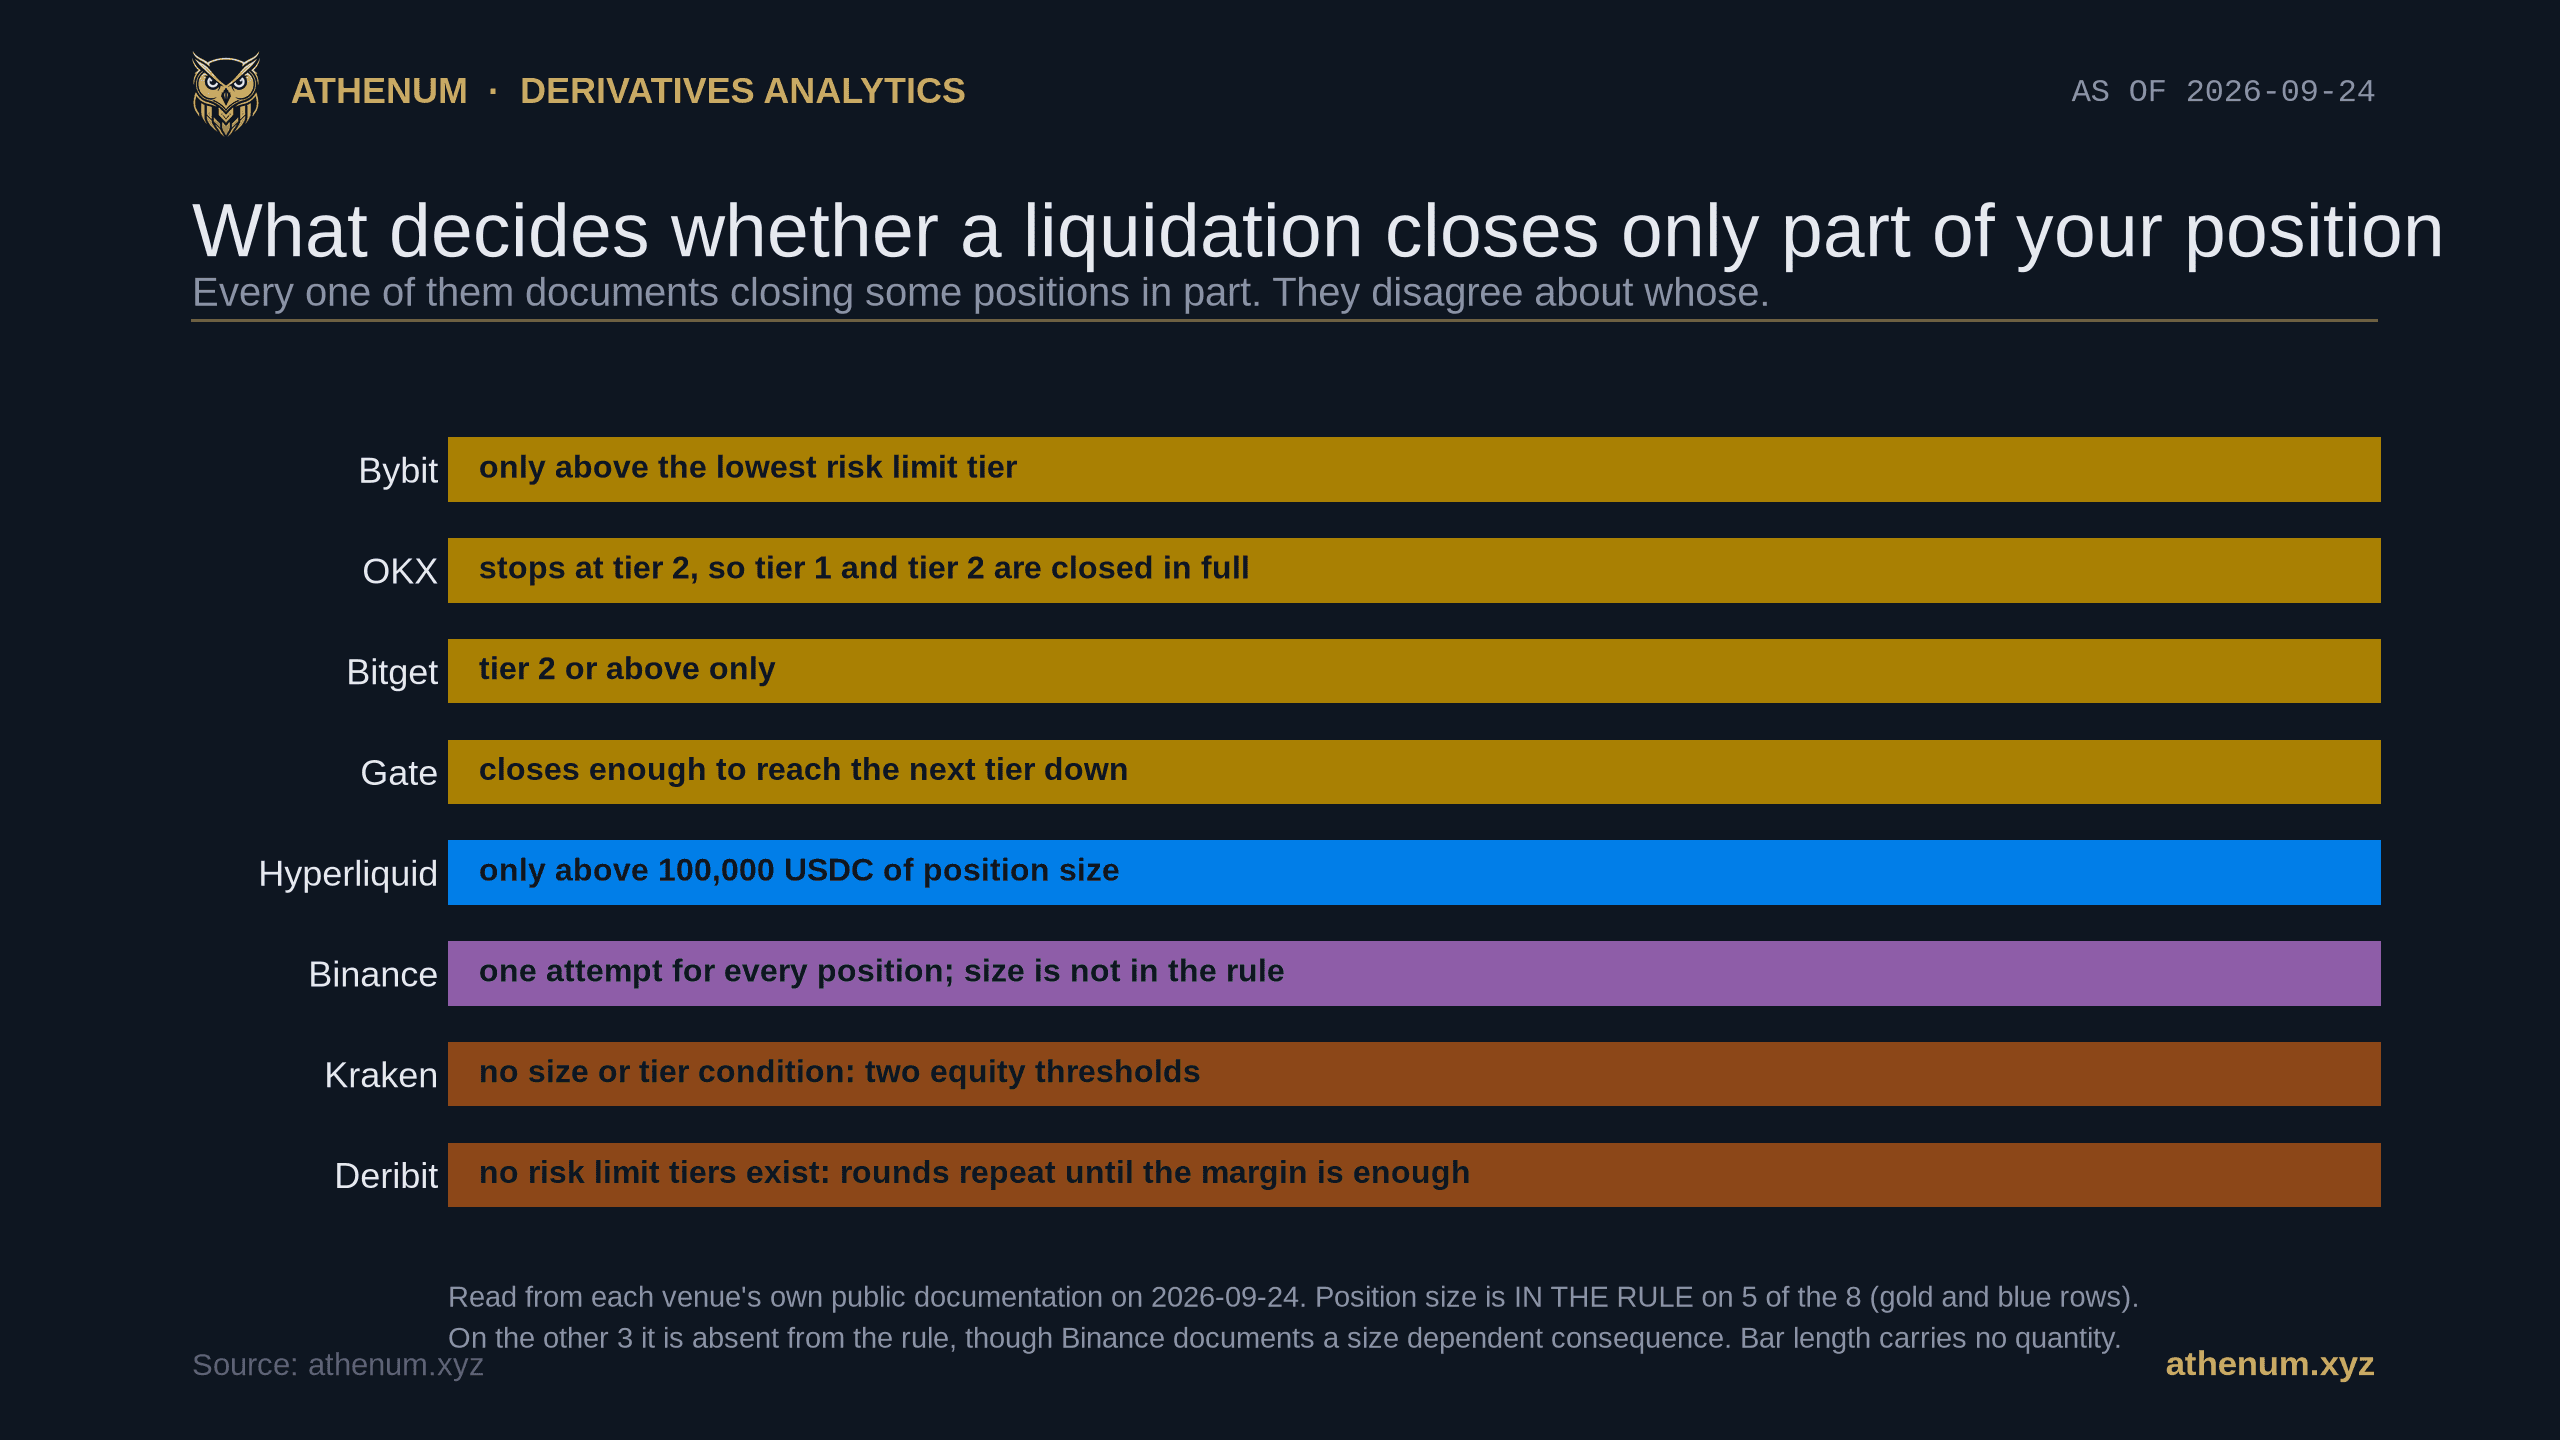
Who Gets a Partial Liquidation and Who Gets Closed All at Once
A liquidation does not always close your whole position. Reading eight venues' own liquidation documentation on 2026-09-24, all of them document closing some positions in part, and they disagree about whose. Bybit, OKX, Bitget and Gate gate the step on the risk limit tier, so a bottom tier position is closed in one action, and OKX stops a rung higher still, at tier 2. Hyperliquid gates on a flat 100,000 USDC of position size, and above it grants one slice before a 30 second cooldown in which orders go back to full size. Binance makes one Immediate or Cancel attempt for every position with no size term in its rule while documenting why smaller ones fare worse anyway. Kraken closes in fixed 10 per cent increments and Deribit repeats liquidation rounds until the requirement is met, neither with a size condition. Position size sits inside the rule itself on five of the eight venues we read and is absent from the rule on the other three.
Athenum Analytics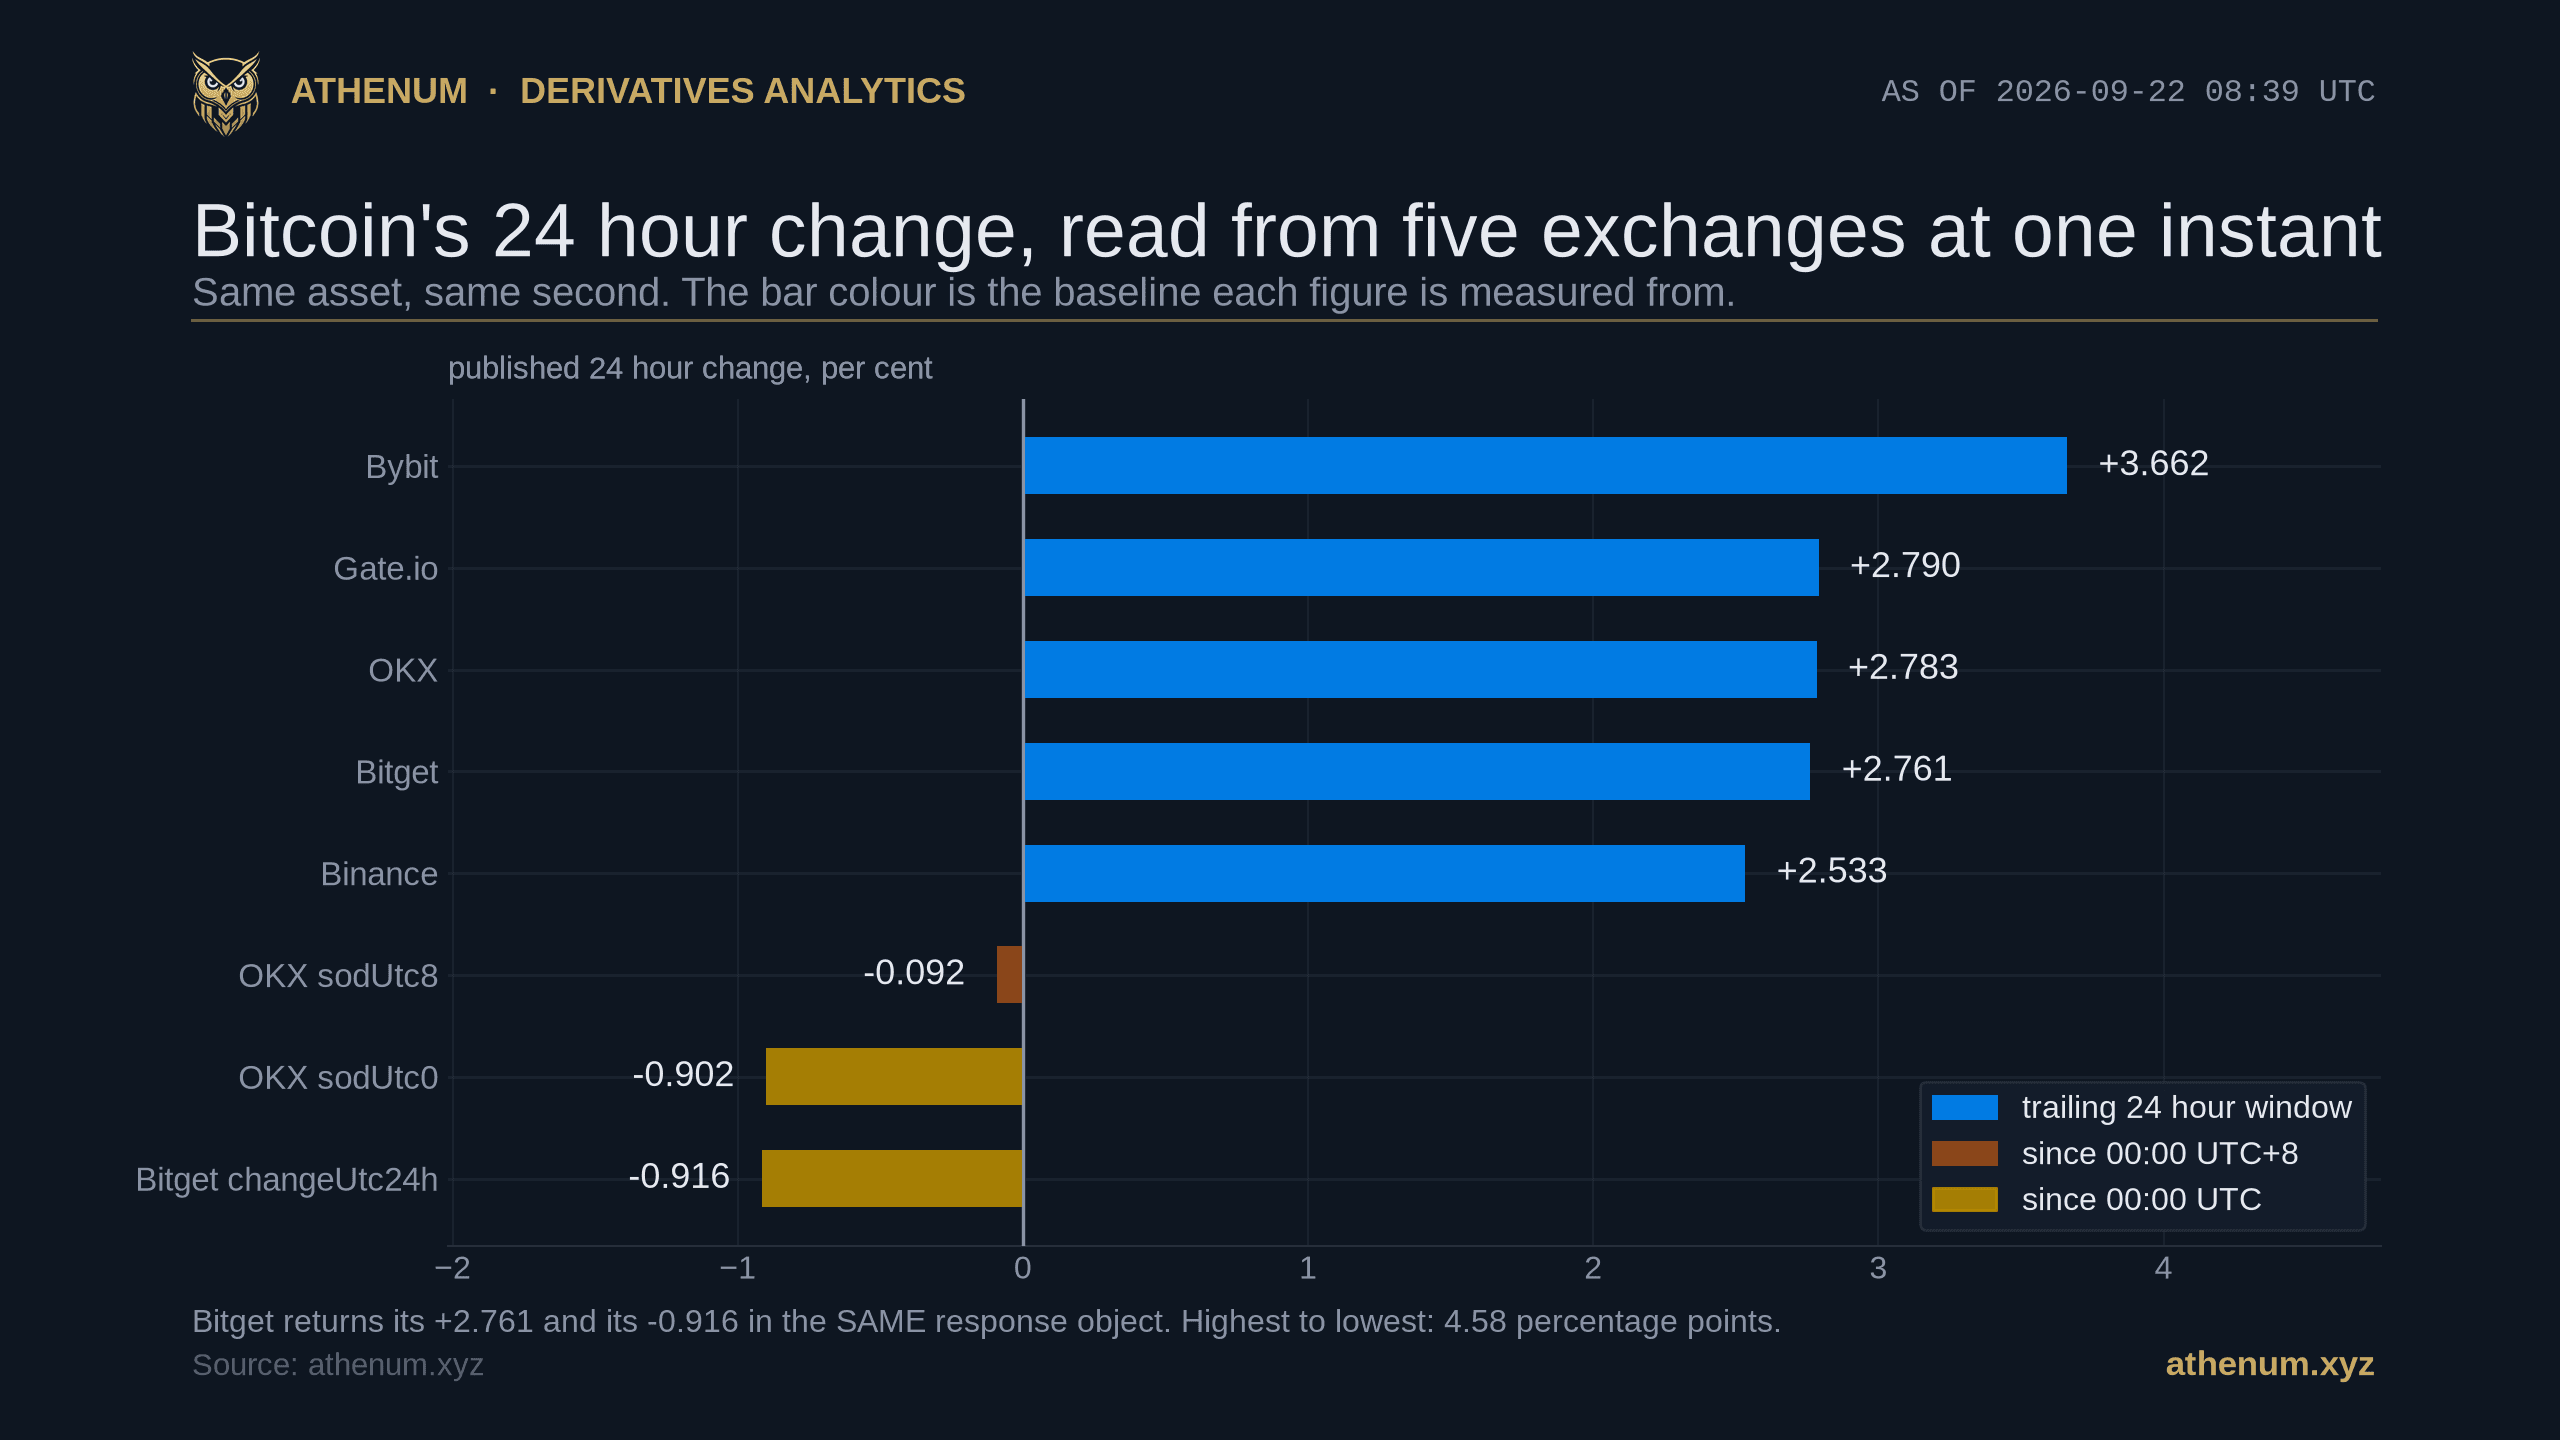
Bitcoin 24 Hour Change: Which Baseline, and Why It Flips the Sign 1 Hour in 4
A Bitcoin 24 hour change is a two point statement, and exchanges disagree about the first point. Some measure from a trailing 24 hour window, some from the price at 00:00 UTC, and OKX also publishes one from 00:00 UTC+8. Read at 2026-09-22 08:39:25 UTC in a 3.0 second capture, the BTC/USDT perpetual carried +3.662 per cent on Bybit and -0.916 per cent in Bitget's since-midnight field, a spread of 4.58 percentage points on the same asset at the same second, with Bitget returning both of its figures in one response object. This is not an edge case. Over the 8,760 hourly readings from 2025-09-22 09:00 UTC to 2026-09-22 08:00 UTC the two baselines differed by a median 0.663 percentage points, by more than 1 point at 37.1 per cent of readings and by more than 2 at 16.3 per cent, and they carried OPPOSITE SIGNS at 2,240 of 8,760, or 25.6 per cent. The disagreement is strongly patterned by the clock: at 01:00 UTC the two figures pointed opposite ways on 51.0 per cent of days, at 23:00 UTC on 4.9 per cent. The same split runs through metrics other than price. Athenum's own cross-venue Bitcoin perpetual open interest at 2026-09-22 07:00 UTC reads +6.96 per cent against 24 hours earlier and -0.81 per cent against 00:00 UTC, from one series at one stamp.
Athenum Analytics
USDC vs USDT Funding: One Exchange, Two Bitcoin Rates at the Same Settlement
USDC vs USDT funding is not a distinction most dashboards make, and it should be. A Bitcoin perpetual quoted in USDC and a Bitcoin perpetual quoted in USDT on the SAME exchange are two books with two premium indices and two quote-currency reference prices, so they charge two different rates at the s
Athenum Analytics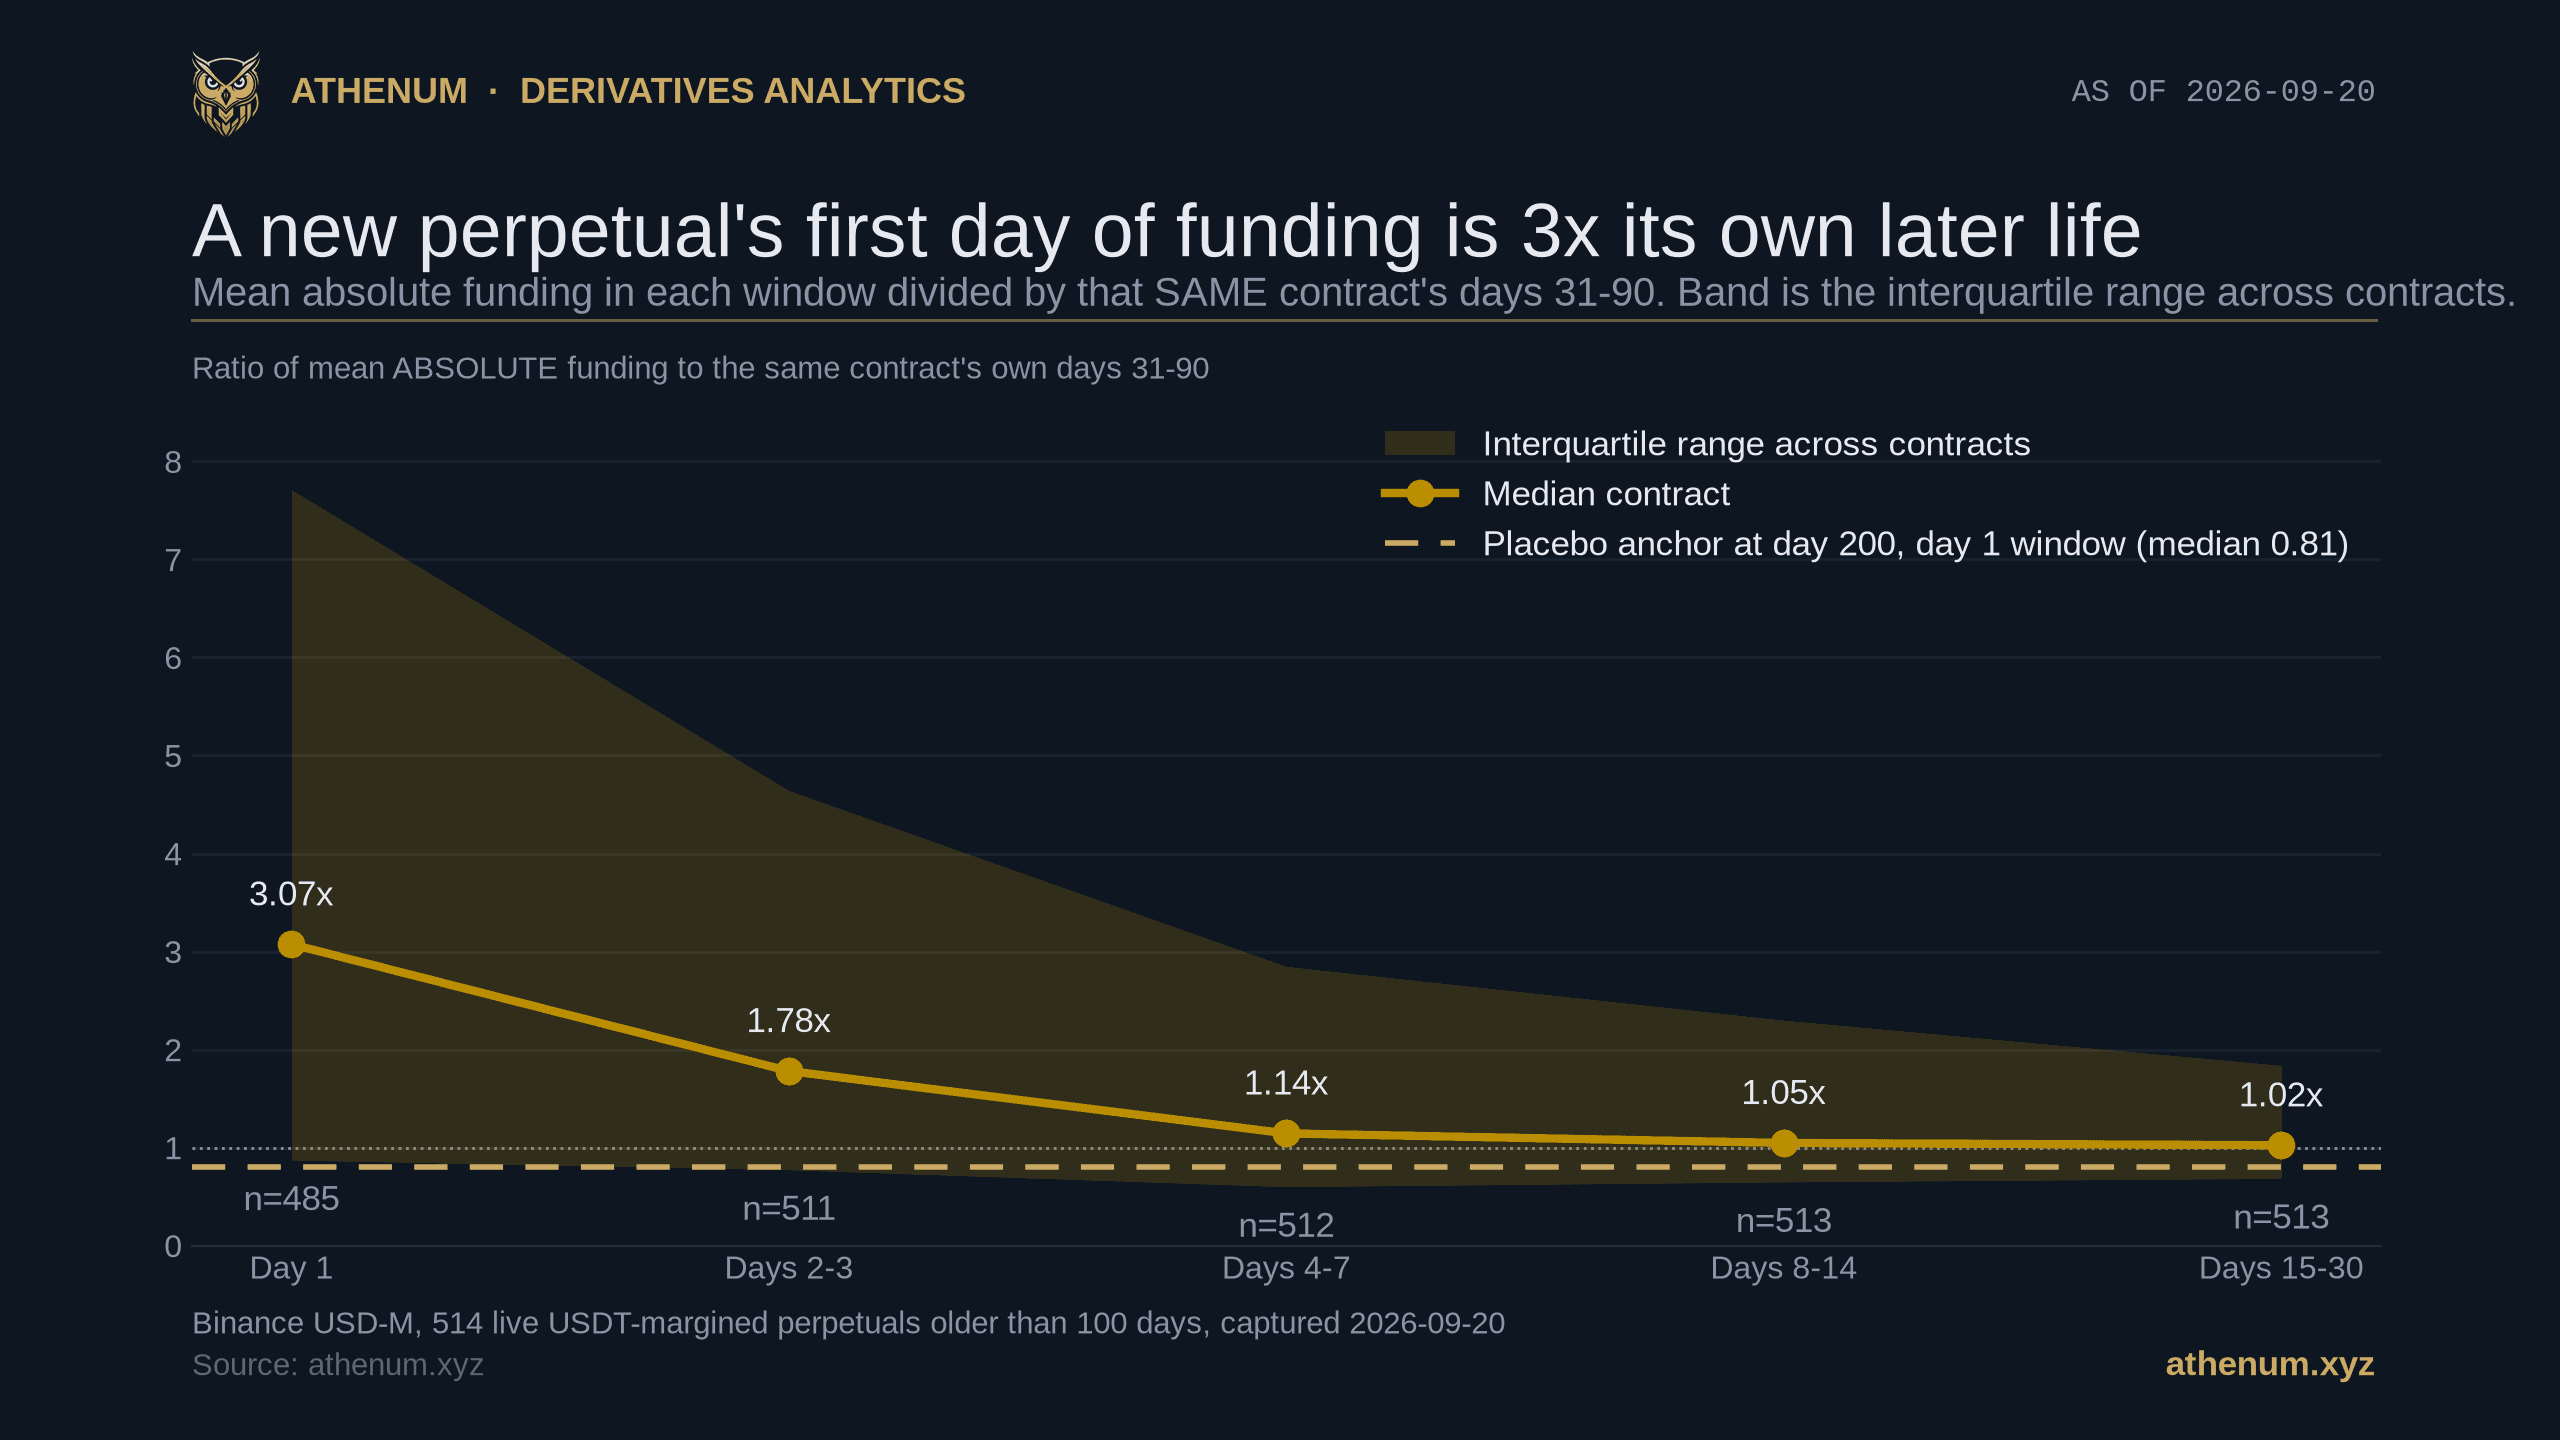
New Perpetual Listings: Day One Funding Is 3x the Contract's Own Later Life
New perpetual listings carry their most violent funding in the hours after they list, and the size of that is measurable rather than folkloric. We read all 528 live USDT-margined perpetuals on Binance's USD-M board on 2026-09-20, kept the 514 with enough history, and compared each contract against i
Athenum Analytics
When Is Funding Charged on a Bitcoin Perp? At the Stamp, and Dodging One Costs 8 Times More
Perpetual funding is not rent that accrues while you hold. It is a transfer taken from whoever is open at the settlement stamp, so a position opened and closed between two stamps pays nothing at all, and a position held for ten minutes across one pays the full interval rate. That makes the interval
Athenum Analytics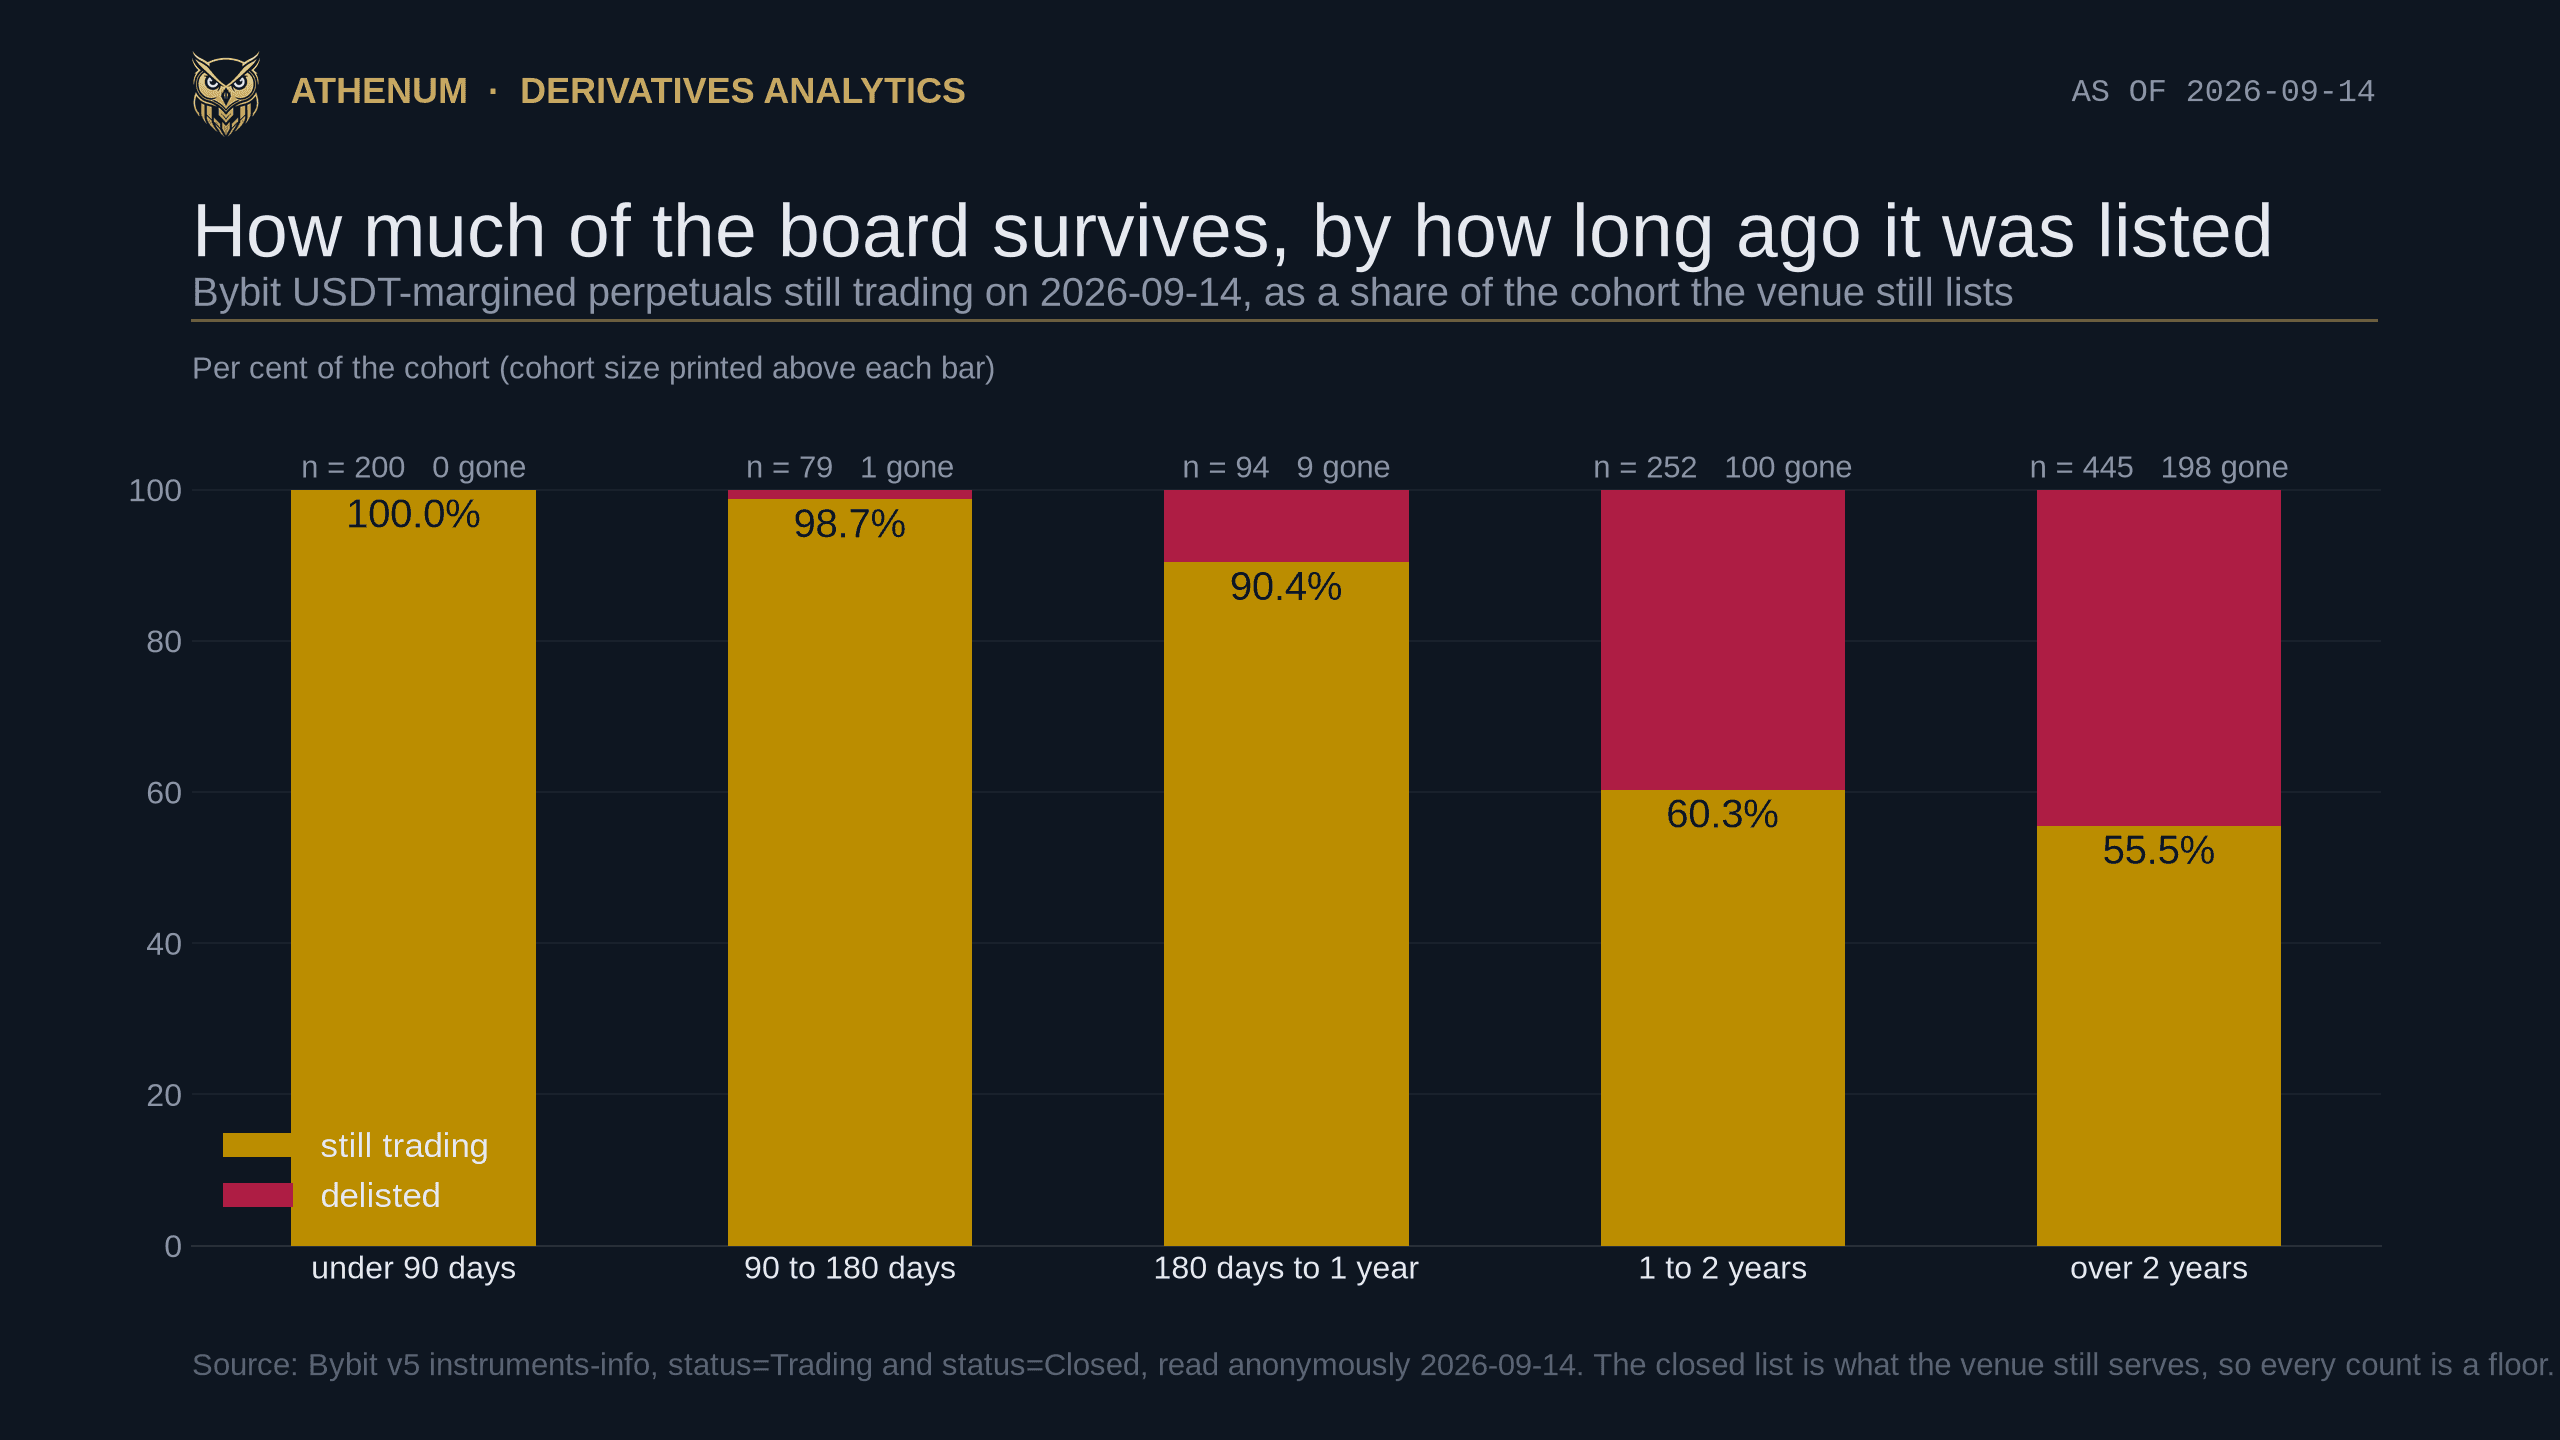
Perpetual Futures Survivorship Bias: 172 of Bybit's 571 One Year Contracts Are Already Gone
If you build a universe of perpetual contracts by calling a venue's live instrument endpoint, you are sampling survivors, and on 2026-09-14 the size of that is measurable rather than theoretical.
Athenum Analytics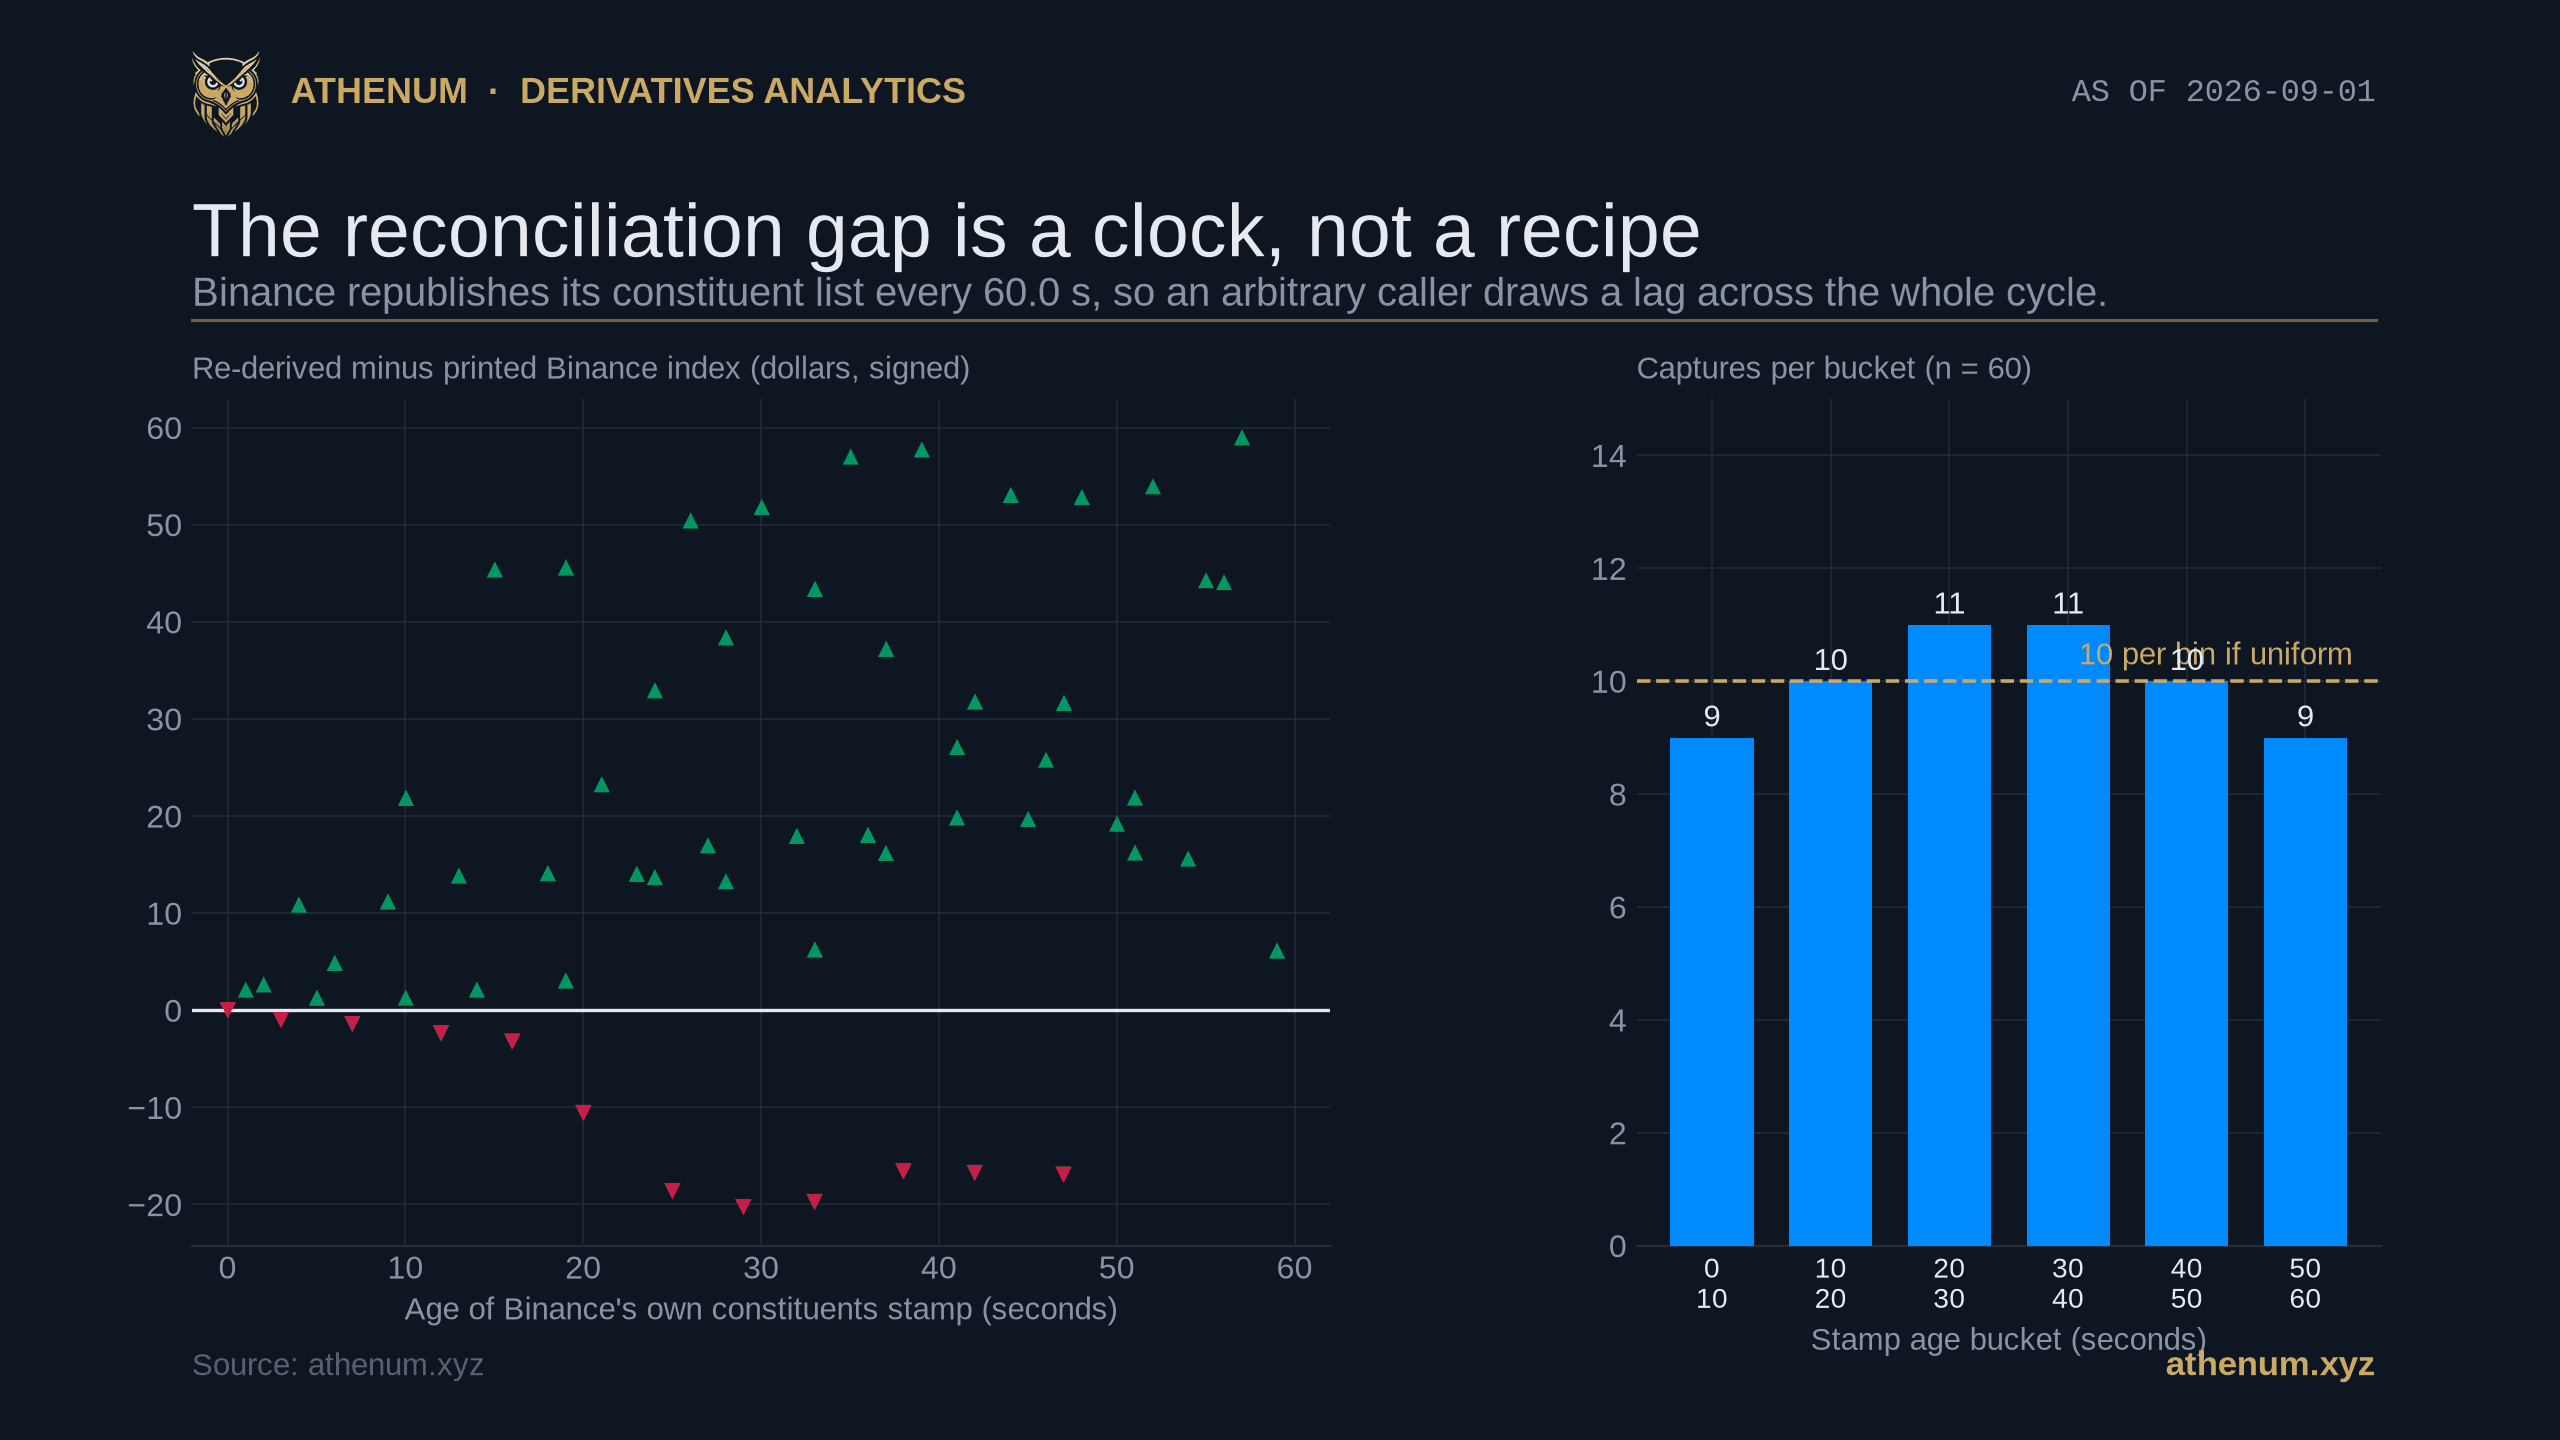
Bitcoin Index Price: One Venue's Sum Closes Exactly, One Is 60 Seconds Behind
A perpetual is liquidated against an index, and two large venues publish the recipe for that index on endpoints that need no key, so you can in principle audit the number that closes your position. We showed in August that those recipes are fixed preset weight grids rather than volume weighted averages, and that the sums reproduce. This post measures the thing that write up left as a phrase, "seconds of drift", and the answer is a fixed clock. On 2026-09-01, across 60 concurrent captures, Binance's constituents endpoint republished on a period of 60.0 seconds, five distinct timestamps with fou
Athenum Analytics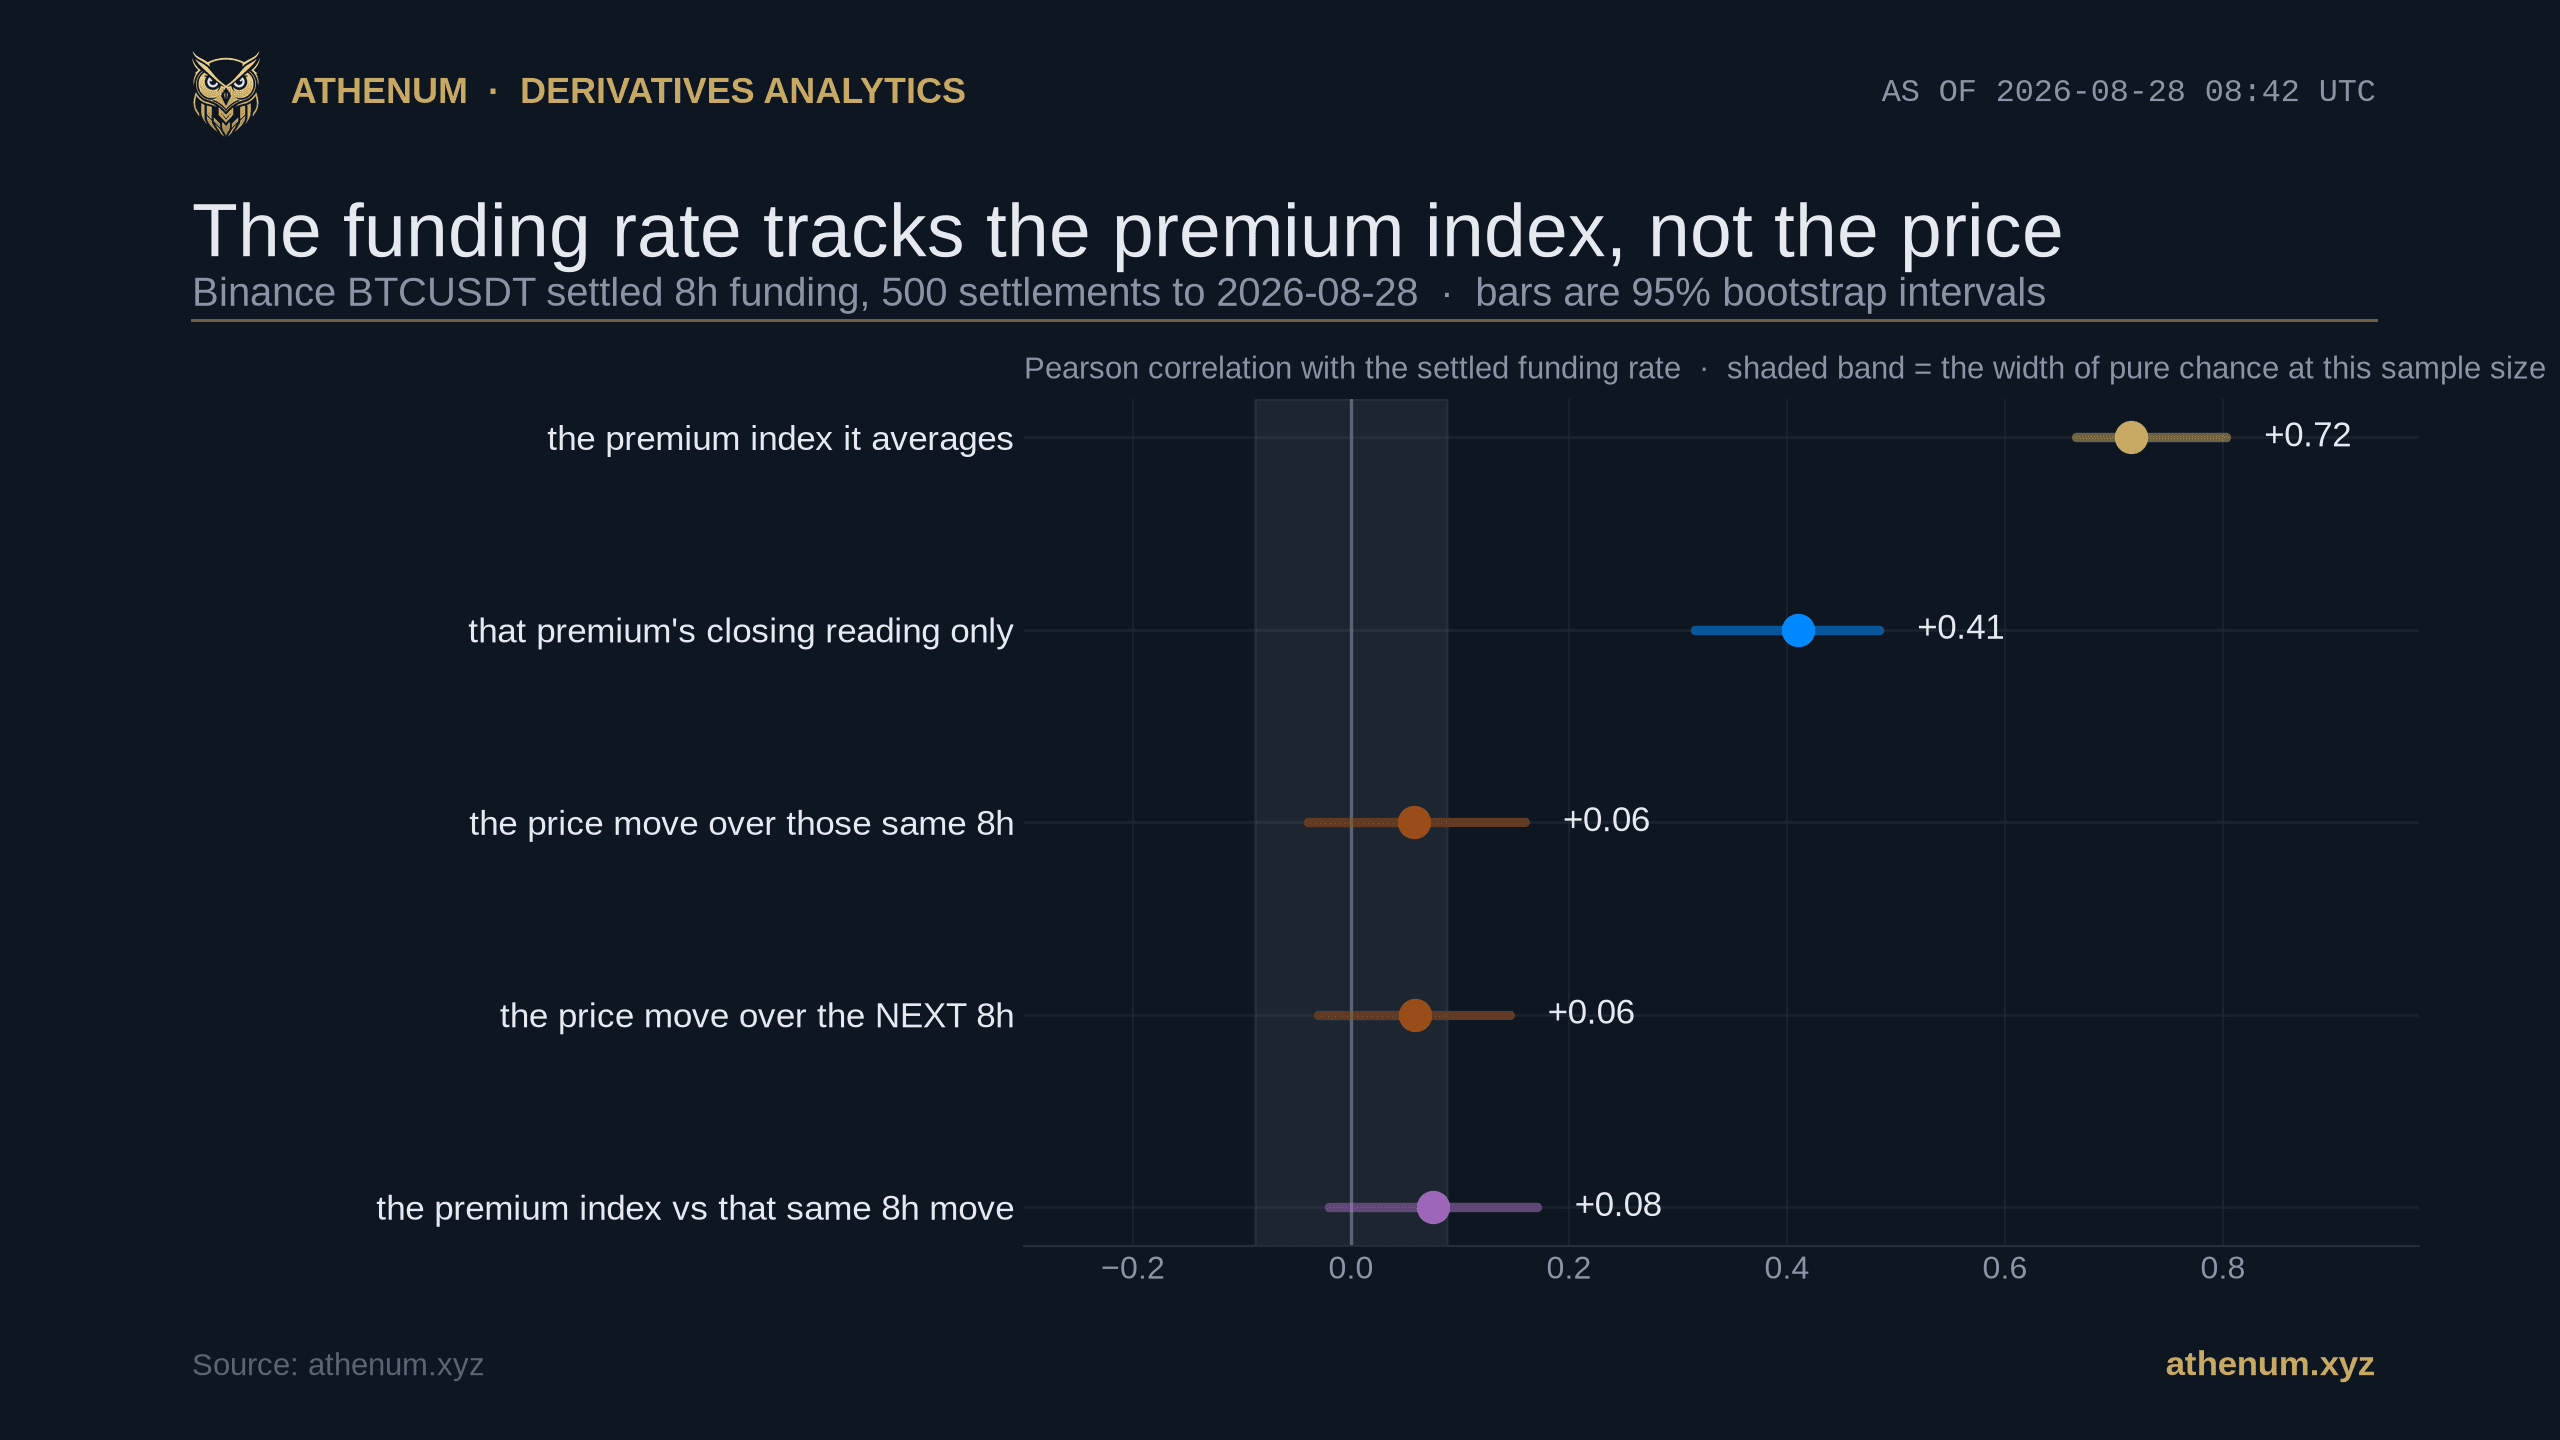
Bitcoin Funding Rate vs Price: 0.72 to the Premium Index, 0.06 to the Move
The Bitcoin funding rate is the fee perpetual longs and shorts exchange every eight hours, and almost every description of it, ours included, says it measures crowding or conviction and then invites you to read that forward as a statement about price. This post tests only that second step. Measured on 2026-08-28 over 500 Binance BTCUSDT settlements back to 2026-03-15, the settled rate correlates +0.72 (95 percent interval +0.67 to +0.80) with the premium index it is built from.
Athenum Analytics